All about this insurance: Contents insurance
Do I need contents insurance as a renter in Germany?
Personal
Personal liability Contents insurance Buildings insurance Natural hazard cover Solar panel insurance Self-build insurance Car insurance Bicycle and e-bike Travel insurance Drone insurance Dog and horse liability Pet health insurance Legal expenses insurance Accident insurance Occupational disability Term life insurance Funeral insurance Private pension Private health insurance Supplementary health Dental insurance Long-term careBusiness
Business liability Professional indemnity D&O insurance Business legal expenses Business contents Commercial buildings Business interruption Electronic equipment Machinery breakdown Contractors all risks Cargo insurance Fleet insurance Cyber insurance Trade credit insurance Company pension (bAV) Company health insurance Group accident insurance By type of businessGuides
Which insurance do I need? Who pays for the damage? Insurance you may not need Cancellation deadlines Insurance questions Compare the wordings of all tariffsInsurers
German insurers A to Z Austrian insurers Spanish insurers Complaints rankingContact
+49 3375 29 12 77 Contact Customer loginLanguage
Deutsch Österreich Español Boats and yachtsInsurance broker / Insurance questions / Contents insurance
In short
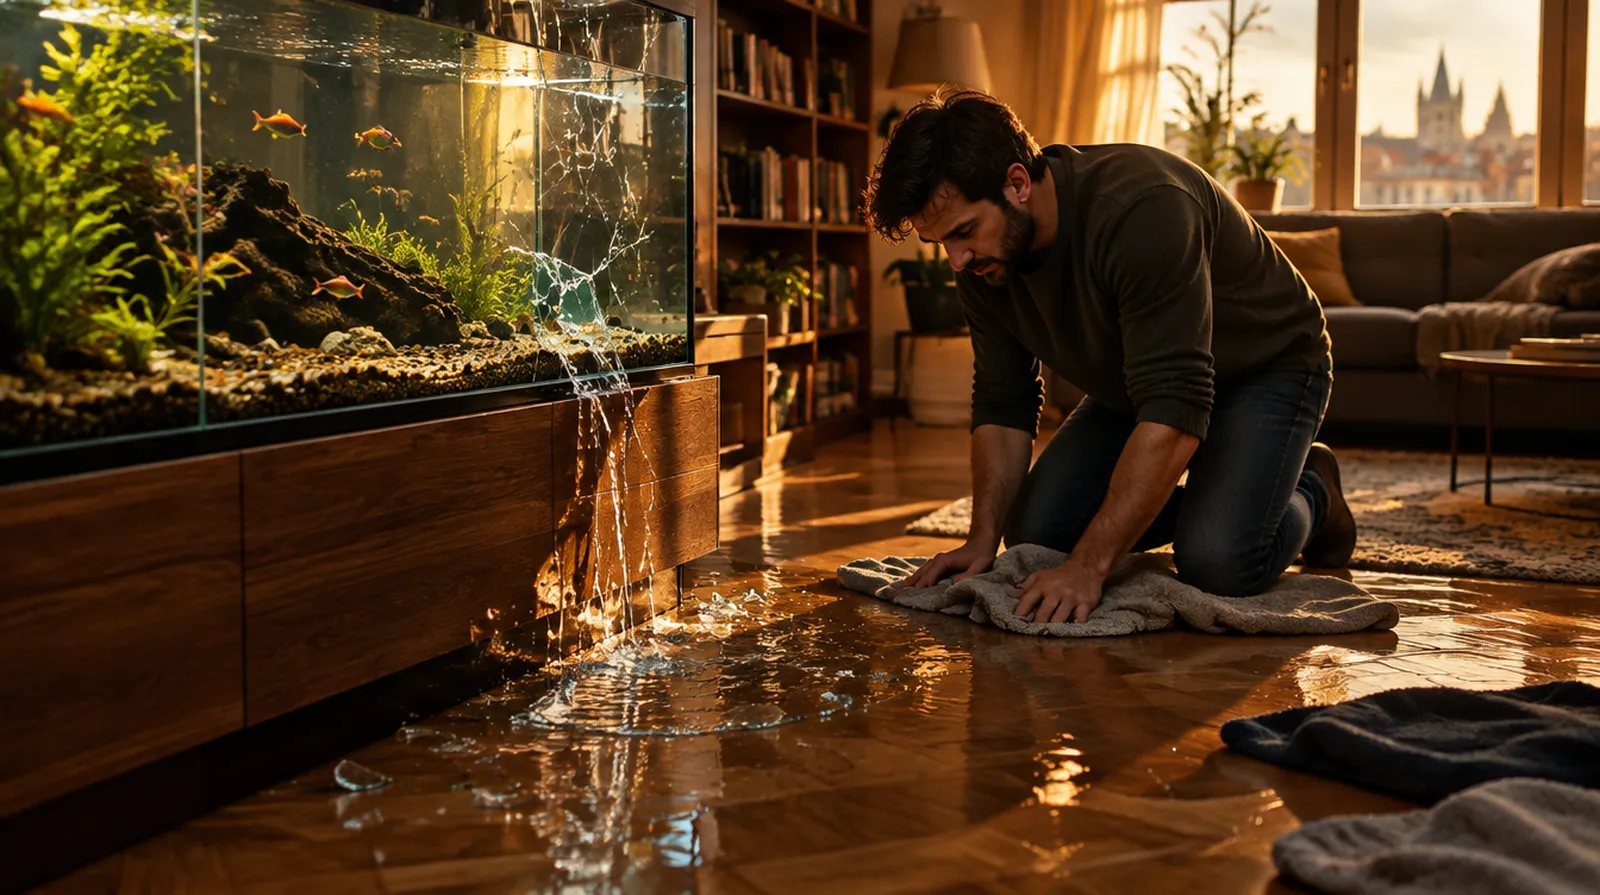
Usually yes. If your aquarium leaks, German model terms (VHB 2022) treat the water as Leitungswasser, so your contents insurance (Hausratversicherung) pays for wet furniture and electronics, and the building insurance pays for floors and walls. Fish and plants are excluded. Damage to your neighbour is paid by your personal liability insurance only if the leak was your fault.
What water damage costs and what cover costs in Germany, according to published figures.
| Example | Typical range |
|---|---|
| Professional drying with equipment and measurements | about EUR 1,500 to 5,000 |
| Renting a dehumidifier yourself | about EUR 50 to 150 per unit and week, plus EUR 5 to 15 electricity a day |
| Leitungswasser damage to residential buildings in Germany, 2024 | around EUR 4.9 billion |
| Contents insurance, 2 rooms, 65 square metres | about EUR 70 to 140 a year |
| Tank size from which a surcharge is possible | from about 1,000 litres |
As of October 2026.
The amounts in the worked example are guide values from quoting practice.
Whether your policy includes aquariums is stated in your terms under Leitungswasser;
we obtain the exact quote.
Worked example
The water runs over the laminate into the flat below. The seam was well kept, no fault is apparent.
| Sofa, rug and sideboard soaked | EUR 1,800, paid by her contents insurance |
| Laminate and drying the screed | EUR 3,000, paid by the landlord's building insurance |
| Ceiling and belongings of the neighbour | EUR 2,500, paid by the neighbour's building and contents insurance |
| Fish, plants and a new tank | EUR 700, she pays herself |
Of EUR 8,000 in damage, EUR 700 stays with her, plus any agreed deductible. Had the leak been her fault, her liability insurance would have paid the EUR 2,500 for the neighbour.
The model terms of the German Insurance Association (GDV) define Leitungswasser as water that escapes where it should not. Besides pipes, heating and appliances, they name waterbeds and aquariums expressly. This applies in the contents terms VHB 2022 and in the building terms VGB 2022 alike.
Your own policy can differ. Older terms and some tariffs treat aquariums differently, and many insurers want the tank stated in the application with its volume. From around 1,000 litres, also counting several tanks together, a surcharge may apply.
| What is wet or broken | Who pays | Condition |
|---|---|---|
| Your furniture, rugs, electronics | your contents insurance | Leitungswasser in the policy |
| Fish, plants, substrate | nobody | excluded for water from your own tank |
| Cracked glass pane | glass insurance | only if the aquarium is named in the policy |
| Leaking silicone seam | nobody | no breakage, so no glass claim |
| Floors, walls, ceiling in your own house | your building insurance | Leitungswasser in the policy |
| Floor and ceiling of a rented flat | the landlord's building insurance | recourse against you only for gross negligence or intent |
| The neighbour's belongings and rooms | their insurance, your liability insurance if you are at fault | you are liable for the damage |
Pets such as fish are part of your household contents. But the model terms exclude damage to the contents of an aquarium caused by water escaping from that aquarium. If the fish die because the tank runs dry, contents insurance does not pay for them. In a fire they would be covered.
The tank itself is not a water claim either. If the pane breaks, only glass insurance helps, and there aquariums are not standard items, they must be named in the policy. A seam that merely leaks is no breakage and not covered at all.
If the water runs into the flat below, fault decides. Under § 823 (1) BGB, anyone who damages another person's property intentionally or negligently must pay. Leaving the hose running unattended during a water change can be negligent. If a well kept seam fails without warning, there is often no fault. Each case is judged on its facts.
If you are liable, your personal liability insurance (Privathaftpflicht) pays the neighbour. If you are not, it checks the claim and defends you against it. The neighbour then claims from their own contents insurance, since aquarium water is Leitungswasser for them too. If their insurer pays and you are liable, it can recover the money from you under § 86 VVG, and your liability insurance steps in again.
Liability insurance never pays for your own belongings, it only covers claims by others.
Soaked laminate, screed or the ceiling below are building damage. The landlord's building insurance pays. According to rulings of the Federal Court of Justice of 13 September 2006, including IV ZR 273/05, the building insurer implicitly waives recourse against a tenant who was only slightly negligent. For gross negligence or intent it can claim from you.
For that case your liability policy should include damage to rented living space (Mietsachschäden). The model terms provide for it, each tariff sets its own limit.
For a small tank of 50 or 60 litres, extra cover is not worth it. Three things matter: Leitungswasser in your contents policy, liability insurance with damage to rented property and, if your fish are valuable to you, knowing that they will not be replaced after a leak.
Glass insurance just for the aquarium rarely pays off, because a leaking seam is more common than a broken pane and would not be covered anyway.
Questions and answers
Not if they die because water escapes from your own tank.
The model terms exclude that.
For other perils such as fire, fish are covered as pets.
The neighbour claims their belongings from their contents insurance,
ceiling and walls go to the building insurance.
If the leak was your fault, those insurers recover the money from you,
and your liability insurance pays.
No.
Liability insurance only covers damage you cause to others.
For the tank itself only glass insurance can help,
if the pane breaks and the aquarium is named in the policy.
Many insurers ask in the application and want to know the volume.
From about 1,000 litres a surcharge may apply.
Leaving out a large tank risks a dispute after a claim.
Then the water did not come from the aquarium.
The model terms exclude splash and cleaning water, so contents insurance usually does not pay.
Yes.
The model terms name waterbeds and aquariums together as sources of Leitungswasser.
NAMMERT insurance broker
We compare insurers and come back to you, in English.
Free; the insurer pays our fee.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.
All about this insurance: Contents insurance
Do I need contents insurance as a renter in Germany?
What does contents insurance pay for water damage in Germany?
What does contents insurance pay for water damage in Germany? After a burst pipe or leaking…
Is glass insurance worth it in Germany?
For many tenants, probably not. Glass insurance (Glasversicherung) costs about EUR 40 to 65 a…
What does contents insurance cover in Germany?
German contents insurance (Hausratversicherung) covers everything movable in your home…
What should I do after a contents insurance claim in Germany?
Report the damage right away and call the police on 110 after a burglary. Limit the damage…
Updated
Was this useful?