Contractors all risks in Germany: who pays when the work is damaged before handover
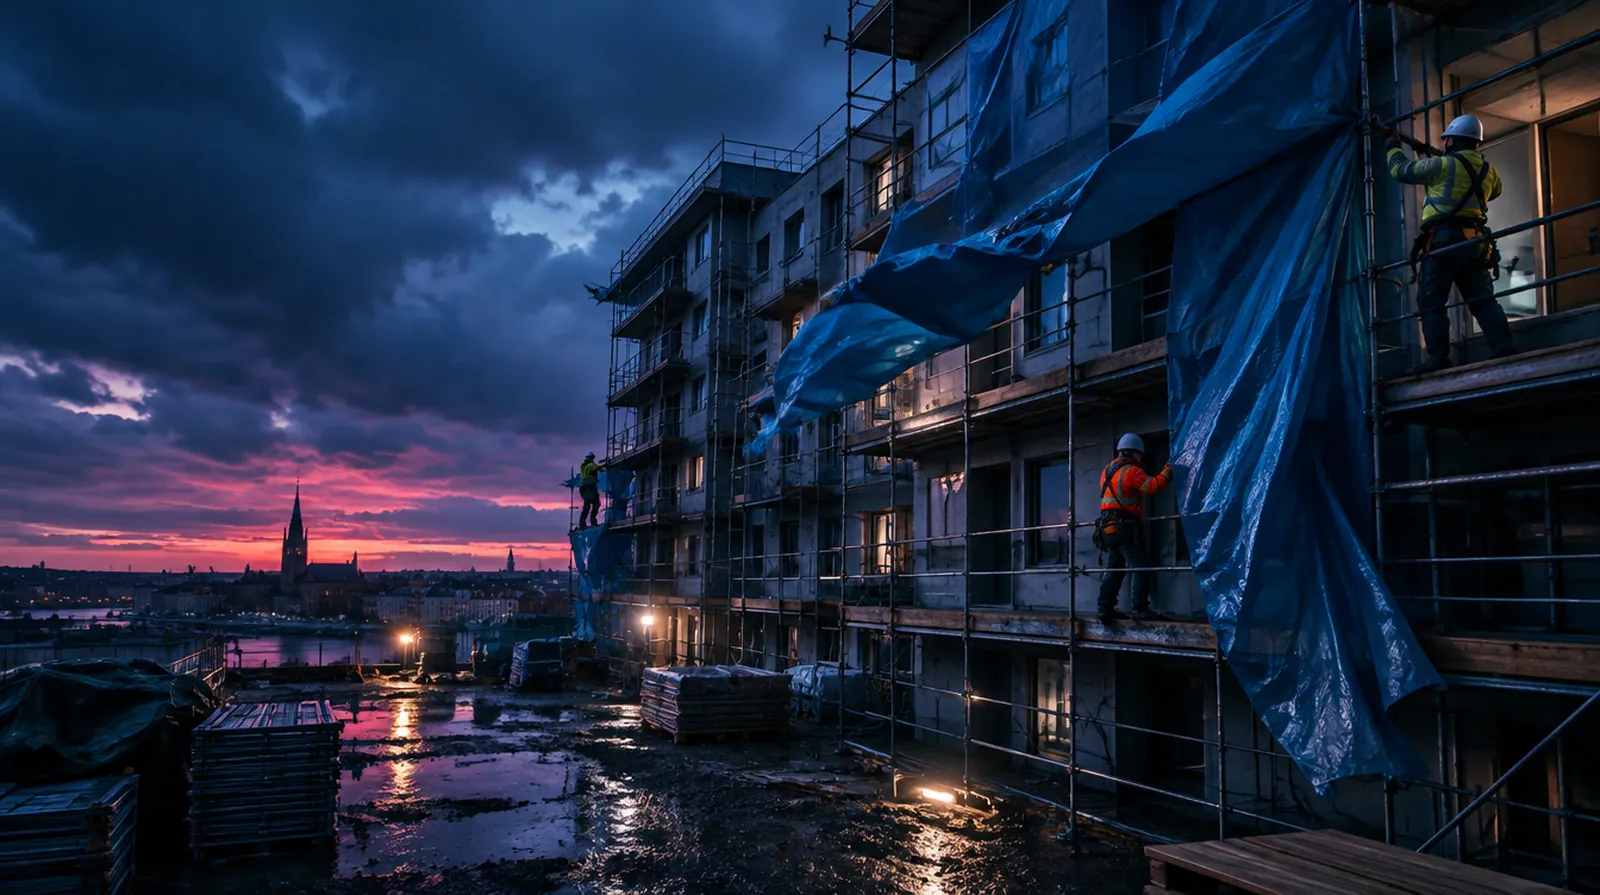
Under German law the contractor carries the risk for his work until the client formally accepts it, and must rebuild at his own cost if it is destroyed. Bauleistungsversicherung, the German form of contractors all risks cover, pays for damage to the works from storm, heavy rain, vandalism, theft of installed parts or design errors. It is not compulsory, but many German clients require it in the building contract.
Do I need my own contractors all risks policy if the client already has one?
Usually not, as long as the client's policy covers all trades and includes your work. That is standard with the client version under ABN terms, and the premium is then often deducted as a share from your final invoice. Check the deductible, because it is often charged to the contractor who caused the loss. If you regularly work on sites without such a policy, you need your own cover under ABU terms, usually as an annual policy for all projects.
Abnahme: the moment the risk passes
German construction law revolves around Abnahme, the formal acceptance of the work by the client. Until then, § 644 of the Civil Code (BGB) places the risk of accidental destruction on the contractor. If a finished wall is knocked down by vandals or blown over in a storm before Abnahme, the contractor rebuilds it without extra payment. Practical completion as known in UK contracts does not shift this risk.
Most German commercial building contracts incorporate the VOB/B, standard terms for construction work. § 7 VOB/B lets the contractor keep his right to payment for executed work destroyed by force majeure, war, riot or other objectively unavoidable events. Courts read this narrowly: ordinary bad weather, theft or vandalism on an unsecured site usually do not qualify, and § 4 (5) VOB/B obliges the contractor to protect his work against damage and theft until acceptance.
Client policy or contractor policy
A client policy under ABN terms covers the entire project and all contractors on site in one contract. That avoids the typical German site dispute over which trade caused the water damage in the screed. Clients frequently pass a share of the premium on to contractors through a deduction written into the contract.
A contractor policy under ABU terms covers only your own work. Firms with several sites at any time usually take an annual policy based on turnover, with a maximum sum per project, so no site starts uninsured.
Refurbishment and existing buildings
When you work on an existing building, the building itself is not part of the insured works. If rain enters through an opened roof and damages the flats below, that loss is covered only if the policy explicitly includes existing structures. For conversions and refurbishments this extension is often the most important part of the cover.
What it does not replace
Contractors all risks is property cover for the works. Damage your team causes to neighbouring buildings, utilities or passers-by falls under business liability insurance (Betriebshaftpflicht), which German clients also expect to see. Your own plant, scaffolding and site containers need machinery or equipment cover. Simply fixing a defect is not an insured loss; only damage the defect causes to other parts of the works is covered.
What is covered
Sudden, unforeseen damage to the works before acceptance
Storm, heavy rain and unusual weather that could not be foreseen
Vandalism and malicious damage
Theft of installed components
Damage resulting from design, calculation and workmanship errors
Negligence of anyone working on site
Clean-up, demolition and debris removal as agreed
Existing structures, where included
Fire, lightning and explosion, where agreed
What is not covered
Rectifying defects where nothing else is damaged
Normal seasonal weather
Theft of loose materials not yet installed, unless agreed
Plant, scaffolding, containers and tools
Third party liability and damage to neighbours
Contract penalties, delay and acceleration costs
Damage after acceptance
Who needs it
Contractors and trades working on shell, roof, fit-out or civil engineering
General contractors and developers responsible for the whole project
Commercial clients who want all trades under one policy
Foreign contractors taking on German projects whose clients ask for proof of cover
Firms refurbishing or converting existing buildings
Who does not need it
Subcontractors on sites with a client policy covering all trades, if the deductible is manageable
Design consultants without their own construction work; they need professional indemnity
Wheel of misfortune
Spin the wheel of bad luck
Six things that really happen. The wheel picks yours and shows who pays.
Cost:
Budget policy Strong policy
See all six cases
Storm flattens a freshly built wall, roughly €5,000 to €30,000. Budget policy: pays, Strong policy: pays. An unseasonal storm before Abnahme is a textbook claim. Without cover the contractor would rebuild at his own cost.
Copper cable stripped from the shell, often four to five figures. Budget policy: pays in part, Strong policy: pays. Cable already installed is part of the works and covered. Loose drums on site are only covered where materials not yet installed are included.
Vandals smash the new windows, four to five figures. Budget policy: pays, Strong policy: pays. Malicious damage by unknown persons is covered, and nobody has to be identified. German insurers do expect a police report.
Rain pours through the opened roof, five figures per flat. Budget policy: does not pay, Strong policy: pays. The existing flats below are not part of the insured works. Only a policy that explicitly includes existing structures pays for them.
Tiles laid crooked, all must come out, four to five figures. Budget policy: does not pay, Strong policy: does not pay. Nothing was destroyed, the work is simply defective. Putting it right is a warranty matter under German law, not an insured loss.
Penalty for a three-week late handover, whatever the contract says. Budget policy: does not pay, Strong policy: does not pay. Delay penalties and acceleration costs are excluded in every German policy. They are contractual risks, not physical damage.
What it costs
The premium is a rate per mille of the contract value, or of annual construction turnover for annual policies, plus 19 percent German insurance tax. For single projects it is usually paid once for the whole construction period.
What drives the premium
Type of construction: building, civil or structural engineering
New build or work on existing buildings
Contract value and duration
Deductible
Extensions such as existing structures, theft, fire, groundwater
Flood exposure of the site
Claims history for annual policies
Premiums are calculated per project or on turnover and there are no reliable public benchmarks, so we do not quote ranges. The actual premium is fixed in the offer.
The policy levels on the market
01
Single project
One project from start of works to acceptance, sum based on contract value.
02
Annual contractor policy
All projects in a year up to a maximum sum per project, premium based on turnover.
03
Extended cover
Adds existing structures, theft of delivered materials, fire and groundwater. Useful for refurbishment, groundworks and exposed sites.
How to recognise a good policy
Criterion
Minimum standard
Strong policy
Why it matters
Scope
own work only
all trades under ABN with waiver of recourse between them
One policy for everyone ends the argument about who caused the damage.
Existing structures
excluded
included with a separate sum
In conversions the damage to the existing building is often larger than to the new work.
Theft
installed parts only
delivered but uninstalled materials up to a limit
Windows, cables and heating equipment tend to disappear before they are fitted.
Fire
not included
included, with no gap to builders' fire cover
Otherwise the shell needs separate fire insurance.
Water
only exceptional flood events
clear cover for groundwater and open excavations
Water is the most common cause of loss in groundworks.
Deductible
high and flat
graded by trade, lower for vandalism
Many site losses are mid-sized and vanish entirely into a high deductible.
Annual policy
each site declared individually
automatic cover up to a maximum per project
A forgotten declaration is the most common gap for contractors.
Insurers on the German market
In Germany contractors all risks is written mainly by property insurers with engineering departments. Some focus strongly on the construction industry.
Insurer
Background
VHV
broker-focused insurer with a strong construction industry focus
One policy for the whole project and all trades, taken out by the client.
Contractor policy (ABU)
Covers only the contractor's own work, per project or annually.
Builders' fire insurance
Fire, lightning and explosion during construction. For residential buildings often included free in the later buildings policy.
Erection all risks
For lifts, ventilation, solar and other technical plant during installation.
Business liability
Covers damage to third parties, which contractors all risks does not.
Myth or truth
True or false?
Five things people say about this insurance. Guess first, then see the answer.
German contractors all risks cover includes third party liability, as it often does abroad.
This is false.
No. Many international CAR policies have a third party liability section, but the German Bauleistungsversicherung covers the works only. Liability to neighbours and passers-by needs Betriebshaftpflicht.
Fire damage to the works is always part of the German policy.
This is false.
Not by default. Fire, lightning and explosion must be agreed. Many clients insure fire during construction through their building insurance, which often includes it free for the build period.
Damage caused by an engineer's calculation error can be covered.
This is true.
True. Physical damage resulting from design and calculation errors is covered. The corrected design itself is not; that is the engineer's liability.
Scaffolding and site containers are insured along with the works.
This is false.
No. The policy covers the building under construction. Scaffolding, containers and plant need their own machinery or equipment cover.
A freak summer cloudburst can be covered even though summer rain is normal.
This is true.
True. What counts is whether the intensity was unusual, not the season. Data from Germany's national weather service (DWD) is the usual evidence in a claim.
Common mistakes
Treating practical completion as the end of your risk instead of formal Abnahme
Relying on § 7 VOB/B for theft or ordinary storms
Working on existing buildings without including them
Accepting the client's premium deduction without knowing the deductible
Bringing a home country policy that does not cover German sites or German law
Frequently asked questions
Questions and answers
Frequently asked
Is contractors all risks insurance compulsory in Germany?
No.
Many clients, public bodies and general contractors require it in the building contract,
so without it you may not get the job.
What is Abnahme and why does it matter for insurance?
Abnahme is the formal acceptance of the work by the client.
It transfers the risk of damage from contractor to client and starts the warranty period.
Your contractors all risks cover ends with it.
Is theft from a construction site covered?
Installed components, yes.
Materials delivered but not yet installed only if the policy includes them.
Tools and machines are never part of the works.
How much does contractors all risks insurance cost in Germany?
It is a rate per mille of the contract value or annual turnover, plus 19 percent insurance tax.
Type of work, existing structures, deductible and extensions drive the rate.
Does it pay for construction defects?
No.
Putting a defect right is a warranty matter.
The policy pays for damage the defect causes to other parts of the works,
for example a collapsing slab that takes walls with it.
Another trade damaged my work. Who pays?
If there is a client policy for all trades, it pays and usually waives recourse.
Otherwise you must claim against the other firm's liability insurer,
which often fails for lack of proof.
Can the client deduct the premium from my invoice?
Only if the building contract says so.
It is common practice in Germany, and in return your work is covered under the client's policy.
Ask for the wording and the deductible.
Can I use my UK or other foreign policy for a German project?
Only if it expressly covers sites in Germany and meets the client's contract requirements.
Many clients want a policy on German terms, and German insurance tax applies to German risks.
Do I need a new policy for every site?
Not with an annual contractor policy.
It covers all projects up to a maximum sum per project and is settled on turnover.
Larger projects are declared separately.
NAMMERT insurance broker
Request quotes for Contractors all risks
We obtain quotes and come back with a comparison, free of charge.
You can write in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.