Property owner liability in Germany: when your building or land injures someone
If you let a house in Germany or own land you do not live on, you are liable for the hazards it creates: a loose roof tile, an icy pavement, a rotten tree. Personal liability insurance usually covers only the home you live in. Everything else needs Haus- und Grundbesitzerhaftpflicht, property owner liability.
Do I need property owner liability if I live in my own house?
Usually not. If you live in a detached house you own, German personal liability policies normally include your liability as owner, often also a granny flat you let out. You need a separate policy for a rented house, an apartment building, a house you do not live in, and undeveloped land. Your personal liability terms show what is included.
The duty to keep your property safe
German courts derive a general duty of care from section 823 BGB: whoever opens a property to others must keep it safe. For owners that means clearing snow and gritting paths in winter, safe stairs and railings, working lighting, and checking trees regularly. The duty applies to tenants, visitors, delivery staff and passers by alike.
Section 836 BGB is stricter for buildings. If a building collapses or parts come loose, such as roof tiles or bits of facade, the law presumes the owner was at fault. You then have to prove that the building was properly maintained and inspected. If you cannot, you pay.
Where personal liability stops
Most German personal liability policies include the house or flat you live in, and many also a granny flat or a single owned apartment that you let. A whole rented house, an apartment building, a holiday home let to guests and an undeveloped plot usually fall outside. Insurers draw these lines differently, so check your own policy wording.
In a German condominium (Wohnungseigentum) the owners association is responsible for the roof, stairwell and grounds. The property manager takes out a separate property owner liability policy for these common parts. As an individual owner you then only need cover for your own unit, which personal liability often provides.
Handing winter clearing to tenants
Many landlords transfer snow clearing to tenants through the lease or house rules, or hire a caretaker service. That is allowed, but it does not end your responsibility. You must still check that the work is actually done. If a pedestrian falls, the court will ask whether you did.
This is where the policy earns its keep a second time: it also defends unjustified claims and pays for lawyers and court costs. With injury claims that can run for years, that defence matters as much as the payment itself.
What is covered
Bodily injury, property damage and resulting financial loss caused by the insured building or land
Defence against unjustified claims, including in court
Breach of the duty to clear snow and grit, even when handed to others
Falling roof tiles, facade parts, snow and ice from the roof
Falling trees and branches
Claims by tenants for injuries in the building
Smaller building and renovation work up to a sum stated in the policy
Sewage and backflow damage to neighbours, depending on the policy
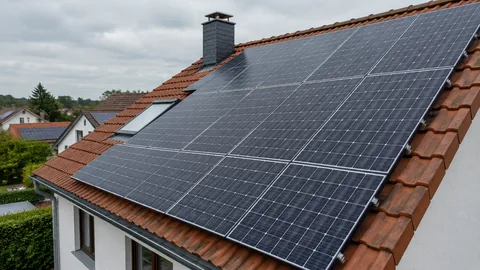
Liability as operator of a rooftop solar system, depending on the policy
What is not covered
Damage to your own building, which buildings insurance covers
Water pollution from a heating oil tank, which needs separate water damage liability
Larger construction projects above the agreed sum, which need builder liability
Commercial units that were not declared
Rent loss and disputes with tenants over rent or service charges
Deliberately caused damage
Who needs it
Landlords of houses and apartment buildings in Germany
Owners of a house they do not live in, including while it stands empty
Owners of undeveloped plots, gardens and leisure land
Owners associations for common property
Heirs of a house until it is sold or let
Who does not need it
Owner occupiers whose personal liability policy includes the house
Owners of a single rented apartment if personal liability covers it
Wheel of misfortune
Spin the wheel of bad luck
Six things that really happen. The wheel picks yours and shows who pays.
Cost:
Budget policy Strong policy
See all six cases
Roof tile hits a parked car, usually four figures. Budget policy: pays, Strong policy: pays. Under section 836 BGB you must prove the roof was properly maintained. The insurer pays justified claims and fights unjustified ones.
Pedestrian slips on icy pavement, five figures, more with lasting harm. Budget policy: pays, Strong policy: pays. The most common claim for owners. Even when winter clearing was handed over, the court looks at your duty to check.
Tree falls on the neighbour's carport, four to five figures. Budget policy: pays, Strong policy: pays. If you did not inspect the tree regularly, you are liable. With a healthy tree in a hurricane, the insurer rejects the claim for you.
Backflow floods the neighbour's cellar, four to five figures. Budget policy: pays in part, Strong policy: pays. Sewage damage is often excluded or tightly capped in basic cover. Good policies include it.
Heating oil tank leaks into soil, five to six figures. Budget policy: does not pay, Strong policy: pays in part. The tank needs its own water damage liability. Some strong policies only cover small amounts in canisters.
Storm tears open your own facade, four to five figures, by house. Budget policy: does not pay, Strong policy: does not pay. Liability only pays for harm to others. Your own facade is a buildings insurance matter.
What it costs
Property owner liability is one of the cheaper policies in Germany, but prices vary widely between insurers. In the Finanztest comparison, the same cover for an apartment building cost several times more with the most expensive insurer than with the cheapest.
Example
Typical range
Apartment building, low priced good policies
from about EUR 43 a year
Apartment building, expensive policies
up to eight times that
What drives the premium
Gross annual rent or number of units
Type of property: house, apartment building, land
Commercial use of individual units
Size of undeveloped plots
Sum insured and excess
Extras such as sewage, solar and renovation limits
Figures from the Finanztest comparison of property owner liability, issue 5/2024, covering 72 policies from 32 insurers. Your premium is fixed only in the quote.
The policy levels on the market
01
Basic
Sum insured below EUR 10 million, sewage and solar limited or excluded, low renovation limit. Only just enough for a small house without special features.
02
Standard
At least EUR 10 million combined, sewage damage, solar and a higher renovation limit included. Right for most landlords.
03
Premium
Higher limits, extended rental and financial loss cover, small heating oil quantities in canisters included, commercial units can be declared. For larger portfolios and mixed use buildings.
How to recognise a good policy
Criterion
Minimum standard
Strong policy
Why it matters
Sum insured
below EUR 10 million
at least EUR 10 million combined
A serious fall with lasting injuries can cost millions.
Transferred winter duty
own clearing duty only
also when handed to tenants or a service
Your duty to check remains and is the most common dispute.
Building work
low construction sum
high construction sum, demolition and digging included
Otherwise a renovation quickly falls outside cover.
Sewage and backflow
excluded or tightly capped
included
Blocked drains often damage neighbours.
Solar system
not mentioned
operator liability and grid feed in included
A rooftop system is a liability risk of its own.
Vacancy
short periods only
no time limit
Houses often stand empty between tenants or after an inheritance.
Undeveloped land
insured separately
included up to a plot size at no extra cost
A garden or woodland plot is easily forgotten.
Default cover
not included
included
If someone without money or insurance damages your building, you would otherwise bear the cost.
Insurers on the German market
Almost every German property insurer sells property owner liability, often as an add on to buildings insurance. We include direct insurers that do not work with brokers so you know the market.
Insurer
Background
Haftpflichtkasse
mutual specialising in liability, sold through brokers
VHV
Hanover-based broker insurer with a large liability book
Die Bayerische
brokers and direct sales, dedicated property owner policy
InterRisk
part of the Vienna Insurance Group, mainly brokers
Allianz
agents and brokers
AXA
agents and brokers
R+V
insurer of the cooperative banks
Gothaer
agents and brokers
HUK-COBURG
own sales network only, does not work with brokers
For houses and apartment buildings, usually priced by gross annual rent.
Liability for undeveloped land
For building plots, gardens, meadows and woodland without buildings, priced by area.
Owners association liability
Taken out by the property manager for common parts, often together with buildings insurance.
Included in personal liability
For the home you live in, a granny flat or a single rented apartment, depending on the policy at no extra cost.
Myth or truth
True or false?
Five things people say about this insurance. Guess first, then see the answer.
If you live in your own house, you usually do not need separate property owner liability.
This is true.
True: German personal liability normally includes the home you live in. Landlords, owners of empty houses and land owners need their own policy.
Once the lease hands snow clearing to tenants, the owner is never liable.
This is false.
False: you must still check that clearing and gritting happen. If you do not, you are liable alongside the tenant.
Nothing can happen on an empty plot.
This is false.
False: trees, holes, loose fences and children at play make even a meadow a liability risk. Cover costs little.
If my roof tile hits someone else's car, buildings insurance pays.
This is false.
No: buildings insurance covers damage to your own house. The other car is paid by property owner liability, or by personal liability for an owner occupied home.
For rented houses the premium is often based on annual rent.
This is true.
True: many insurers use gross annual rent as it reflects the size of the building well. Report it if the rent rises significantly.
Common mistakes
Assuming your personal liability covers the rented house
Leaving an inherited or empty house uninsured
Forgetting the undeveloped plot
Thinking that handing over winter clearing ends your liability
Not insuring the heating oil tank against water pollution
Not reporting a rent increase or a new commercial unit
Frequently asked questions
Questions and answers
Frequently asked
Is property owner liability compulsory in Germany?
No, the law does not require it.
But as an owner you are liable without any upper limit for damage caused by your building or land,
so every landlord should have it.
How much does it cost?
In 2024 Finanztest found good policies for an apartment building from about EUR 43 a year.
Expensive insurers charged several times that for similar cover.
The premium usually depends on gross annual rent and the type of property.
Does my personal liability cover the granny flat I let?
In many policies yes, as long as you live in the house yourself.
Some insurers limit this to one unit or charge extra.
The policy wording tells you.
Who is liable if the tenant does not clear the snow?
First the tenant, if the duty was validly transferred.
You are liable alongside if you failed to check that the work was done.
Property owner liability covers this remaining duty.
Do I need it for a plot without a building?
Yes, unless your personal liability includes it.
Trees can fall and visitors can trip on land without a house as well.
Some policies include plots up to a certain size at no extra cost.
Does it pay for damage to my own house?
No.
Liability insurance only pays when others are harmed.
Fire, storm and burst pipe damage to your own building is a matter for buildings insurance.
Is my oil tank covered?
Usually not.
If heating oil leaks into soil or groundwater,
you need separate water damage liability for the tank.
Some policies only include small amounts in canisters.
Why use a broker?
Policies differ in renovation limits, sewage, vacancy and transferred winter duty,
while prices are often close.
We also check what your personal liability already covers.
The insurer pays our fee.
NAMMERT insurance broker
Request quotes for Property owner liability
We obtain quotes and come back with a comparison, free of charge.
You can write in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.