01
Basic
Model Gliedertaxe, moderate progression, standard 15-month deadlines, reduction from 25 percent pre-existing contribution. Covers severe accidents, leaves gaps for wear-related injuries.
Personal
Personal liability Contents insurance Buildings insurance Natural hazard cover Solar panel insurance Self-build insurance Car insurance Bicycle and e-bike Travel insurance Drone insurance Dog and horse liability Pet health insurance Legal expenses insurance Accident insurance Occupational disability Term life insurance Funeral insurance Private pension Private health insurance Supplementary health Dental insurance Long-term care Property owner liability Oil tank liability Hunting liability Horse liability insurance Glass insurance Gadget insurance Motorcycle insurance Motorhome insurance Travel medical Horse surgery insurance Basic abilities Child disabilityBusiness
Business liability Professional indemnity D&O insurance Business legal expenses Business contents Commercial buildings Business interruption Electronic equipment Machinery breakdown Contractors all risks Cargo insurance Fleet insurance Cyber insurance Trade credit insurance Company pension (bAV) Company health insurance Group accident insurance By type of businessGuides
Which insurance do I need? Who pays for the damage? Insurance you may not need Cancellation deadlines Insurance questions Compare the wordings of all tariffsInsurers
German insurers A to Z Austrian insurers Spanish insurers Complaints rankingContact
+49 3375 29 12 77 Contact Customer loginLanguage
Deutsch Österreich Español Boats and yachtsHome / Insurance broker / Personal
If you work in Germany, you are covered by statutory accident insurance at work and on your commute, but that scheme does not cover you at home, on holiday or while doing sport. German private accident insurance pays a lump sum for permanent physical impairment after an accident. It is common here and often misunderstood by newcomers.
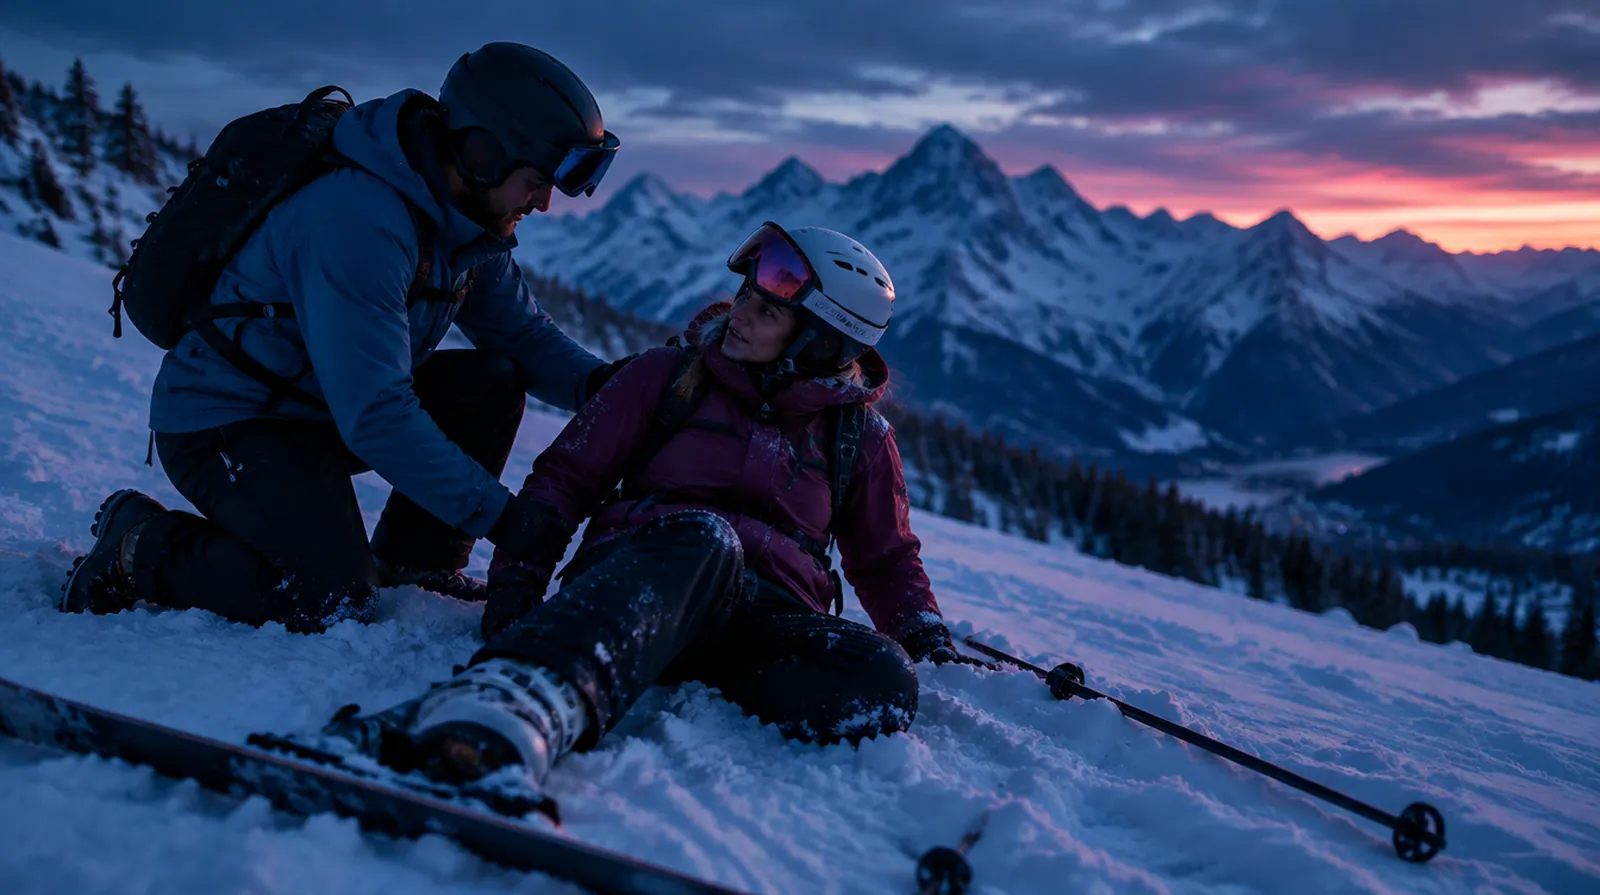
The question almost everyone asks first
Health insurance pays for treatment, not for the lasting consequences of an injury. After a leisure accident, nobody in the German system pays you a lump sum for a stiff knee, a rebuilt bathroom or lost earnings. Private accident insurance does exactly that. It is most useful for children, the self-employed and people who cannot get income protection. If you can get occupational disability insurance, buy that first, because illness causes far more lost careers than accidents.
Do the maths
German policies fix a degree of disability for the loss of each body part. With progression, payouts grow faster in serious cases.
Values from the German model conditions (GDV), progression as a common model scale.
As an employee in Germany you are automatically insured by your employer's Berufsgenossenschaft, the statutory accident insurer for your industry. It pays for accidents at work and on the direct route between home and work. Your employer pays the contribution, which is why you never see it on your payslip.
Outside that, you are on your own. A cycling fall on a Sunday, a skiing accident in Austria or a slip on the stairs at home are not covered. Even for work accidents, a statutory injury pension is only paid if your earning capacity is reduced by at least 20 percent beyond the 26th week after the accident. Freelancers are not covered at all unless they join their Berufsgenossenschaft voluntarily.
German policies do not work like UK or US accidental death and dismemberment cover with a fixed sum per injury. They use a table called the Gliedertaxe, which assigns a percentage to each body part. Losing the full use of a hand might be 55 or 70 percent, depending on the insurer. That percentage is multiplied by your base sum (Grundsumme).
Many contracts add progression: above a certain degree of impairment, the payout rises faster than the percentage. A policy with 350 percent progression pays three and a half times the base sum for total impairment. Sales brochures like to quote that maximum. For comparison, the base sum and the Gliedertaxe matter much more.
If a pre-existing condition or wear and tear contributed to the injury, the insurer reduces the payout. Standard terms do so from a 25 percent contribution, better policies only from 50 percent or more. This clause decides many claims involving knees, shoulders and the spine.
The model terms published by the German Insurance Association (AUB 2014 and 2020) require the permanent impairment to arise within 15 months of the accident, to be certified in writing by a doctor and to be claimed from the insurer within that time. Miss the deadline and the claim is lost, even if the injury is obvious.
If you are treated abroad, keep every medical report and have them translated early. A German insurer will need a doctor's statement that a lasting impairment is likely. Good policies extend the deadlines considerably, which is worth more than most optional extras.
What is covered
What is not covered
Who needs it
Who does not need it
Wheel of misfortune
Six things that really happen. The wheel picks yours and shows who pays.
Cost:
Premiums in Germany depend mainly on the base sum and your occupational risk class. Office workers and children pay least, manual trades and older people more.
What drives the premium
We do not quote a premium range, because prices vary too much with the base sum and occupation. Your premium is only fixed in the quote.
01
Basic
Model Gliedertaxe, moderate progression, standard 15-month deadlines, reduction from 25 percent pre-existing contribution. Covers severe accidents, leaves gaps for wear-related injuries.
02
Comfort
Improved Gliedertaxe, longer deadlines, reduction only from 40 or 50 percent, wider definition of accident, tick bites included. A sensible choice for most adults.
03
Premium
Very generous Gliedertaxe, long deadlines, psychological consequences and own-movement injuries included, guaranteed future improvements of the terms.
| Criterion | Minimum standard | Strong policy | Why it matters |
|---|---|---|---|
| Gliedertaxe | model values of the German Insurance Association | clearly higher percentages for hand, foot and eye | With the same base sum, this table decides how much money you actually receive. |
| Deadlines for impairment | 15 months | 36 months to arise, 48 months to claim | Missed deadlines are the most common reason valid claims fail. |
| Pre-existing conditions | reduction from 25 percent | reduction only from 60 to 100 percent | Most adults have some joint wear, and that is where reductions bite. |
| Definition of accident | includes strains from extra effort on limbs | includes own movements without external impact | A torn ligament from twisting your knee is otherwise often not an accident. |
| Loss of consciousness | excluded | included, even when caused by a stroke or heart attack | Falling after fainting would otherwise not be covered at all. |
| Rescue costs | up to €5,000 | €25,000 or more | Mountain rescue by helicopter quickly costs five figures and is not fully paid by health insurance. |
| Improvement guarantee | none | future better terms apply automatically | Your old contract then benefits from later improvements without a new health check. |
Almost every German property and casualty insurer sells accident cover. The differences lie in the Gliedertaxe, deadlines and pre-existing condition clause, often between two product lines of the same company. This is a market overview, not a statement about which insurers we work with.
| Insurer | Background |
|---|---|
| Allianz | German non-life company of the Allianz group, sold through agents and brokers |
| AXA | German arm of the French AXA group, agents and brokers |
| ERGO | owned by Munich Re, agents, brokers and direct sales |
| R+V | insurer of the German cooperative banks |
| Gothaer | group headed by a mutual, agents and brokers |
| InterRisk | part of the Austrian Vienna Insurance Group, sells through brokers |
| Die Haftpflichtkasse | mutual insurer, sells through brokers |
| Ammerländer | regional mutual from Lower Saxony, sells through brokers |
| HUK-COBURG | sells through its own network only, does not work with brokers |
Compare the wordings of all tariffs 74 tariffs from 38 providers, as of 24 October 2026
From the BaFin register
123
123 insurers supervised by BaFin, the German regulator, are licensed for this class of insurance.
(Unfall, Summenversicherung)
Source: BaFin company database, 18 September 2026; EU insurers without a German office excluded.
Individual and family policy
One contract for yourself or your household, each person with their own base sum.
Children's accident insurance
High base sum at low cost. Some insurers offer a children's disability policy instead, which also pays after serious illness.
Senior accident insurance
Lower sums, but practical help after an accident such as shopping, cleaning and transport for a few months.
Accident pension
Lifelong monthly payment from a set degree of impairment, usually 50 percent, on top of the lump sum.
Premium refund policy
Accident cover with a savings element. Much more expensive with low returns. Usually better to insure the risk and invest separately.
Myth or truth
Five things people say about this insurance. Guess first, then see the answer.
My German employer's insurance covers me around the clock.
This is false.
False. The Berufsgenossenschaft only pays for accidents at work and on the direct commute. A hiking fall on Saturday is covered by your health insurance for treatment, but nobody pays a lump sum for lasting damage.
German accident insurance can pay out even if you never miss a day of work.
This is true.
True. It pays for lasting physical impairment, not for lost income. Someone who loses the full use of a finger gets money even if they keep working in the office as before.
A tick bite in a German forest can be an insurance claim.
This is true.
True, if the policy includes infections from tick bites. Tick-borne encephalitis is concentrated in southern Germany, Lyme disease occurs across the country. Strong policies include both, basic ones often neither.
You need a German passport to buy accident insurance here.
This is false.
False. Insurers want a residence in Germany and an account in the SEPA area for the premium. Nationality plays no role in the price or the cover.
Accident insurance just pays the hospital bill.
This is false.
False. Treatment costs are your health insurer's job. An accident policy pays a lump sum for lasting impairment, plus agreed extras such as rescue costs or a daily hospital allowance.
Questions and answers
Yes.
Private accident policies in Germany normally cover you worldwide.
You will need medical reports the insurer can assess,
so ask for detailed written findings and keep copies.
Deadlines run regardless of where you were treated.
Since 2021, German law extends statutory cover to activities at home that are directly part of
your work,
and to the route to your children's nursery when working from home.
Making coffee in your kitchen or going to the shops is generally not covered.
It is a fixed table in the policy that gives each body part a percentage for complete loss or loss
of function, for example an arm, a hand, an eye or hearing.
Partial loss gives a proportional share.
It is the core of every German accident policy.
Usually not, or only in part.
Insurers treat a slipped disc as caused mainly by wear unless an accident was the main cause.
Strong policies include own-movement injuries and reduce payouts only when pre-existing damage
clearly dominates.
No.
Accident insurance pays a lump sum based on physical impairment after an accident.
The German equivalent of income protection is occupational disability insurance
(Berufsunfähigkeitsversicherung), which pays a monthly pension if you cannot work in your job,
whatever the cause.
It is one of the more useful policies for children.
Statutory cover applies only at nursery, school and on the way there.
Children cannot yet get disability insurance,
and a lasting injury affects their whole working life.
That depends on the insurer.
Many policies continue if you move within the EU, some end when you give up your German residence.
Check the terms before you move and tell your insurer about the new address.
Work from what you would need at a medium impairment of 20 to 50 percent: adapting a home, a car,
aids and several years of reduced income.
The maximum with progression only matters in rare severe cases.
Yes.
After an insured event, both sides may cancel the contract.
That is one reason to choose a good policy from the start rather than switching later with a
claims history.
NAMMERT insurance broker
We obtain quotes and come back with a comparison, free of charge.
You can write in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.

Do I need occupational disability insurance if I have just moved to Germany?
How much term life cover do I need in Germany?
Do my employees in Germany need group accident insurance if the Berufsgenossenschaft already…
What does German public health insurance not cover?
Am I covered by accident insurance during breaks and in the toilet at work in Germany?
Am I covered by accident insurance if I work while on sick leave in Germany?
Am I covered by accident insurance when volunteering in Germany?
Am I covered by accident insurance when working from home in Germany?
Can accident insurance cut my payout because of pre-existing conditions?
Does accident insurance in Germany pay for cosmetic surgery after an accident?
Does accident insurance pay for a herniated disc in Germany?
Does accident insurance pay for a stroke or heart attack in Germany?
Does accident insurance pay for a torn ligament or cruciate ligament in Germany?
Does accident insurance pay if I fall due to circulation problems in Germany?
Does private accident insurance also pay for a workplace accident in Germany?
Does private accident insurance pay pain and suffering damages in Germany?
How high should the basic sum insured be in accident insurance?
Is accident insurance with premium refund worth it in Germany?
Is an accident pension worth it in private accident insurance in Germany?
Is an automatic annual increase worth it in accident insurance?
What deadlines apply after an accident for accident insurance in Germany?
What happens to accident insurance when a care level is assessed in Germany?
What is an immediate payment for serious injuries in German accident insurance?
What is the difference between statutory and private accident insurance in Germany?
What is the recovery allowance in German accident insurance?
What is the transitional benefit (Übergangsleistung) in German accident insurance?
Ten life situations, sorted honestly
Find your case, see which policy pays
Who it suits and what to check
Boat or yacht? NAMMERT has its own cover concepts for boats, arranged by the same broker.
Boat insuranceUpdated