Insurance for roofers and roofing contractors in Germany
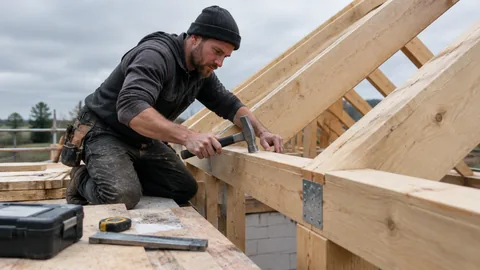
Roofers work where a mistake drops straight into the whole house: rain through the stripped roof, fire while torching bitumen, a tile on the neighbour's car. On top of that comes the highest fall risk of any trade. This page explains what your business has to insure and what you should budget for.
Who pays if a thunderstorm comes overnight and rain gets into the stripped roof?
Usually your public liability policy, if you had not secured the roof well enough: the customer's ceilings, insulation, furniture and floors. What matters is that weather damage to buildings you are working on is not excluded and that you document the sheeting with photos. Storm damage to a roof nobody is working on is paid by the owner's buildings insurance instead.
What goes wrong in this trade
01
Rain in the open roof
The old covering is off and the tarpaulin does not survive the storm. Water runs through two floors and the customer moves into a hotel.
02
Fire while torching
While welding bitumen membranes, insulation or timber catches fire. These fires are among the most expensive claims in the building trades.
03
Falling objects
Tiles, sheet metal or tools drop from the roof onto cars, conservatories or passers-by.
04
Falls
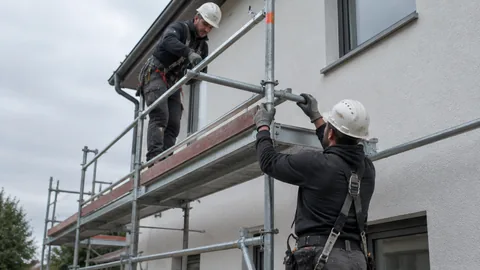
Stepping through a rooflight, falling from the scaffold: no trade has as many serious fall accidents. For owners without Berufsgenossenschaft cover this can threaten their livelihood.
05
Asbestos and contamination
Removing old corrugated sheets releases asbestos. Cleaning up neighbouring areas and claims from neighbours are often not covered.
06
Leaking junctions
A faulty flashing at a chimney or dormer drips unnoticed for years. The consequential damage to timber and insulation is large and hard to prove.
If you as the owner are not voluntarily insured with the Berufsgenossenschaft, you have no accident cover after a fall. Personal accident insurance with a high sum insured closes this gap.
Roofing is one of the occupations with the highest risk of being unable to work. Take out income protection early, or it becomes expensive or impossible.
Pays employees a lump sum after an accident in addition to the Berufsgenossenschaft, including in their free time.
What it costs: example prices
Roofers pay more for liability than most finishing trades, because fire, storm and fall claims are high. The premium depends on turnover, payroll and the share of flat roof and welding work.
Insurance
Example
Typical range
Business liability
Micro business with low turnover, €3 million cover
about €275 to €900 a year
Business liability
Business with three to five employees, €250,000 to €500,000 turnover, including flat roofs
about €1,500 to €5,000 a year
Cargo insurance
Tools in transit for three vehicles, up to €10,000 per claim
about €150 to €300 a year
Machinery breakdown
Inclined hoist and sheet metal folder worth €40,000
about €400 to €900 a year
Accident insurance
Owner, €150,000 basic sum insured with progression
about €300 to €700 a year
For comparison: Liability insurance for a small roofing business costs roughly as much per year as ten to fifteen square metres of newly laid tiled roof.
Guide prices excluding German insurance premium tax, as of September 2026.
The entry price for liability and the tools in transit figure come from published examples;
the other ranges are guide values from our quoting practice,
because hardly any reliable tariff examples for roofers are published.
Six claims that really happen to roofing businesses, all on a single Wednesday in June. Go through the day and see who pays.
Damage so far€228,200
After an overnight thunderstorm the tarpaulin has torn off the stripped roof. Water on two floors, ceilings and parquet ruined.
€32,000 · Paid by: Business liability
A loose tile slides off the scaffold boards and smashes the windscreen and bonnet of a parked car.
€3,900 · Paid by: Business liability
While torching on a flat garage roof, the timber decking catches fire. The neighbour's garage and carport are destroyed.
€58,000 · Paid by: Business liability
A gust of wind tips over the inclined hoist; motor and guide rail are bent.
€7,500 · Paid by: Machinery breakdown
The owner steps through a rooflight and falls four metres. Broken vertebra, months of rehabilitation, lasting impairment.
€120,000 · Paid by: Accident insurance
Copper sheet, cordless tools and the circular saw are stolen from the flatbed truck at the site.
€6,800 · Paid by: Cargo insurance
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €228,200
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Get written confirmation that weather damage to an opened roof and to buildings you are working on is covered.
Hot work such as torching and welding must be expressly included; follow the requirements for extinguishers and fire watch.
Choose at least €5 million combined cover; for commercial and industrial roofs clients often ask for €10 million.
Check whether asbestos work and the cleanup of asbestos contamination are covered if you strip old roofs.
If you as the owner are not voluntarily insured with BG BAU, you need personal accident insurance with a high sum insured.
Solar installation must be in the policy if you fit panels yourself or prepare the roof for them.
Why NAMMERT for your business
We negotiate the clauses
For roofers the problem is not the price but exclusions for weather and hot work. We put the wording of several insurers side by side and show you the gaps.
Storm damage is our daily work
In boat insurance we handle storm and water claims ourselves. We know how to document a loss so that it gets paid quickly.
We think of you too
Accident and income protection for owners and employees are part of running a roofing business. We handle both together.
Family owned since 1989
We can be reached when things go wrong, and we speak the language of businesses that roll up their sleeves.
Frequently asked questions
Questions and answers
Does a roofer in Germany need liability insurance?
It is not required by law, but clients and property managers almost always ask for proof.
Without it, a single fire while torching can cost you the business.
How much does liability insurance cost for roofers?
For very small businesses, tariffs start at around €275 a year.
With employees and flat roof work, premiums in our experience usually range from €1,500 to €5,000.
Is rain damage to an open roof covered?
Yes, under public liability, if weather damage to buildings you are working on is included.
Photograph the sheeting; that helps answer the question of whether you secured the roof well
enough.
Am I as the owner covered by the Berufsgenossenschaft?
Not automatically.
As a business owner you can insure yourself voluntarily with BG BAU,
the statutory accident insurer for construction.
Without it you should have personal accident insurance;
in roofing that is essential for your own sake.
Why is income protection so expensive for roofers?
Because falls, backs and joints push the risk up sharply.
The younger and healthier you are when you sign, the cheaper it is.
Some insurers offer better ratings for master roofers who mainly plan and supervise.
Is solar work on the roof covered?
Only if installing solar panels is named as an activity in the policy.
Many roofers now offer it but have never updated their policy.
NAMMERT insurance broker
Request quotes for Roofer
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.