Business interruption insurance in Germany: keeping the business alive after a loss
Business interruption insurance keeps a business alive after a loss: it pays your lost profit and ongoing costs when an insured physical loss stops or slows down your business. In Germany it is called Betriebsunterbrechungsversicherung, often shortened to BU, which is easy to confuse with the personal disability insurance of the same abbreviation. The concept is close to UK gross profit cover, the details are German.
What does business interruption insurance pay in Germany?
It pays the operating profit you lose and the fixed costs that keep running, such as salaries, rent, leasing and interest, while the business is interrupted after insured physical damage. Typical triggers are fire, water from pipes, storm or burglary on your premises. Payments run until the business is back to normal or the indemnity period ends, usually after twelve months. Losses without physical damage, such as illness or a weak market, are not covered.
Do the maths
The downtime clock
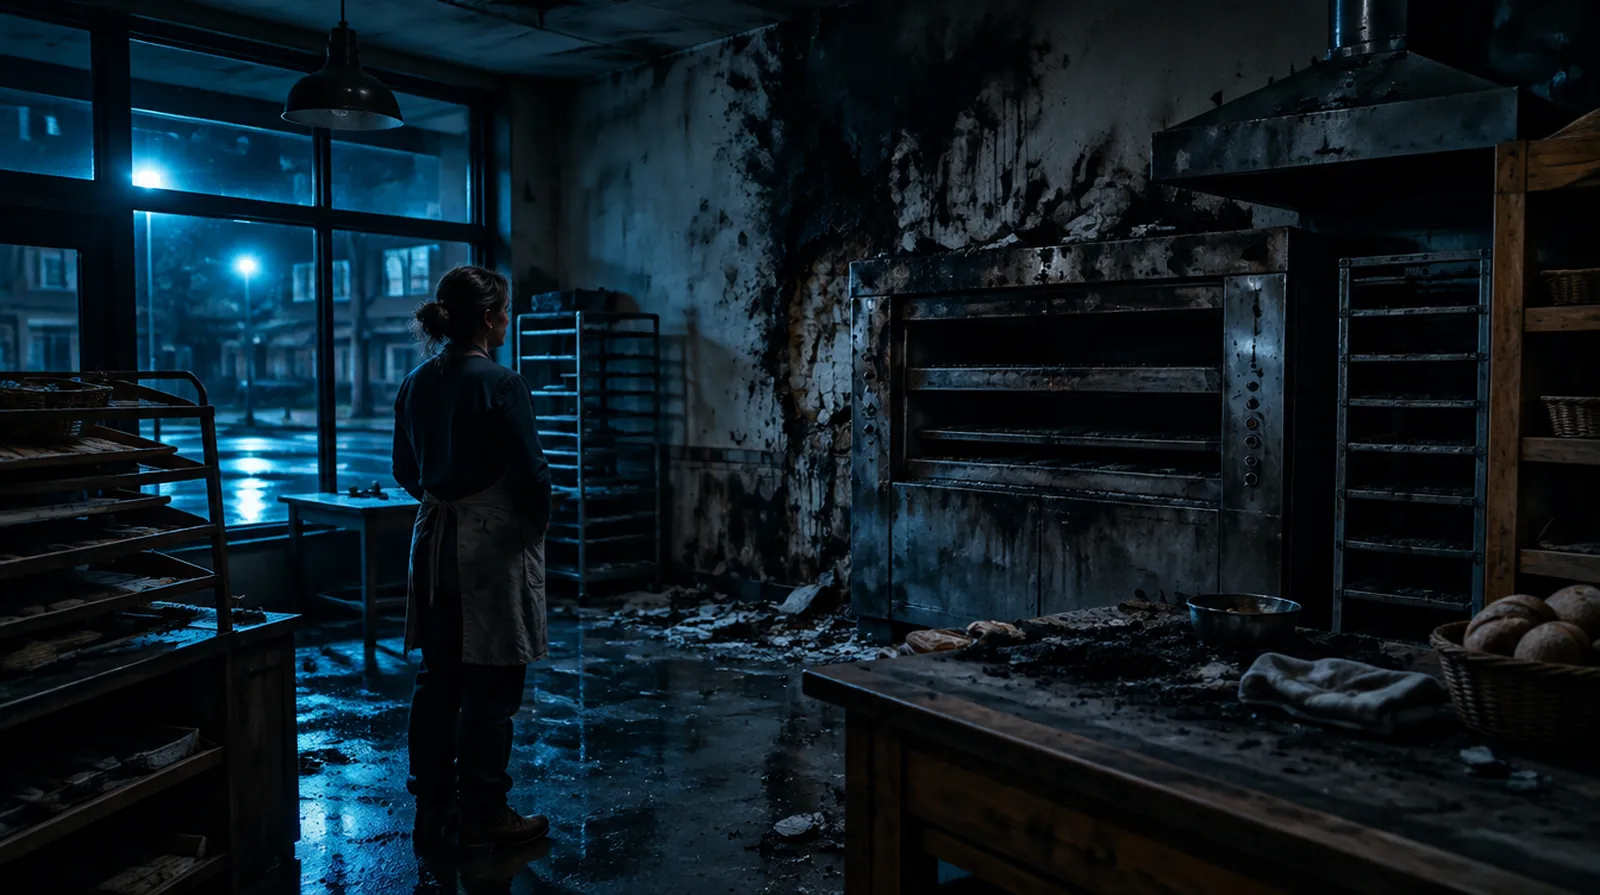
After a fire the building is replaced in weeks. Customers take longer to come back. Wages, rent and loans keep running, every day.
Months counted as 30 days.
No physical damage, no claim
German business interruption cover follows property damage. If your premises burn down, the policy pays. If your only supplier burns down, the power grid fails or the authorities close your restaurant for hygiene reasons, the standard policy does not, because nothing of yours was damaged.
Extensions exist for suppliers and customers (Rückwirkungsschäden), for failure of public utilities and, as a separate product, for closure orders under the Infection Protection Act (Betriebsschließungsversicherung). The pandemic court cases in Germany showed how much depends on the exact wording of such cover.
Setting the sum insured
The sum insured is your expected operating profit plus fixed costs for one year, or for the full indemnity period if it is longer. Your tax adviser (Steuerberater) can derive it from the profit and loss account: turnover minus variable costs such as materials and goods purchased.
Use expected figures, not last year's. A growing company insured on historic numbers is underinsured, and the proportional reduction under § 75 VVG applies here too. Good wordings waive underinsurance up to a margin or refund premium if the actual figure turns out lower.
How long is long enough?
The indemnity period starts on the day of the loss. Twelve months is often enough for an office that can move to temporary space. A manufacturer with its own building and special machinery with long delivery times may need 18 or 24 months, plus time to win back customers.
Smaller businesses often buy a simple version inside their contents policy (Klein-BU), where the business interruption sum equals the contents sum. That is cheap and convenient, but check whether that figure matches your real annual profit and costs.
What is covered
Lost operating profit during the interruption
Continuing costs such as salaries, rent, leasing and interest
Interruption after fire, lightning or explosion
Interruption after water, storm, hail or burglary, if agreed
Costs to reduce the loss, such as temporary premises
Extra costs of keeping the business running
Losses caused by damage at named suppliers or customers, if included
What is not covered
Losses without physical damage, such as recession, strikes or illness
Closures ordered by authorities for infection control
Cyber incidents without physical damage
Machinery breakdown unless machinery interruption is added
Delays caused by lack of funds for rebuilding
Contractual penalties owed to customers
Who needs it
Manufacturers relying on machinery that cannot be replaced quickly
Trade businesses with a workshop and staff
Restaurants and hotels with high fixed costs
Retailers with long commercial leases
Medical practices and laboratories
Who does not need it
Freelancers without premises, whose bigger risk is their own illness
Wheel of misfortune
Spin the wheel of bad luck
Six things that really happen. The wheel picks yours and shows who pays.
Cost:
Budget policy Strong policy
See all six cases
Fire shuts the workshop for 8 months, six figures, more for larger firms. Budget policy: pays, Strong policy: pays. Physical damage on your premises, followed by lost profit and running costs: the textbook claim.
Sole supplier's plant burns down, weeks or months of lost sales. Budget policy: does not pay, Strong policy: pays. No damage at your site means no claim under basic cover. Supplier extensions (Rückwirkungsschäden) close that gap.
Grid failure across the business park, a few thousand euros a day, depending on size. Budget policy: does not pay, Strong policy: pays in part. Strong policies add public utility failure, capped and usually after a waiting period.
Rebuild takes 20 months, not 12, eight months without cover. Budget policy: pays in part, Strong policy: pays. A twelve month indemnity period simply ends. With 24 months the remaining time is covered.
Health authority closes the kitchen, days or weeks of revenue. Budget policy: does not pay, Strong policy: does not pay. No physical damage, no business interruption claim. Closure orders need separate closure insurance.
Police cordon after fire next door, a few days of lost trade. Budget policy: does not pay, Strong policy: pays in part. Your premises are intact, so basic cover does not pay. Some wordings include denial of access for a short period.
What it costs
The premium follows the sum insured, the indemnity period and the fire risk of your business. A small business interruption element inside a contents policy costs far less than a standalone policy. There are no reliable published price ranges.
What drives the premium
Sum insured: profit plus fixed costs
Length of the indemnity period
Type of business and fire risk
Dependence on key machines, suppliers or customers
Perils included and extensions
Time deductible, for example the first 24 or 48 hours
Premiums depend too much on sum and business type for meaningful averages. Your premium is known once we have a quote.
The policy levels on the market
01
Small BU inside the contents policy
Sum equal to the contents sum, twelve months, same perils. Simple and often sufficient for small firms.
02
Standalone fire and multi-peril BU
Own sum from your accounts, indemnity period of your choice, water, storm and burglary included.
03
All risks BU with dependencies
Covers interruptions from any non-excluded damage, plus suppliers, customers and utilities.
How to recognise a good policy
Criterion
Minimum standard
Strong policy
Why it matters
Indemnity period
12 months
18 to 24 months or based on recovery time
Rebuilding and regaining customers often takes more than a year.
Underinsurance waiver
none
waiver up to an agreed margin
Growth quickly makes last year's figures too low.
Supplier and customer extension
excluded
named and unnamed suppliers and customers
Many businesses stop because someone else has a fire.
Public utilities
excluded
power, gas, water and telecoms with a sub-limit
A fire at a substation can stop a whole industrial estate.
Extra costs
only loss mitigation costs
own limit for temporary premises and outsourcing
Staying operational keeps customers from leaving.
Time deductible
several days
24 to 48 hours at most
For short interruptions, the deductible decides whether anything is paid.
Insurers on the German market
Business interruption in Germany is written by the same property insurers that cover contents and buildings, often in the same contract. Larger sums and supply chain covers are the domain of industrial and broker-focused insurers. This list is a market overview.
Insurer
Background
Allianz
BU as extension or standalone
AXA
commercial property with BU options
HDI
Talanx group, mid-sized firms and professions
R+V
mid-market customers
Zurich
commercial and industrial customers
Helvetia
property and engineering lines through brokers
Mannheimer
part of the Continentale group, trade-specific schemes