All about this insurance: Contents insurance
Do I need contents insurance as a renter in Germany?
Insurance broker / Insurance questions / Contents insurance
In short
Report the damage right away and call the police on 110 after a burglary. Limit the damage, photograph everything and throw nothing away. After a burglary, a list of stolen items with their replacement value (Stehlgutliste) goes to both the police and the insurer. In 2025 an average burglary cost around EUR 3,850. Breaching these duties can reduce your payout.
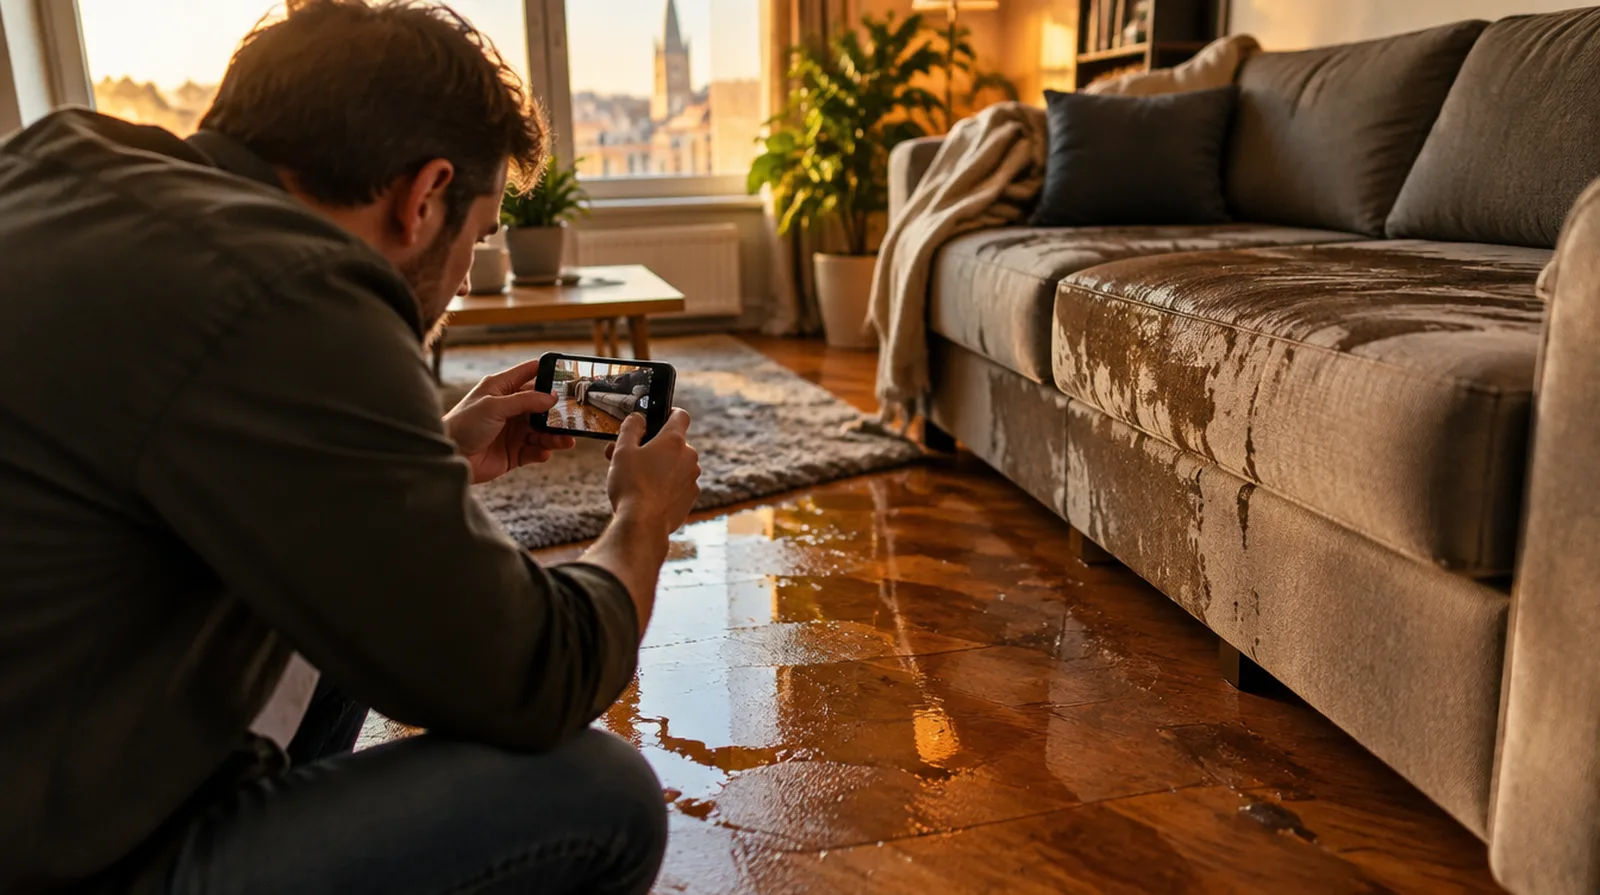
What contents claims cost on average, according to figures published by German insurers.
| Example | Typical range |
|---|---|
| Average insured burglary claim 2025 | around EUR 3,850 |
| Average lightning and surge claim 2025 | around EUR 1,760 |
| Home burglaries paid by contents insurance 2025 | around 100,000 cases, about EUR 380 million in total |
| Mediation by the insurance ombudsman | EUR 0 for you, binding on the insurer up to EUR 10,000 |
As of September 2026, from publications of the German insurance association and the ombudsman. Your own policy terms decide the individual case; we help you with the report and evidence.
Worked example
The front door was forced open. A laptop, a camera and jewellery were stolen and the door is damaged. The sum insured is sufficient, deductible EUR 150.
| Laptop, price new today | EUR 1,200 |
| Camera with lens | EUR 900 |
| Jewellery, not in a safe | EUR 1,500 |
| Emergency repair of the door the same evening | EUR 250 |
| Total | EUR 3,850 |
| Less deductible | EUR 150 |
EUR 3,700 is paid if the stolen goods list is complete and on time and the jewellery stays under the limit for valuables. For tenants, the door itself is often paid by the landlord's buildings insurance.
Safety first: after a fire or water leak get people out, and switch off power and water if that is safe. After a burglary, touch nothing and call the police on 110. The general emergency number 112 reaches fire brigade and ambulance and works in English in most places.
Then keep the damage as small as possible: mop up water, move wet furniture out, secure a broken door and block stolen bank cards. The insurer normally pays for these steps too, so keep the receipts.
| Type of damage | What to do at once |
|---|---|
| Burglary | call police on 110, change nothing, block cards, notify insurer |
| Water leak | turn off the water, tell your landlord, save furniture, take photos |
| Fire | call 112, then photos, do not wipe off soot yourself |
| Power surge after a storm | unplug devices, keep them, note the time |
| Bike theft | report to the police, have frame number and receipt ready |
Report the claim by phone, email or the insurer's online portal, and do it straight away. German policies require you to report without undue delay. Some terms ask for notice within one day after a burglary. A gap of several weeks is often treated as too late in disputes.
Photograph the damage before you tidy up. Keep damaged items until the insurer agrees they can go. Receipts, bank statements, online order histories, warranty cards and old photos of your home help prove what you owned. English receipts from abroad are fine as evidence.
The list includes every stolen or damaged item with an exact description, brand, age and the price of buying an equivalent item new. It goes to the police and separately to the insurer. Handing it to the police alone is not enough.
Send it as quickly as possible. If you remember more items later, add them in writing. If you send no list or send it very late, the insurer may reduce or refuse payment.
The insurer may ask questions, request evidence and send a loss adjuster. You must answer truthfully. False statements, even about small details, can cost you the whole claim.
It may not simply stay silent for months. If the claim is not settled one month after your report, you can ask for an advance on the amount that is certain. If it refuses, ask for the reasons in writing. Letters will usually be in German; we can go through them with you.
A very small loss just above your deductible often brings little. Several claims in a short time can lead the insurer to cancel the policy or raise the premium. So do the sums before you report a minor loss.
This does not apply to burglary: you report it to the police anyway, and the insurer should know about it.
Questions and answers
Without undue delay. After a burglary ideally the same or next day. Some policy terms state one day for burglary.
Other evidence helps: bank statements, online orders, warranty cards, photos of your home or witnesses. Without any proof it gets difficult.
Some insurers accept it, many work only in German. Short, clear sentences help. As your broker we can write or check the report with you.
For emergency steps that prevent further damage, yes. Agree larger repairs or getting rid of furniture with the insurer first.
Yes, after a claim both sides can cancel. After a single valid claim it is rare, after several in a short time it happens.
Ask for the reasons in writing and check them. Then you can turn to the insurance ombudsman free of charge before thinking about court.
NAMMERT insurance broker
We compare several insurers and come back with a proposal. Free for you; the insurer pays our fee. You can write in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.
All about this insurance: Contents insurance
Do I need contents insurance as a renter in Germany?
What does contents insurance pay after a burglary in Germany?
After a burglary, German contents insurance (Hausratversicherung) pays the cost of buying stolen items new, repairs to …
When does contents insurance not pay in Germany?
German contents insurance (Hausratversicherung) pays nothing if the risk is not covered, such as flooding without the …
Does contents insurance cover power surges from lightning in Germany?
Yes, if power surge from lightning (Überspannung durch Blitz) is in your policy. Newer tariffs almost always include i …
Does contents insurance pay out for gross negligence in Germany?
Yes, if your policy waives the gross negligence defence. Without that clause, section 81 of the German Insurance Contr …
NAMMERT Assekuradeur GmbH, insurance broker licensed under section 34d(1) of the German Trade Regulation Act, broker register no. D-C08Q-TOSD4-37. For boat and yacht insurance we act as underwriting agency, not as broker. Statutory disclosure (German) · Updated
Was this useful?