Business liability
Pays for falls, cuts and accusations against your staff, including door checks by your own people.
Insurance broker / Business types / Hospitality
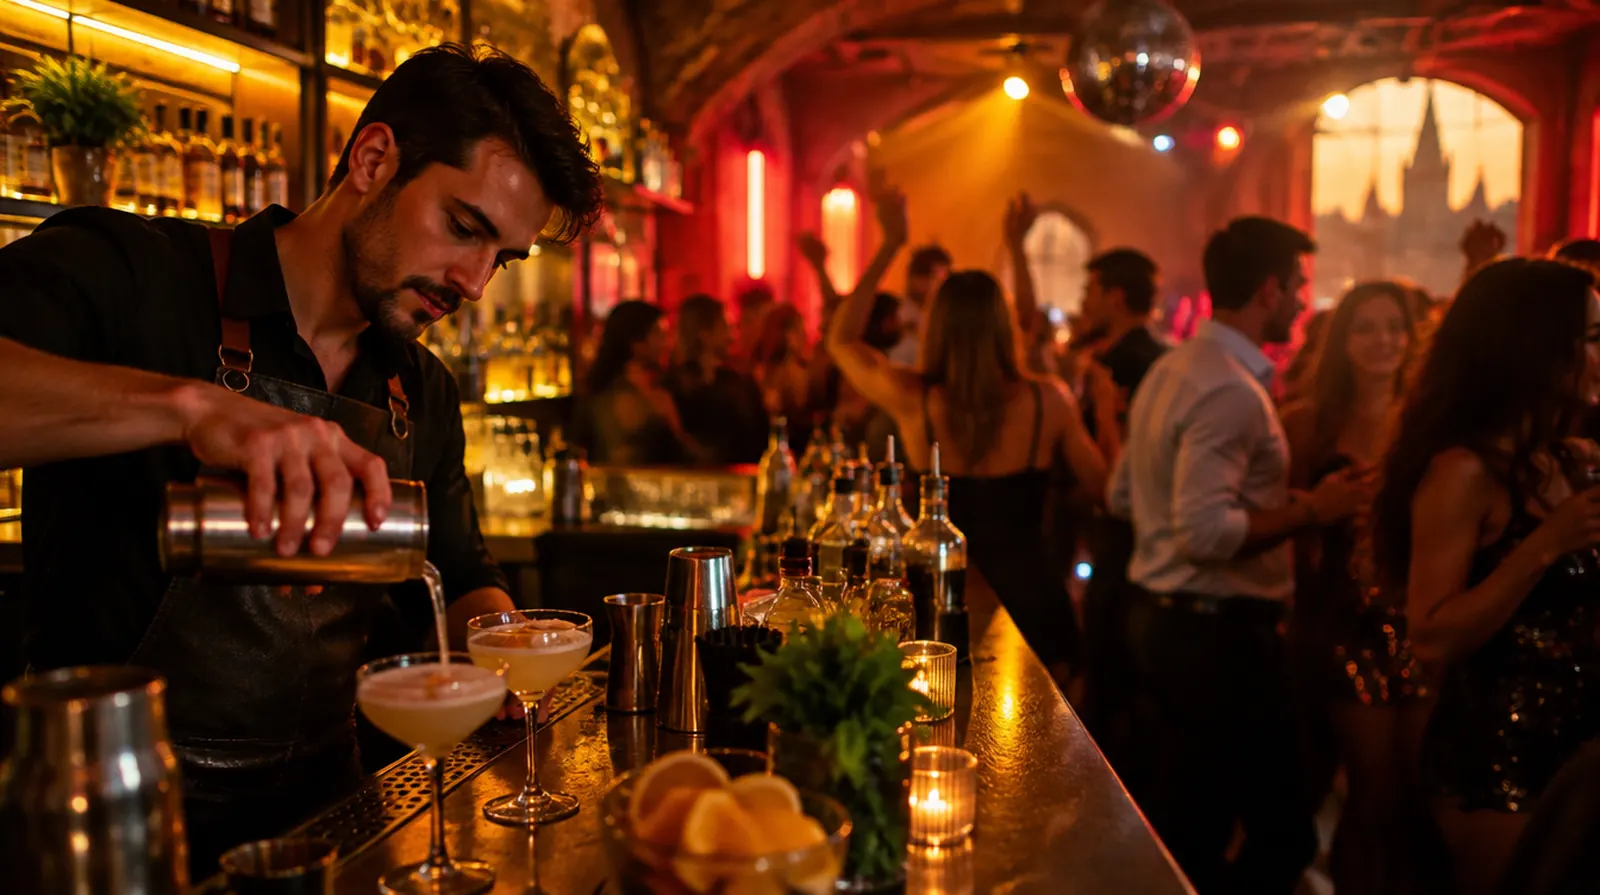
A bar earns its money while others sleep, and that is exactly when the claims happen: glass on the dance floor, an argument that escalates, a smoke machine that sets off the detector and a sound system that will not start again after a power cut. This page shows what needs to be insured and what it costs.
The question almost everyone asks first
Not for the people fighting; they are liable themselves. Your public liability steps in when you are blamed: too few staff, a blocked fire exit, a doorman who grips too hard. What matters is that door checks and security by your own staff are written into the policy. No insurer pays for damage to your fittings caused purely by rowdiness unless you have included vandalism.
A packed dance floor, broken glass underfoot, stairs in half darkness: falls and cuts are part of everyday life.
When door staff step in, an accusation of assault follows quickly. That means lawyers and often compensation.
Cigarette ends on the smoking terrace, fridges running nonstop, lighting rigs: many fires start when nobody is left on site.
Spirits, tobacco and the night's takings are easy to sell and, at night, easy to take.
Neighbours' complaints, closing time conditions, trouble with the local public order office (Ordnungsamt): this quickly becomes a question of survival.
Sound system, lighting, beer taps and refrigeration are expensive and sensitive to power surges and spilt drinks.
Compared with other trades, 1 low to 5 high.
Essential
Pays for falls, cuts and accusations against your staff, including door checks by your own people.
Replaces furnishings, bar counter, stock and till after fire, burst pipes, storm and burglary, ideally with vandalism.
Strongly advised
Pays rent and fixed costs when a fire wipes out the weekends on which you earn your money.
Covers sound system, lighting and till against power surges, liquid damage and operating errors.
For disputes with neighbours, the Ordnungsamt, the brewery and staff; licensing issues in particular often end up in court.
Depends on the business
If the till, ticket sales or guest list are hacked.
Bars and clubs pay more than a café because injuries are more frequent. What counts is turnover, number of guests, dancing, live music, own door staff and opening hours.
| Insurance | Example | Typical range |
|---|---|---|
| Business liability | Pub or bar, around €50,000 turnover, €3 million cover | about €130 to €300 a year |
| Business liability | Bar or club with dance floor, live music and own door staff | about €600 to €2,000 a year |
| Business contents | Furnishings, bar counter and stock worth €80,000 | about €350 to €900 a year |
| Electronic equipment | Sound and lighting system worth €25,000 | about €200 to €500 a year |
| Business interruption | Loss of income for up to twelve months, added to the contents policy | about €150 to €450 a year on top |
For comparison: Basic cover of public liability and contents insurance costs about as much a year as 80 cocktails.
Guide prices as of September 2026, based on published tariff examples and on our own quoting practice. Not every insurer writes nightclubs, and they are often priced individually; we obtain the exact quote for you.
01
For: corner pub or small bar without dancing
Together about €500 to €1,100 a year
Request this package02
For: cocktail bar or pub with live music and staff
Together about €1,200 to €2,800 a year
Request this package03
For: club or nightclub with own door staff and events
Together about €3,000 to €7,000 a year
Request this packageSix claims of the kind bars and clubs really see, all in one Saturday night. Click through the night and see who pays.
A thunderstorm sends a surge through the mains; the mixing desk and two power amplifiers are fried.
A guest falls on broken glass by the dance floor and cuts a hand badly.
Your own doorman restrains a guest, who breaks an arm and reports him to the police.
The neighbours take legal action over the noise, and the town threatens closing time conditions.
A cigarette end in the bin on the smoking terrace sets the store room on fire.
The bar stays shut for eight weeks: sixteen weekend nights without takings.
Which package would you have had?
Illustrative amounts before any excess. Whether and how much is paid depends on the policy terms.
Not every insurer writes clubs and nightclubs. As a broker we compare several and know who accepts dancing and your own door staff on fair terms.
In boat insurance we settle claims ourselves. That helps when, after a fight, it has to be established whether your staff are liable at all.
Bar, equipment, car and your private cover are handled together.
Advice is free for you, as the insurer pays our commission. And you reach people who know your venue.
Questions and answers
Public liability and contents insurance are the foundation. With a sound and lighting system, electronics cover is worth it, and because takings depend on a few nights a week, loss of income cover too.
For a small pub without dancing about €130 to €300 a year. Clubs with a dance floor and own door staff usually pay €600 to €2,000.
Your own employees on the door are covered by your public liability if the policy says so. An external security firm needs its own liability cover under § 34a GewO.
Contents insurance pays for destruction by guests only if vandalism is included. You can also pursue the person responsible yourself.
Yes, but not from every insurer. Nightclubs are usually assessed individually, with questions about escape routes, staff and fire safety.
At work and on the way home through the BGN, the statutory accident insurer for food and hospitality, even at four in the morning.
NAMMERT insurance broker
The recommended covers are already ticked. Change what does not fit; we obtain quotes and come back with a comparison. You can write in English.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.
Will my insurer pay if guests fall ill after eating?
Who is liable if a guest is injured at an event: the agency, the client or the venue?
Is the money in the gaming machines insured?
This page covers the following classes of the German WZ 2025 (identical to NACE at four digits):
Source: Federal Statistical Office of Germany (Destatis), WZ 2025. All business types
Boat or yacht? Here we are not the broker but the underwriting agency, with our own policies and our own claims handling.
Boat insuranceNAMMERT Assekuradeur GmbH, insurance broker licensed under section 34d(1) of the German Trade Regulation Act, broker register no. D-C08Q-TOSD4-37. For boat and yacht insurance we act as underwriting agency, not as broker. Statutory disclosure (German) · Updated