Business liability
Pays for damage to visitors, halls and neighbouring stands, including damage to rented halls and fairs abroad.
Insurance broker / Business types / Construction and trades
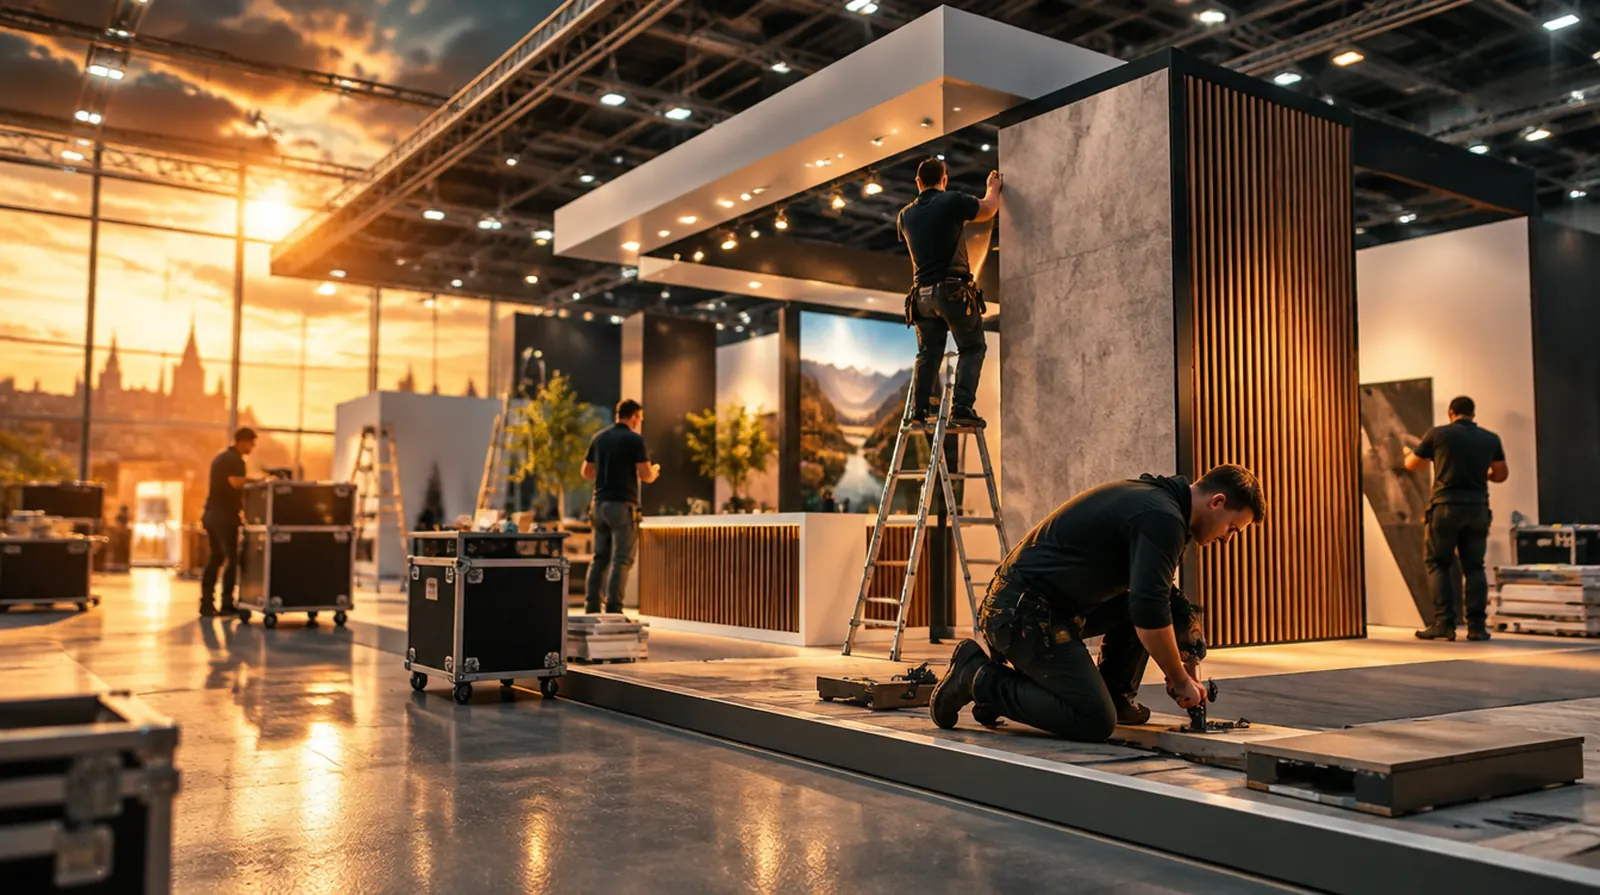
Stand building means putting up a stand in someone else's hall in three nights, running it in front of the public and taking it down again in one night. In between come transport across half of Europe, hired technology and a hall floor that must not be damaged. This page explains what your business should insure and what it costs.
The question almost everyone asks first
Your public liability policy, if the stand was built or secured defectively. It pays for treatment, compensation for pain and suffering and damage to neighbouring stands. What matters is that exhibition stand building is named as an activity in the policy and that the territorial scope also covers fairs abroad if you build there.
A poorly suspended truss, a wall that is not anchored: when thousands of visitors walk the aisles, a design fault quickly becomes expensive.
During build-up, hall floors, sprinklers or neighbouring stands get damaged; the organiser sends the bill.
Stand elements, graphics and furniture travel hundreds of kilometres and break, get wet or go missing.
During build-up and dismantling nights, tools, monitors and exhibits stand in the open. Thefts are common.
LED walls, projectors and touchscreens are expensive and often hired. Whoever damages them is liable to the hire company.
Ladders, aerial work platforms and exhaustion: accidents during build-up are typical in stand building.
Compared with other trades, 1 low to 5 high.
Essential
Pays for damage to visitors, halls and neighbouring stands, including damage to rented halls and fairs abroad.
Strongly advised
Covers stand components, graphics and tools on the way to the fair and back, including breakage and theft.
Protects your own and hired LED walls, monitors and media technology against damage and theft.
Replaces the workshop, store of stand systems and machines after fire, burglary and water.
Depends on the business
Pays fixed costs if the workshop or store is out of action before an important trade fair season.
Lorries and vans for the trade fair tours can be bundled in one fleet policy.
Business legal expenses cover for disputes with exhibitors over sign-off and payment, and with organisers over damage.
Liability for stand builders is cheap compared with other trades. The bigger items are transport and technology, because the stand is constantly on the move.
| Insurance | Example | Typical range |
|---|---|---|
| Business liability | €100,000 turnover, €1,000 excess | about €160 to €500 a year |
| Business liability | Business with three to ten employees and fairs abroad, €5 million cover | about €600 to €1,800 a year |
| Cargo insurance | Stand components up to €50,000 per shipment, fairs in Europe | about €400 to €1,200 a year |
| Electronic equipment | Media technology and LED walls worth €60,000 | about €700 to €1,800 a year |
For comparison: Liability and transit cover for a small stand builder cost about as much per year as three to four square metres of finished modular stand.
Guide prices excluding German insurance premium tax, as of September 2026. The entry price for liability comes from a published tariff example; the other ranges are guide values from our quoting practice. We obtain the exact quote for you.
01
For: stand builder working alone or with temporary help, modular stands
Together about €550 to €1,500 a year
Request this package02
For: own workshop, three to ten employees, fairs in Europe
Together about €2,000 to €5,500 a year
Request this package03
For: stand building and shopfitting with store, lorries and media technology
Together about €5,000 to €12,000 a year excluding the fleet
Request this packageSix claims that really happen to stand builders, all on the last build-up day before a big trade fair. Go through the day and see who pays.
While unloading, a crate of printed glass walls falls off the pallet truck. All elements are broken.
The aerial work platform damages a sprinkler head in the hall. Water runs onto two neighbouring stands.
A hired LED wall falls out of its mounting while being hung. The hire company charges for twelve modules.
While screwing down, the raised access floor of the hall is damaged. The organiser demands compensation.
On the first day of the fair, a stand wall that was not anchored tips onto a visitor. Bruises and a shoulder injury.
During the dismantling night, cordless tools and two monitors disappear from the stand.
Which package would you have had?
Illustrative amounts before any excess. Whether and how much is paid depends on the policy terms.
In stand building, territorial scope, transit and third-party technology decide the outcome. We compare exactly these points across several insurers.
In boat insurance we handle claims ourselves, including on journeys and abroad. We know how to document a loss properly far away from the business.
Workshop, transport, technology and your private cover sit with one contact person.
Our advice is free for you; the insurer pays our remuneration. And we can be reached even when the fair opens at the weekend.
Questions and answers
Not by law, but trade fair organisers almost always ask for it, often with minimum cover of €5 million.
Published tariffs start at around €160 a year for €100,000 turnover with an excess. With employees and fairs abroad, it is usually €600 to €1,800 in our experience.
Not under liability. For that you need transit or exhibition insurance that also covers breakage and theft.
Only if the territorial scope provides for it. Check before every fair abroad and get written confirmation.
Liability insurance often excludes hired movable property. Electronics insurance for third-party equipment closes this gap.
The exhibitor is liable for what they do on the stand. You as the stand builder are liable for faults in the construction. Both should have their own policies.
NAMMERT insurance broker
The recommended covers are already ticked. Change what does not fit; we obtain quotes and come back with a comparison. You can write in English.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.
Is my customer's kitchen insured if it burns in my workshop?
Will the insurer pay if a cable fire breaks out months after my job?
Will the insurer pay if someone steals goods from my shop?
Boat or yacht? Here we are not the broker but the underwriting agency, with our own policies and our own claims handling.
Boat insuranceNAMMERT Assekuradeur GmbH, insurance broker licensed under section 34d(1) of the German Trade Regulation Act, broker register no. D-C08Q-TOSD4-37. For boat and yacht insurance we act as underwriting agency, not as broker. Statutory disclosure (German) · Updated