All about this insurance: Personal liability
Do I really need personal liability insurance in Germany?
Insurance broker / Insurance questions / Personal liability
In short
Yes, if your policy explicitly includes damage caused while doing a favour (Gefälligkeitsschäden). Then your personal liability insurance pays even if you were only slightly careless and would not be liable by law. Many policies set a separate, lower limit for this. A good policy costs singles about EUR 40 to 120 a year.
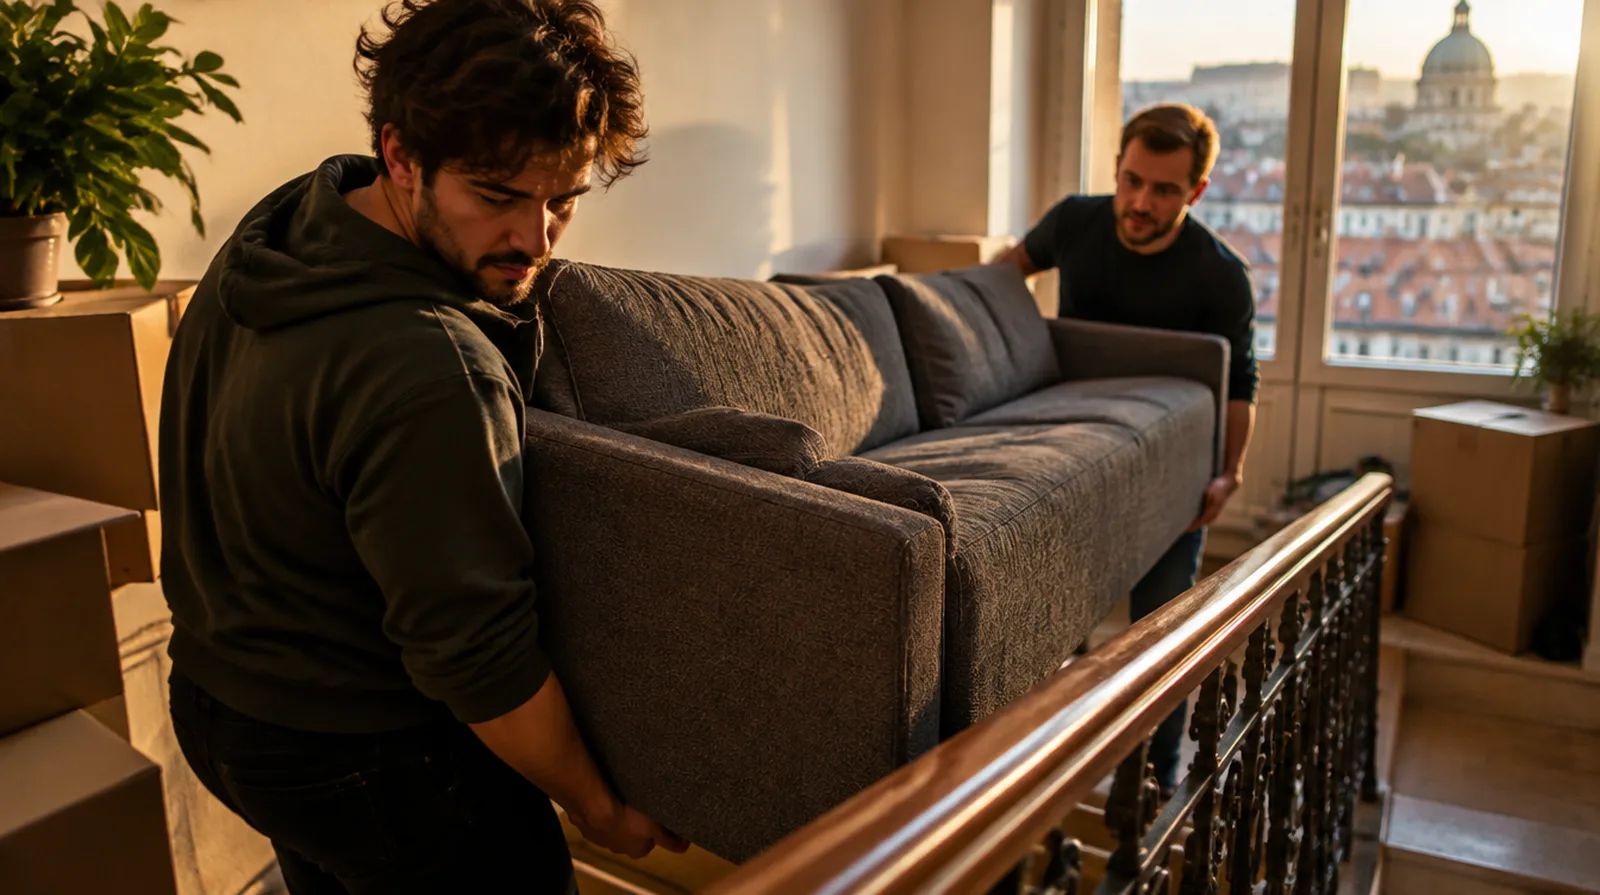
Guide values for personal liability insurance that includes favour damage.
| Example | Typical range |
|---|---|
| Single, policy with favour damage | about EUR 40 to 120 a year |
| Family, policy with favour damage | about EUR 60 to 180 a year |
| Simplest online policy with favour damage | from about EUR 3 a month |
Guide values as of September 2026 from publicly quoted premium ranges. The limits for favour damage range from a few tens of thousands of euros to the full sum insured, depending on the policy (guide value from our quoting practice).
Worked example
You help a friend move. While you put it down, the TV slips and the screen breaks. It is three years old.
| New price of the TV | EUR 900 |
| Current value after three years | about EUR 450 |
| Payment without the clause | often EUR 0, because slight carelessness among friends |
| Payment with the clause | about EUR 450 |
Your friend gets the current value, you pay nothing or only your deductible.
German courts often assume that people who help a friend for free are only liable for gross negligence or intent. The idea is that friends silently agree not to hold each other responsible for small clumsiness.
That sounds good for you, but not for your friend: if the TV slips while you carry it, they are left with the loss. And your liability insurance does not pay, because it only pays when you are legally liable.
In the UK or US, most people would simply expect their home or renters insurance to sort this out. In Germany personal liability insurance (Privathaftpflicht) is a separate policy, and this rule about favours is a German peculiarity that surprises many newcomers.
Helping each other move is common among expats without family nearby. If friends help you, it is fair to ask whether their policy includes favour damage. If you help, check your own policy first. The terms are usually in German, look for the word Gefälligkeitsschäden.
With the clause, the insurer agrees not to rely on the silent waiver of liability. It pays as if you were normally liable. The friendship stays intact and nobody has to negotiate.
Courts have also decided that such a silent waiver usually cannot be assumed if the helper has liability insurance. Do not rely on that alone, a clear rule in the contract is safer.
| Situation | Without clause | With clause |
|---|---|---|
| Moving: TV falls through carelessness | often no payment | payment up to the agreed sum |
| Watering plants: tap left running | dispute about liability likely | payment |
| Damage through gross negligence | payment if gross negligence is covered | payment |
| Damage on purpose | no payment | no payment |
Damage to borrowed or rented items is not automatically a favour case. If you borrow a moving van, the owner's motor insurance or a separate rule applies. Damage to a car you drive for a friend is generally not paid by personal liability insurance.
Paid help is no longer a favour. If you are paid to help someone move, you are working, and personal liability insurance is not made for that.
If you almost never help others and rarely get help, the clause brings little. Newer policies usually include it at no extra cost, so buying it separately only makes sense if your old policy is otherwise good.
Questions and answers
Damage you cause while helping others for free, for example when moving house, watering plants or building a wardrobe.
With the favour damage clause, yes, usually at current value. Without it the insurer can refuse, because you are often not liable for slight carelessness.
Not if the person is covered under the same policy. Personal liability insurance generally does not pay for damage among co-insured people.
Not while driving, that is a matter for motor insurance. If you damage the parked car, for example while carrying something, it can be a liability case.
Usually only the current value. This is legal compensation, not new-for-old insurance.
NAMMERT insurance broker
We compare several insurers and come back with a proposal. Free for you; the insurer pays our fee. You can write in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.
All about this insurance: Personal liability
Do I really need personal liability insurance in Germany?
Does personal liability insurance cover borrowed items in Germany?
Only if your tariff includes it explicitly. Older and basic German policies exclude damage to borrowed, rented or leas …
What does personal liability insurance cover in Germany?
German personal liability insurance (Privathaftpflichtversicherung) pays when you are at fault for injury, property da …
When does personal liability insurance not pay in Germany?
Personal liability insurance (Privathaftpflicht) does not pay for damage caused on purpose, damage to your own things, …
NAMMERT Assekuradeur GmbH, insurance broker licensed under section 34d(1) of the German Trade Regulation Act, broker register no. D-C08Q-TOSD4-37. For boat and yacht insurance we act as underwriting agency, not as broker. Statutory disclosure (German) · Updated