Insurance for bike shops and cycle repair workshops in Germany
Most of what a bike shop sells today is e-bikes at 4,000 euros and more, and the bikes it services leave the workshop to be ridden at 25 kilometres an hour. One badly fitted brake, or a battery that catches fire in the shop overnight, can hit the business hard. This page explains how to cover those risks and what it costs.
Am I liable if a customer crashes because of the brakes after a service?
Yes, if the crash goes back to your work, such as wrongly fitted brake pads or a thru axle that was never tightened. Your public liability policy then pays for treatment, lost earnings and compensation for pain and suffering. Make sure assembly and repair work are insured as activities, not just the retail side. A checklist the customer signs on collection helps if there is a dispute later.
What goes wrong in this trade
01
Mistakes in the workshop
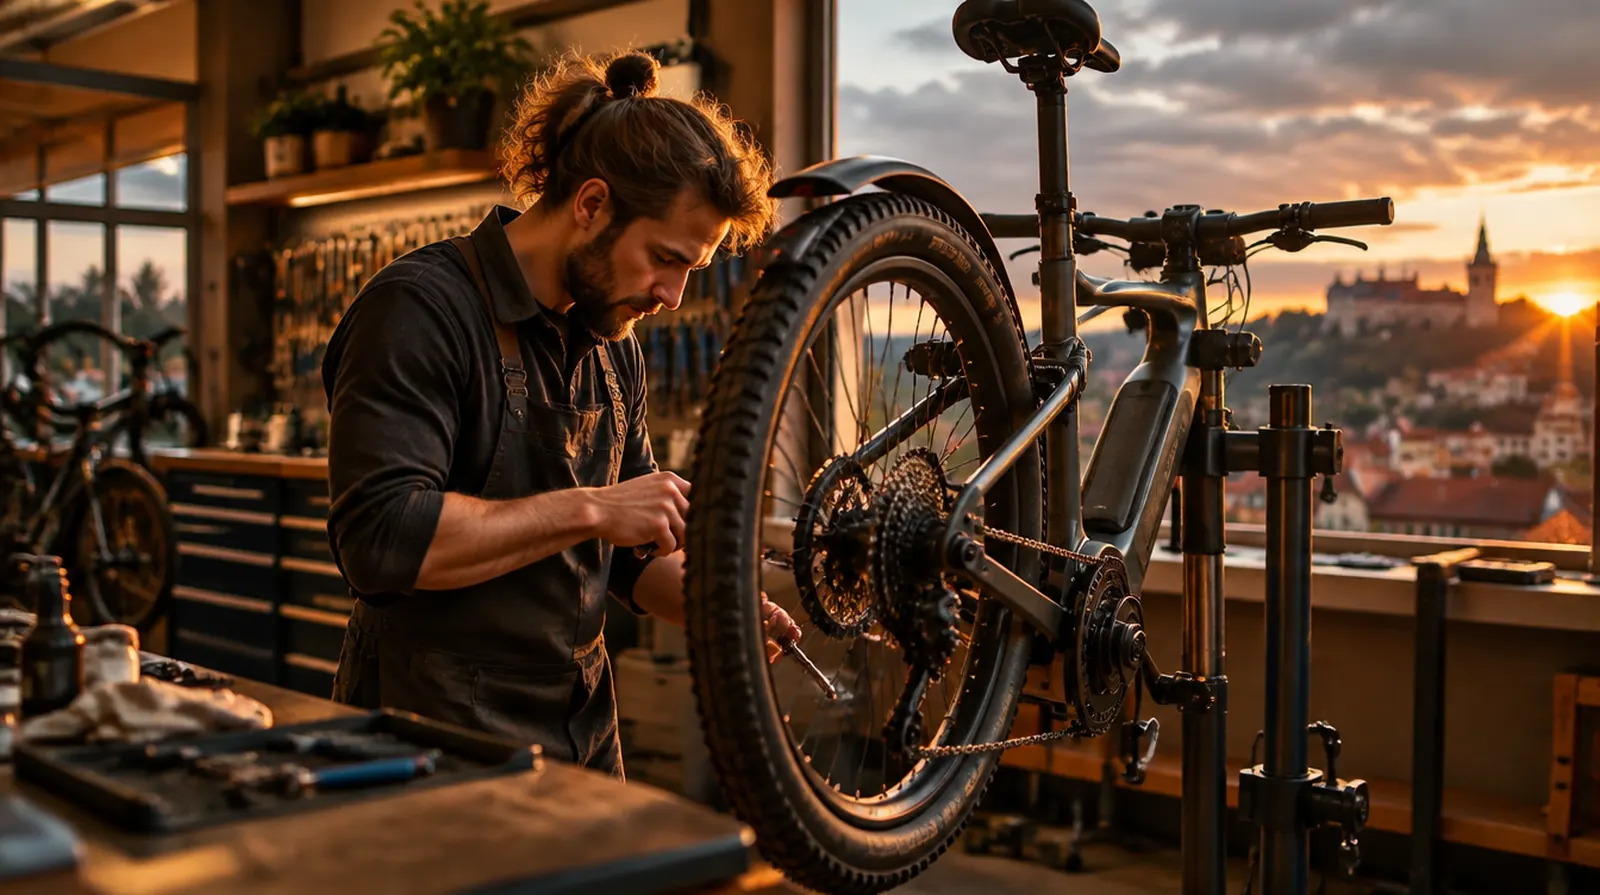
A loose stem bolt, badly adjusted brakes, a wheel that was not secured: falls from an e-bike often end in serious injuries.
02
A battery catches fire
Damaged or cheap batteries from customers' bikes can ignite while charging, and a lithium fire spreads quickly to the stockroom and shop floor.
03
Break-ins
A stockroom holding twenty e-bikes is worth more than a new car. Professional thieves arrive with a van and are gone within minutes.
04
Test rides
Someone takes a bike out for a test ride and never returns it, or falls and damages a demo bike.
05
Bikes left in your care
In high season up to forty bikes belonging to customers stand in the workshop. If they are stolen or burn, you are liable.
06
Recalls and batch defects
When a manufacturer's forks crack or its batteries turn out to be faulty, the resulting recall usually lands at the dealer's counter first.
Pays when customers are injured after assembly, repairs or a test ride, and for damage to customers' bikes if cover for damage to items being worked on is included.
Replaces bikes, batteries, tools and fittings after a break-in, fire, water damage or storm, including customers' bikes as third party property where this is added.
For disputes with manufacturers over warranty claims, with leasing companies or with your landlord.
What it costs: example prices
Liability cover is cheap for bike shops, provided the workshop is properly included. The larger item is contents insurance, because e-bikes pack a lot of value into a small space.
Insurance
Example
Typical range
Business liability
Bike shop with workshop and one to three employees
around 80 to 400 euros a year
Business contents
Bikes, batteries and fittings worth 150,000 euros, including burglary
around 500 to 1,300 euros a year
Business contents
Specialist shop holding 300,000 euros of stock in season
around 1,000 to 2,500 euros a year
Business interruption
Loss of income for up to twelve months
around 120 to 400 euros a year
Electronic equipment
Diagnostic and workshop equipment worth 10,000 euros
around 100 to 300 euros a year
For comparison: For a small bike shop, liability and contents insurance together cost roughly what ten full services in your own workshop bring in over a year.
Guide figures excluding insurance tax, as of September 2026.
Liability is based on a public price comparison for bicycle retail.
Contents insurance for e-bike stock is a guide figure from our own quoting practice,
because insurers assess theft and battery fires case by case.
Six losses that bike dealers genuinely face, all squeezed into one Tuesday in April. Tap through the day and see who pays.
Damage so far€158,300
Burglars force the roller shutter and load eight e-bikes into a van.
€32,000 · Paid by: Business contents
Two days after a service, a customer falls because the front brake was fitted wrongly. Broken collarbone and lost earnings.
€18,000 · Paid by: Business liability
While a bottom bracket is being pressed in, the carbon frame of a customer's bike cracks.
€3,500 · Paid by: Business liability
The motor diagnostic unit falls off the workbench and stops working.
€1,800 · Paid by: Electronic equipment
A customer's battery on the charging rack catches fire. The workshop, spare parts and twelve customers' bikes are burnt or covered in soot.
€75,000 · Paid by: Business contents
Shop and workshop stay closed for six weeks at the height of the season.
€28,000 · Paid by: Business interruption
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €158,300
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Have assembly, repairs and test rides written into your liability policy explicitly, not only the sale of bikes.
Insure customers' bikes as third party property under your contents policy, with a sum that fits the peak season.
Clarify the fire safety conditions for charging batteries, and store damaged batteries separately in a fireproof place.
Agree an automatic increase in the sum insured for spring, when the stockroom and workshop are at their fullest.
Only hand out test bikes against ID and a signed agreement: theft during a test ride is usually covered only if you add it.
Choose at least 5 million euros of cover for personal injury, because e-bike accidents often have serious consequences.
Why NAMMERT for your business
We know vehicles with motors and batteries
Electric drives and batteries play a growing part in boat insurance too. As a broker we compare several insurers on exactly how they treat battery fires.
We handle claims ourselves
Because we handle boat claims in house, we know which evidence an insurer asks for after a break-in or fire, and we help you put it together in full.
Shop, van and private cover in one place
Your business, vehicles, your own bike and your personal cover sit with one contact, reachable on +49 3375 29 12 77.
A family business since 1989
We advise businesses that know their customers by name, just as we do. Our advice costs you nothing.
Frequently asked questions
Questions and answers
What insurance does a bike shop need?
Public liability that includes the workshop and test rides,
and contents insurance with burglary cover for the bikes.
With plenty of e-bikes in stock, business interruption cover is worth having too.
How much does insurance cost for a bike dealer?
Liability starts at around 80 euros a year.
Add contents insurance for e-bikes and small specialist shops usually pay between 900 and 2,200
euros.
Are customers' bikes in my workshop insured?
Only if third party property is included in your contents insurance.
Damage caused while you work on a bike falls under liability,
provided cover for items being worked on is part of it.
Will insurance pay for a battery fire?
Fire is covered under contents insurance.
If you break agreed conditions on charging and storing batteries, however,
the insurer may reduce the payout.
Who is liable for an accident on a test ride?
If the rider injures someone else on a pedelec,
either their own private liability or your business liability pays, depending on the policy.
Damage to the demo bike itself is covered by your contents insurance only if you have added it.
Do S-pedelecs need their own insurance?
Yes.
S-pedelecs up to 45 kilometres an hour must be insured and carry an insurance number plate,
even when used as demo or rental bikes.
NAMMERT insurance broker
Request quotes for Bike shop
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.