Insurance for boat hire, charter and leisure hire in Germany
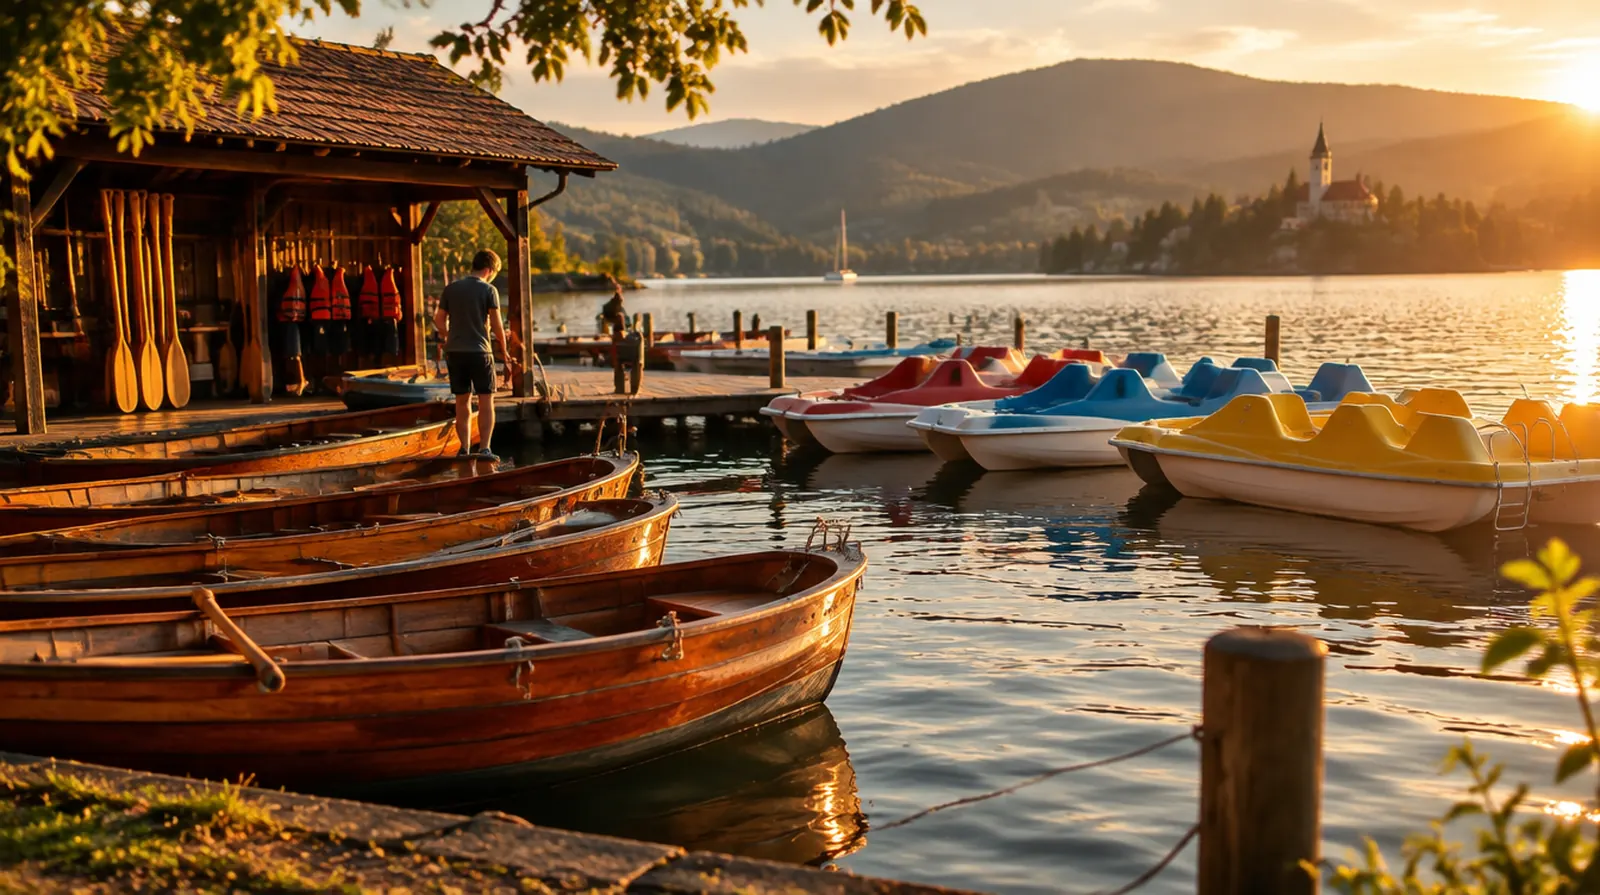
At a boat hire business, the person at the helm is someone you met fifteen minutes ago. They ram jetties, run boats aground and lose paddles, SUPs and sometimes their nerve. The boats themselves belong in a commercial boat policy, the business on land in its own liability cover. This page shows how the two fit together.
Can I insure my hire boats on an ordinary boat policy?
No. Private boat insurance does not cover commercial hire, and if you hire the boat out anyway, you put your cover at risk. Boats used commercially need a commercial tariff with a surcharge, with a separate policy for each boat. As an underwriting agency (Assekuradeur) we designed this cover ourselves, including for charter jet skis, and handle claims in house.
What goes wrong in this trade
01
Hirers with no experience
Many hirers are driving a motorboat for the first time. Mooring, locks and oncoming traffic often end against someone else's jetty or another boat.
02
Running aground
A rock just below the surface or a stretch of shore taken too shallow: propeller, shaft and hull can easily suffer damage running into four figures.
03
People in the water
Bathers, swimmers, stand up paddlers: injuring someone with a hire boat is the most expensive case, and it usually affects a third party rather than the hirer.
04
Weather at the jetty
Thunderstorms and gales tear boats off their buoys, push them against the jetty or fill open boats with rainwater.
05
Theft of hire kit
SUP boards, outboard motors, buoyancy aids and wetsuits disappear from containers and boathouses, often the night before the season opens.
06
A short season
If half the fleet is out of action after a storm in July, you cannot make up the takings in October.
Covers the business on land: falls on the jetty, damage in the car park, safety briefings and guided tours. Liability arising from using the boats sits in the boat policy for each vessel.
The biggest item is the boats themselves. As the underwriting agency we price them on our own commercial tariff, boat by boat, according to value, length, engine and waters, with a surcharge for commercial use. The examples below cover the business on land, which is insured separately.
Insurance
Example
Typical range
Business liability
Hire business with jetty, kiosk and up to three seasonal staff
about 150 to 400 euros a year
Business contents
20 SUPs and canoes, buoyancy aids and cash in a container, worth 25,000 euros
about 250 to 600 euros a year
Business interruption
Loss of income for up to six months, together with contents insurance
about 150 to 400 euros a year on top
Cyber insurance
Small business with online booking, 250,000 euros cover
about 350 to 500 euros a year
For comparison: Liability and contents cover for the business on land costs about as much a year as ten half days hiring a motorboat that needs no licence.
Guide prices excluding German insurance tax, as of September 2026,
based on published tariff examples for comparable businesses and our own quoting experience.
We quote the boats from your boat list, because value and engine size vary widely.
Six things that really happen on land, all on a single Saturday in August. Damage to and by the boats themselves we handle in house under the boat insurance; here you see what the business alongside has to carry.
Damage so far€77,300
The container was broken into overnight. Six SUP boards, two outboard motors and the cash float are gone.
€7,800 · Paid by: Business contents
A customer slips on the wet jetty and breaks her ankle.
€8,500 · Paid by: Business liability
The online booking system has been encrypted, and every reservation for the weekend is lost.
€4,000 · Paid by: Cyber insurance
On a guided canoe tour, a group capsizes at the weir. One participant is injured and blames the guide for a poor safety briefing.
€15,000 · Paid by: Business liability
A thunderstorm flattens the jetty and rips open the boathouse roof.
€24,000 · Paid by: Commercial buildings
With no jetty, the hire business stands still for ten days in the middle of the summer holidays.
€18,000 · Paid by: Business interruption
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €77,300
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Insure every hire boat commercially on its own policy. A privately insured boat used for hire is often left without cover when something happens.
Set a deposit in your hire agreement equal to the excess on the boat policy, so the hirer carries the small claims.
Record every safety briefing with a signature and the time. After an accident, that is your most important piece of evidence.
List SUPs and canoes as a separate item in your contents insurance, with cover away from the premises for use on the water if the insurer offers it.
Check lease and mooring agreements for required liability limits, and name the local council or landlord as co-insured if they ask for it.
Declare charter jet skis and fast motorboats explicitly. We also insure jet skis used commercially, which is rare on the market.
Why NAMMERT for your business
For boats, our own cover concept
For boats we have our own tariffs for charter and hire, arranged through our brokerage with Württembergische. You get your boat cover directly from us, and our own team takes up each claim and files it in full.
We handle claims ourselves
A jetty rammed on a Sunday, a propeller on a rock: we know the boatyards, the surveyors and the typical hirer claims from decades of our own claims files.
Land and water from one source
For the jetty, boathouse, hire kit and online booking, we act as your broker, compare offers from several insurers and match them to your boat policies. That way there is no gap between the shore and the water.
A family business by the water since 1989
Boats are our livelihood and we know the rhythm of a season. You have named contacts who still pick up the phone in August.
Frequently asked questions
Questions and answers
Does a boat hire business need compulsory insurance?
There is no nationwide requirement.
Some waters and harbour regulations,
permits from the water authority and lease agreements often do require liability cover for the
boats.
Without it, an injury caused by a hirer would be unaffordable anyway.
Is the hirer or the hire business liable for damage?
Towards third parties, often both are: the business as keeper and the hirer as skipper.
The hire business's boat liability cover pays first;
in cases of gross negligence it can recover money from the hirer.
Why does every boat need its own policy?
Because boats used commercially are assessed one by one: value, engine and use differ widely.
We do not offer bundled policies covering several boats for commercial use.
Are SUP boards and canoes covered by the boat insurance?
Small hire kit without an engine is often cheaper to insure as equipment under contents insurance.
Motorboats and sailing boats belong in boat insurance.
We look at your list and split it sensibly.
Can I occasionally hire out my privately insured boat?
On our private tariff you can include private hire for up to 30 days per insurance year.
If you hire out regularly and commercially, you need the commercial tariff.
Who handles the claim if a hirer damages my boat?
For boats insured with us, we handle claims ourselves.
You report the damage directly to us,
we instruct the surveyor and boatyard and file the claim in full with the insurer,
which decides on payment.
NAMMERT insurance broker
Request quotes for Boat hire
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.