Insurance for bowling alleys and skittle centres in Germany
In a bowling centre, the real value is not in the till but in the pinsetter machinery behind the lanes. If it fails, the whole operation stops, not just one lane. Add falls on the approach, the ball return, and a bar or shoe hire running alongside the lanes, and cover has to join up machinery, liability and downtime rather than treat them separately.
Two policies work together. Machinery breakdown insurance pays for repair or replacement of the pinsetter after a mechanical failure, wear related damage or operating error. Business interruption cover pays rent, wages and lost profit while the affected lane, or the whole centre, is out of action. Without both, you carry the repair cost and the lost trading days yourself.
What goes wrong in this trade
01
Pinsetter breakdown
The automatic pinsetter mechanism is the most expensive part of any lane. When it fails, that lane can be out of use for days while parts are sourced.
02
Falls on the approach
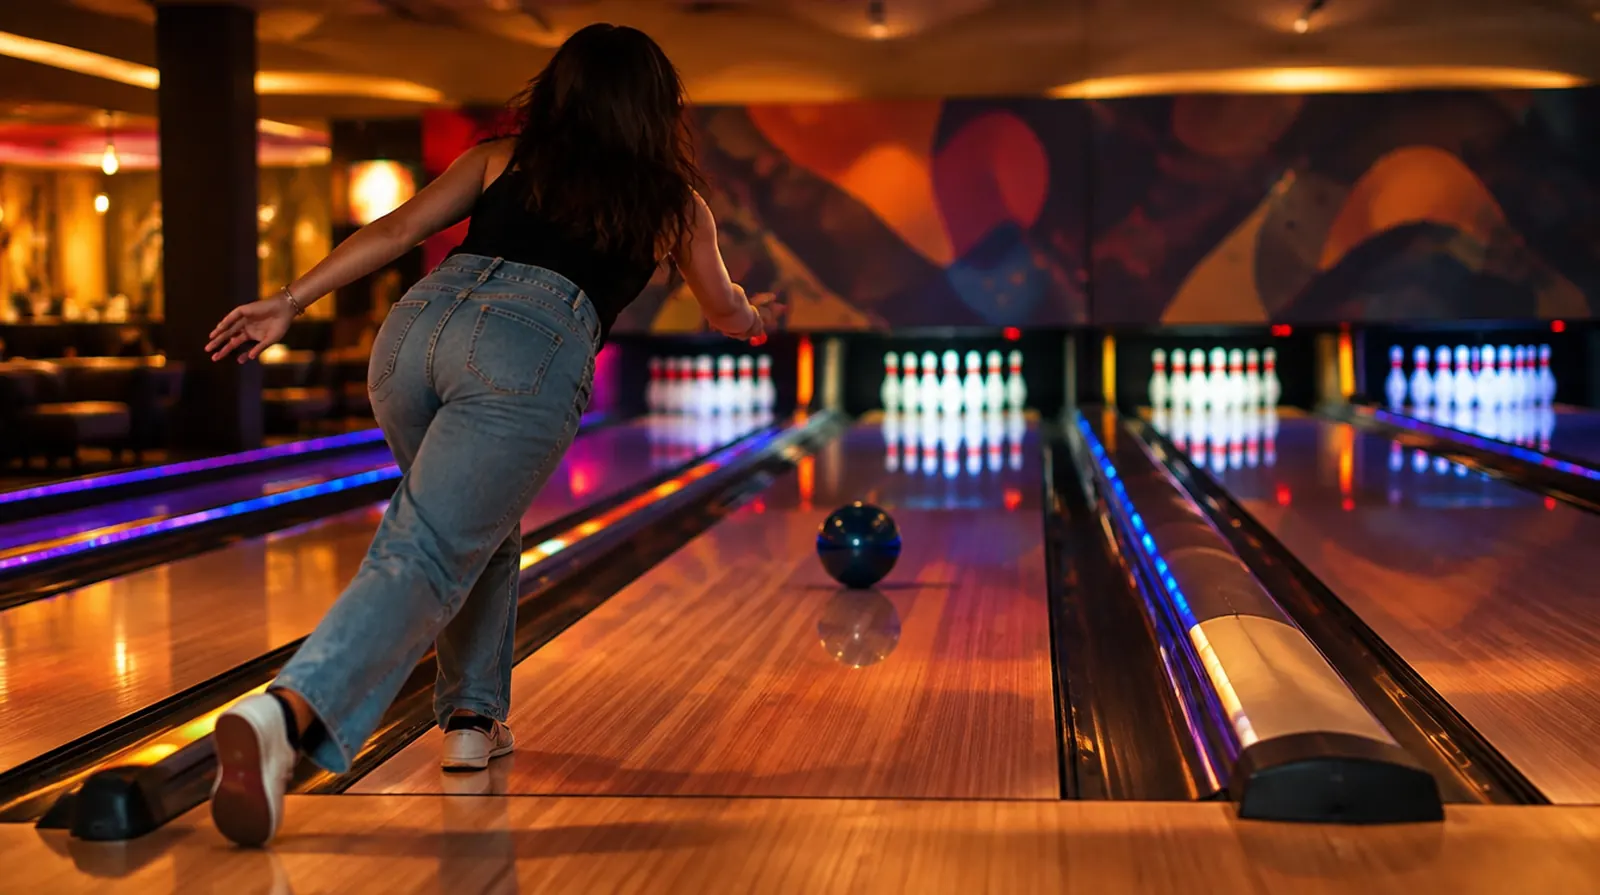
The oiled approach is deliberately slippery. A guest in street shoes, or without bowling shoes, can slip quickly, and the liability question then lands with the operator.
03
Ball return injuries
Fingers get caught in the return, balls drop on feet. Small accidents with a big impact, especially with children.
04
Catering and the bar
Alcohol service, a hot kitchen, a busy bar at the weekend: food poisoning and a fat fire are separate risks alongside the lanes themselves.
05
Children's parties
Groups of children, little supervision from parents, a lot happening at once. Duty of care then sits mostly with staff.
06
Booking system outage
Lanes get booked online and payments run through digital systems. An attack on the booking system can stop advance sales altogether.
For disputes with the landlord, the pinsetter maintenance contractor or a local authority.
What it costs: example prices
The premium is driven mainly by the number of lanes and the value of the pinsetter machinery, plus catering and footfall. A small centre with a handful of lanes costs noticeably less than one with twenty lanes and its own kitchen.
Insurance
Example
Typical range
Business liability
Bowling centre with eight lanes, a bar and five to ten staff
roughly 300 to 700 euros a year
Business contents
Fixtures, bar and shoe hire worth 150,000 euros
roughly 800 to 2,000 euros a year
Machinery breakdown
Eight pinsetter units with a replacement value of 400,000 euros
roughly 2,000 to 5,000 euros a year
Business interruption
Lost profit cover for up to twelve months, alongside the machinery policy
roughly 600 to 1,500 euros a year extra
Cyber insurance
Centre with online booking and card payments, 250,000 euros of cover
roughly 350 to 700 euros a year
For comparison: Public liability and machinery breakdown together cost about as much per year as six months of a pinsetter maintenance contract.
Guide prices excluding insurance tax, as of September 2026.
Few published figures exist for bowling centres specifically,
so these are drawn from comparable public liability and machinery breakdown policies and our own
quoting practice.
The actual quote depends on the number of lanes, the pinsetter type and the maintenance contract.
Six things that genuinely happen at bowling centres, all packed into a single day here. Step through the day and see who pays.
Damage so far€44,700
The pinsetter on lane 3 jams and damages itself trying to clear the fault.
€8,500 · Paid by: Machinery breakdown
Lane 3 stays closed for three days waiting for a spare part.
€2,200 · Paid by: Business interruption
A child in street shoes slips on the approach and breaks a wrist.
€9,000 · Paid by: Business liability
At a children's party, a boy catches his finger in the ball return.
€4,000 · Paid by: Business liability
The fryer in the bar catches fire, leaving the seating area badly smoke damaged.
€12,000 · Paid by: Business contents
The online booking system is hacked, customer data is exposed, a forensic specialist has to be brought in.
€9,000 · Paid by: Cyber insurance
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €44,700
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Check the pinsetter maintenance contract against your machinery policy so you know exactly what each one covers, and that together they leave no gap.
Set up business interruption cover so that a single closed lane counts the same way as a full shutdown.
Include shoe hire and the bar in your contents policy, they are often not automatically part of the sports facility cover.
Brief staff on their duty of care at children's parties and keep a record of what was agreed with parents.
Check that alcohol service and the kitchen are explicitly included in your public liability policy.
Cover the online booking system against outage if a large share of your bookings run through it.
Why NAMMERT for your business
We know the machinery
Pinsetters are not a standard risk. We know which insurers are actually willing to underwrite machinery values for bowling equipment.
We link breakdown and liability
A pinsetter loss is rarely just property damage. We put machinery, business interruption and liability together so no gap opens up between the policies.
Claims experience from our own handling
In boat insurance we handle claims ourselves, including for equipment and machinery. We use that experience when your insurer hesitates after a pinsetter failure.
No fee, one steady contact
The insurer pays our remuneration. You deal with a family business that has kept the same phone number since 1989.
Frequently asked questions
Questions and answers
Is the pinsetter machinery automatically covered?
No.
Many contents policies exclude machinery or cap it at low sums insured.
The pinsetters need a separate machinery breakdown policy.
Who is liable if a guest falls on the approach?
Usually the operator, and public liability responds if the lane was properly maintained and signed.
Missing warnings or no bowling shoe requirement can make a claim harder to settle.
Does insurance pay if a lane is closed for repairs?
Only with business interruption cover,
and only if the closure follows an insured loss, not ordinary wear and tear.
Does a bowling centre need separate catering insurance?
Usually a public liability policy that explicitly includes the catering side is enough,
as long as the kitchen and bar remain secondary to the lanes.
A larger restaurant operation is worth a separate look.
What does insurance cost for a small bowling centre?
For a centre with a handful of lanes and no kitchen,
expect roughly 1,500 to 3,500 euros a year for liability, contents and machinery combined.
More lanes and catering push the premium up.
Is insurance for a bowling centre a legal requirement?
No.
There is no statutory insurance requirement for the business itself,
though local building and safety rules set requirements for public venues.
NAMMERT insurance broker
Request quotes for Bowling alley
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.