Business liability
Pays for scalds, allergic reactions and guests' falls, on the terrace too.
Insurance broker / Business types / Hospitality
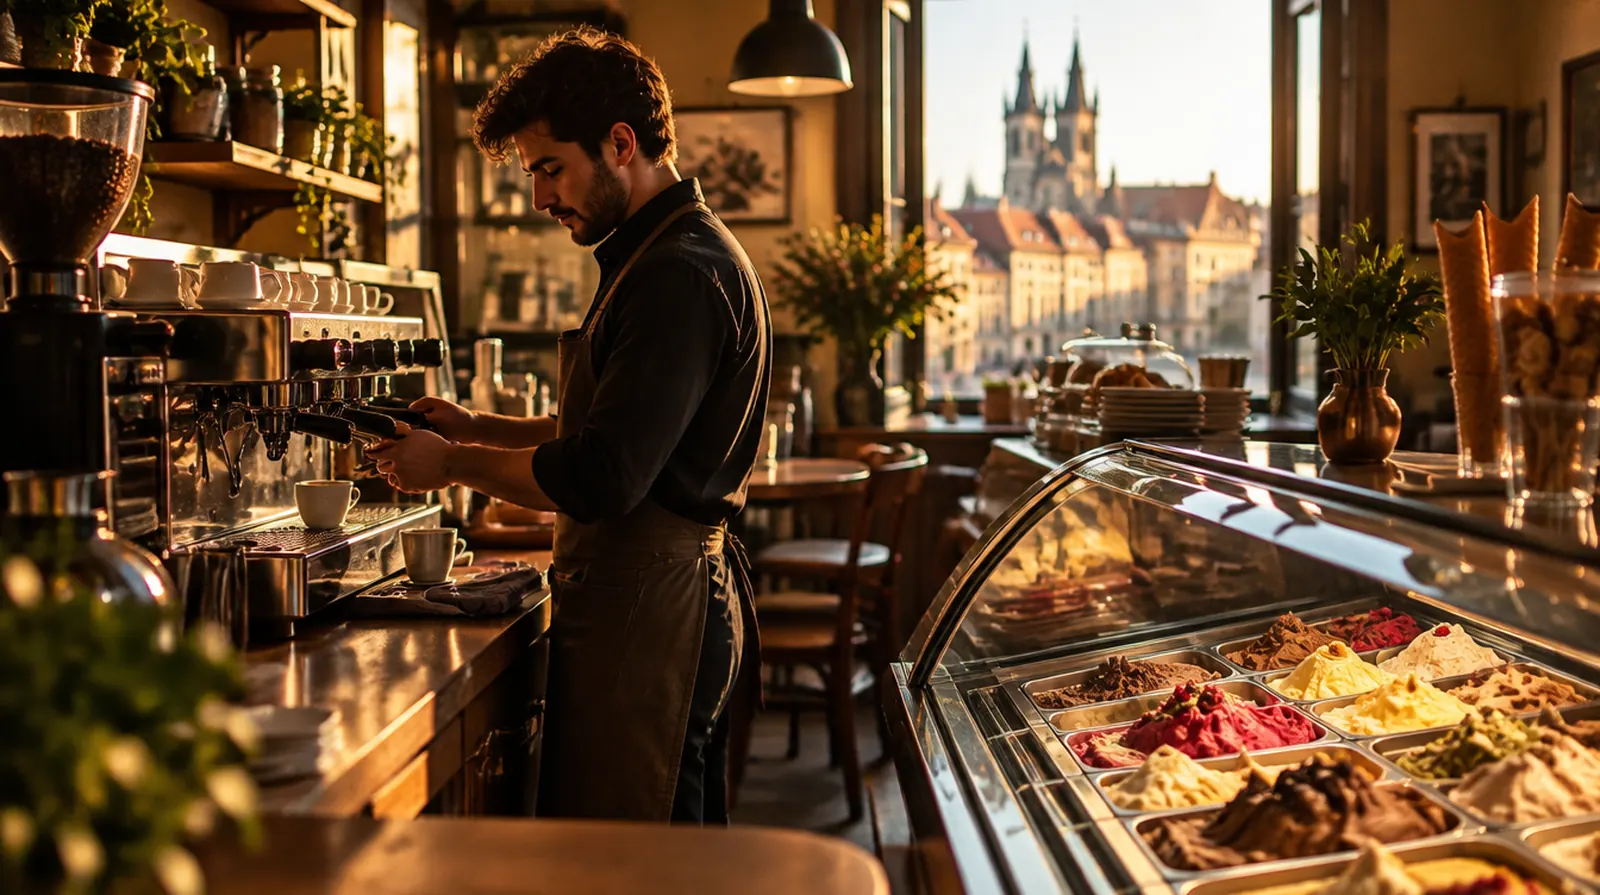
In a café most of the money sits in two machines: the espresso machine and, in an ice cream parlour, the chilled display counter. If either fails, the day is lost, and in summer a broken compressor quickly turns into a week without takings. Add hot drinks spilt on guests, nut allergies and the terrace in a storm. This page shows what you need and what it costs.
The question almost everyone asks first
Not by standard contents insurance, which pays for fire, burst pipes, storm and burglary. A short circuit in the control board, a burnt out boiler or an operating error are matters for electronics or machinery insurance. With a machine costing €10,000 to €20,000 that almost always pays off; wear and limescale are excluded there too, though.
A tray tips, a high chair knocks the table: scalds from coffee and tea are the typical injury claim in a café.
Nuts, gluten, milk: if a label is missing or orders get mixed up, an allergic reaction can be life threatening.
Espresso machine, ice cream maker and chilled counter run all day. If one fails in July, your most important takings are gone.
One overnight power cut, and the entire ice cream stock and the weekend's cakes are lost.
In a thunderstorm, parasols, awnings and furniture become missiles, hitting cars and passers by.
The plumbed in water supply and the dishwasher run all day. A burst hose often floods the cellar or the neighbours.
Compared with other trades, 1 low to 5 high.
Essential
Pays for scalds, allergic reactions and guests' falls, on the terrace too.
Strongly advised
Replaces furnishings, machines and supplies after fire, burst pipes, storm and burglary, with spoiled refrigerated stock included.
Covers espresso machine, ice cream maker, display counter and till against short circuits, power surges and operating errors.
Keeps paying rent and wages if the café is closed after a fire or water damage.
Depends on the business
For disputes with your landlord, staff or the town, for instance over the terrace permit.
If the till system or ordering app is hacked and guest data is affected.
A café is cheaper to insure than a restaurant with a deep frying kitchen. What counts is turnover, number of seats, terrace, whether you bake yourself and the value of machines and counters.
| Insurance | Example | Typical range |
|---|---|---|
| Business liability | Daytime café, around €40,000 turnover, €3 million cover | about €80 to €170 a year |
| Business liability | Café or ice cream parlour with two to five staff and a terrace | about €170 to €600 a year |
| Business contents | Furnishings, machines and supplies worth €60,000 | about €200 to €500 a year |
| Electronic equipment | Espresso machine, gelato counter and till worth €30,000 | about €200 to €450 a year |
| Business interruption | Loss of income for up to twelve months, added to the contents policy | about €80 to €250 a year on top |
For comparison: Basic cover of public liability and contents insurance costs about as much a year as 100 cappuccinos.
Guide prices as of September 2026, based on published tariff examples and on our own quoting practice. If you bake your own cakes or make your own ice cream, liability costs a little more; we obtain the exact quote for you.
01
For: small daytime café or coffee bar without a terrace
Together about €300 to €650 a year
Request this package02
For: café or ice cream parlour with terrace, staff and expensive equipment
Together about €700 to €1,500 a year
Request this package03
For: large café with its own bakery, till system and online ordering
Together about €1,400 to €2,800 a year
Request this packageSix claims of the kind cafés and ice cream parlours really see, all on one hot Sunday in July. Click through the day and see who pays.
A power cut overnight: the ice cream stock and the cakes in the counter have melted.
The espresso machine dies with a bang; the control board has burnt out.
A pot of tea tips over a toddler sitting on his mother's lap. Scalds, hospital, compensation.
A guest with a nut allergy asks, is still served the wrong cake and needs emergency treatment.
A thunderstorm gust tears a parasol from its stand and damages two parked cars.
The machine's water hose bursts and water runs into the building's cellar.
Which package would you have had?
Illustrative amounts before any excess. Whether and how much is paid depends on the policy terms.
As a broker we compare several insurers and make sure your most expensive equipment does not fall between contents and electronics cover.
In boat insurance we settle claims ourselves. We know which questions follow a machine breakdown and which evidence counts.
Café, car, your home and your team's pensions sit with one contact.
Advice is free for you, as the insurer pays our commission. You speak to the same people, year after year.
Questions and answers
Public liability is essential. Contents insurance, electronics or machinery cover for the coffee machine and counter, and loss of income cover all make sense.
Public liability for a small café starts at about €80 a year. With contents insurance, basic cover usually costs between €300 and €650.
Only if spoiled refrigerated stock is in the policy. Make sure a failure of the public grid is included too.
No, the terrace belongs in your public liability and contents policies. Check that outdoor furniture and parasols are covered against storm and theft.
If you labelled or served something wrongly, yes. Public liability pays medical costs and compensation and checks whether the claim is justified.
At work through the BGN, the statutory accident insurer for food and hospitality, including mini jobbers and pupils in holiday jobs.
NAMMERT insurance broker
The recommended covers are already ticked. Change what does not fit; we obtain quotes and come back with a comparison. You can write in English.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.
Will insurance pay if the oven simply breaks down?
Will my insurer pay if guests fall ill after eating?
Is motor insurance enough for my food truck?
Boat or yacht? Here we are not the broker but the underwriting agency, with our own policies and our own claims handling.
Boat insuranceNAMMERT Assekuradeur GmbH, insurance broker licensed under section 34d(1) of the German Trade Regulation Act, broker register no. D-C08Q-TOSD4-37. For boat and yacht insurance we act as underwriting agency, not as broker. Statutory disclosure (German) · Updated