Insurance for DIY stores, hardware shops and paint retailers in Germany
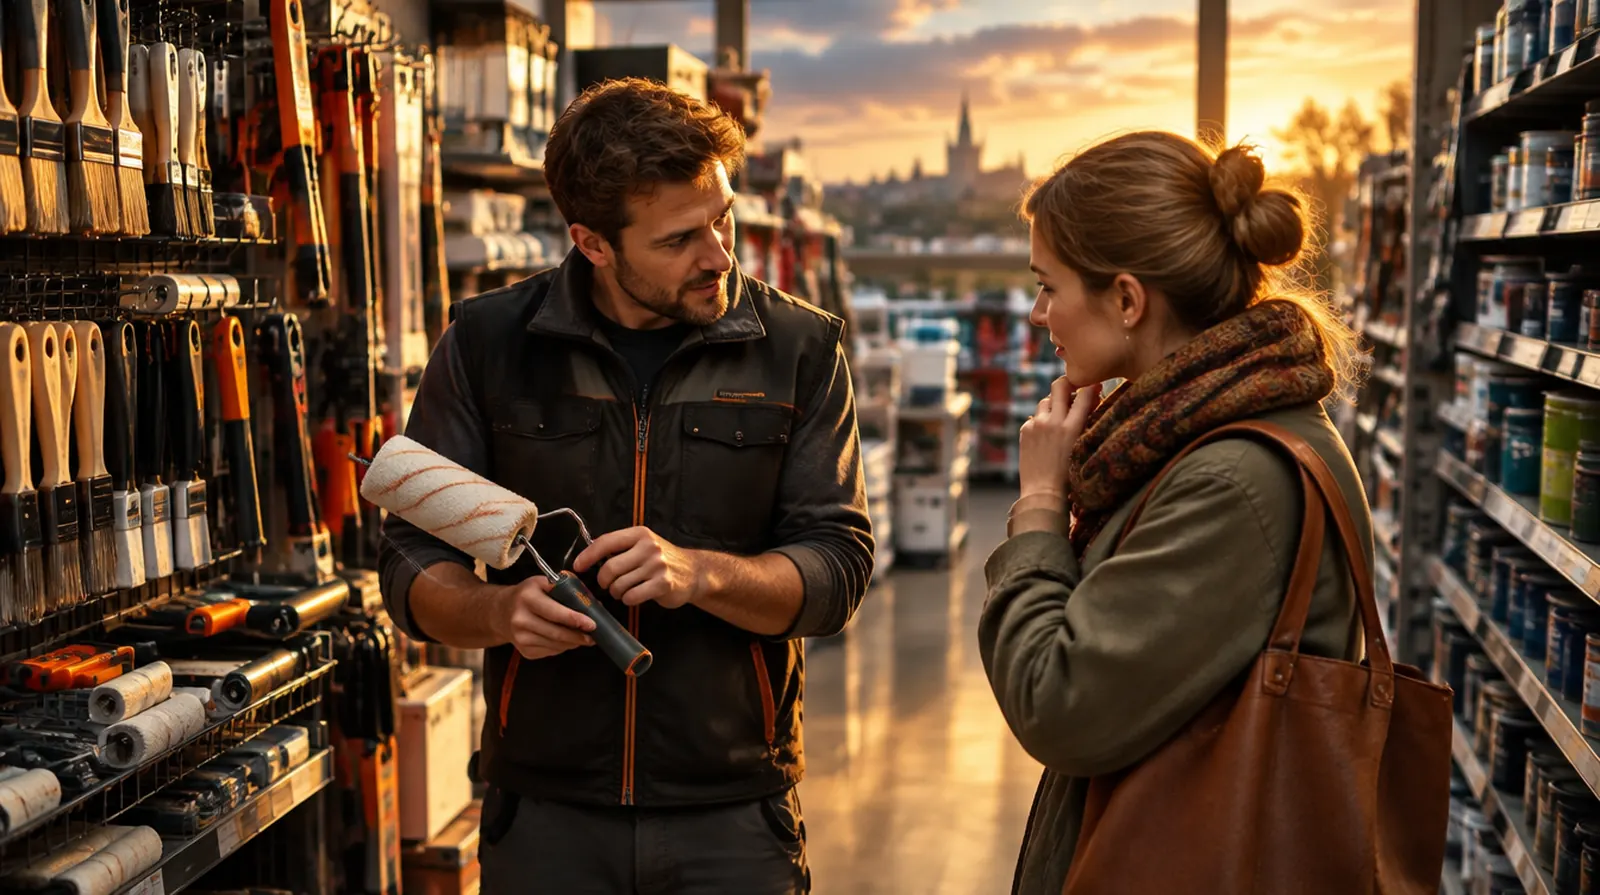
In a DIY store heavy goods are stacked almost to the ceiling, customers hire hammer drills and have timber cut to size, and the shelves hold paint, gas bottles and thinners. Together that makes a particular mix of liability and fire risks. This page shows how to insure them and what it costs.
Am I liable if a customer is injured using a machine they hired from me?
Yes, if the machine was faulty or you did not show the customer how to use it properly. Your public liability policy then pays, provided equipment hire is included. Many retail policies cover only sales. Check every machine before it goes out, record the instructions you gave and hand out protective gear with it.
What goes wrong in this trade
01
Goods from above
Packs of tiles, sacks and boxes four metres up: if something falls while a customer pulls it out or staff restock, it lands on someone's head.
02
Tool hire
Hammer drills, tile cutters, trailers: inexperienced customers hurt themselves or damage other people's property.
03
Flammables on the shelves
Paint, thinners, aerosols and gas bottles can turn a small fire into a major one very quickly.
04
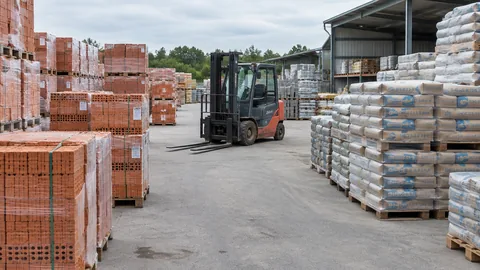
Forklifts and pallet trucks
Forklifts moving among customers and manoeuvring in the outdoor yard lead to accidents involving people and vehicles.
05
Wrong advice
The wrong wall plugs for kitchen cabinets or an unsuitable adhesive in the bathroom: any damage that follows at the customer's home tends to be blamed on whoever gave the advice.
06
Outdoor areas
Black ice in the car park, building materials in the open yard and storms over the garden centre are risks in their own right.
Covers accidents in the store and car park, and damage from hired tools, cutting services and products sold, provided hire and products liability are included.
Tops up the statutory accident cover from the Berufsgenossenschaft for staff who lift heavy loads and spend a lot of time on ladders.
What it costs: example prices
Small hardware and paint shops pay much the same as other retailers. A large store with high racking, tool hire and an outdoor yard is a bigger risk and is priced individually.
Insurance
Example
Typical range
Business liability
Hardware or paint shop, turnover below 500,000 euros
around 200 to 600 euros a year
Business liability
Large store with tool hire and a cutting service
around 800 to 2,500 euros a year
Business contents
Stock and fittings worth 150,000 euros
around 400 to 1,000 euros a year
Machinery breakdown
Forklift, panel saw and hire tools worth 60,000 euros
around 300 to 900 euros a year
Business interruption
Loss of income for up to twelve months for a large store
around 400 to 1,200 euros a year
For comparison: For a small hardware shop, a year of liability and contents insurance costs roughly as much as a set of professional cordless tools off its own shelves: drill driver, circular saw and sander.
Guide figures excluding insurance tax, as of September 2026.
Figures for small shops follow published examples for retail; large stores with hire,
machinery and business interruption are guide figures from our own quoting practice.
Six losses of the kind DIY stores and hardware retailers really see, all on one Saturday in spring. Tap through and find out who pays.
Damage so far€181,500
A customer pulls a pack of laminate from the top shelf and two more land on his shoulder. A fracture and six weeks off work.
€15,000 · Paid by: Business liability
Returning a hired hammer drill, a customer reports that he drilled into his neighbour's water pipe because the depth stop was faulty.
€8,500 · Paid by: Business liability
The panel saw jams, the blade snaps and damages the guide rail.
€4,500 · Paid by: Machinery breakdown
Manoeuvring in the outdoor yard, the forklift backs into a customer's car.
€3,500 · Paid by: Business liability
In the paint department a rag soaked in linseed oil ignites, and shelves and stock go up in flames.
€90,000 · Paid by: Business contents
After the fire the store stays closed for two months in the peak season.
€60,000 · Paid by: Business interruption
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €181,500
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Have tool hire, cutting to size and paint mixing named explicitly in your liability policy.
Check whether goods in the outdoor yard and garden centre are covered against storm and hail.
Follow the fire safety conditions for paint, gas bottles and aerosols, and store them exactly as the policy requires.
Choose at least 5 million euros of cover for personal injury; with lots of customers and heavy goods, 10 million is more sensible.
Insure hire tools against damage and theft while they are with the customer, under machinery insurance.
Train forklift drivers regularly and close off aisles while restocking; insurers will ask what rules you have.
Why NAMMERT for your business
We sort out the extensions
Every insurer handles tool hire, cutting services and outdoor storage differently. As a broker we compare several quotes on exactly these points.
We know large claims
In boat insurance we handle claims ourselves, including fires and total losses. We know how loss of income is calculated and what you need to provide for it.
Store, vehicles and staff in one place
Building, stock, delivery vans, staff benefits and your personal cover are handled by one contact, on +49 3375 29 12 77.
A family business since 1989
Many hardware and building materials dealers are family businesses, just like us. Our work costs you nothing.
Frequently asked questions
Questions and answers
What insurance does a DIY store need?
Public liability that includes tool hire and products liability,
contents insurance for the stock and, for larger stores,
business interruption and machinery insurance.
How much does insurance cost for a hardware shop?
Small shops pay around 200 to 600 euros a year for liability,
and usually 600 to 1,500 euros together with contents insurance.
Am I liable for giving wrong advice?
If your advice was clearly wrong and it caused damage, you may be.
Your liability insurer examines the claim and fends off any that are unjustified.
Is tool hire included?
Not automatically.
Hire must be named in your liability policy,
and the tools themselves need machinery or contents insurance that also applies away from the
premises.
Will insurance pay for a fire caused by paint or solvents?
Yes, fire is covered.
If the store does not keep to agreed storage conditions, however,
the insurer may reduce the payout.
Who pays after a forklift accident?
On your own premises it is usually your business liability policy,
on public roads the forklift's motor third party liability.
Injured employees are looked after by the Berufsgenossenschaft, the statutory accident insurer.
NAMMERT insurance broker
Request quotes for DIY store
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.