Insurance for boutiques, shoe shops and clothing retailers in Germany
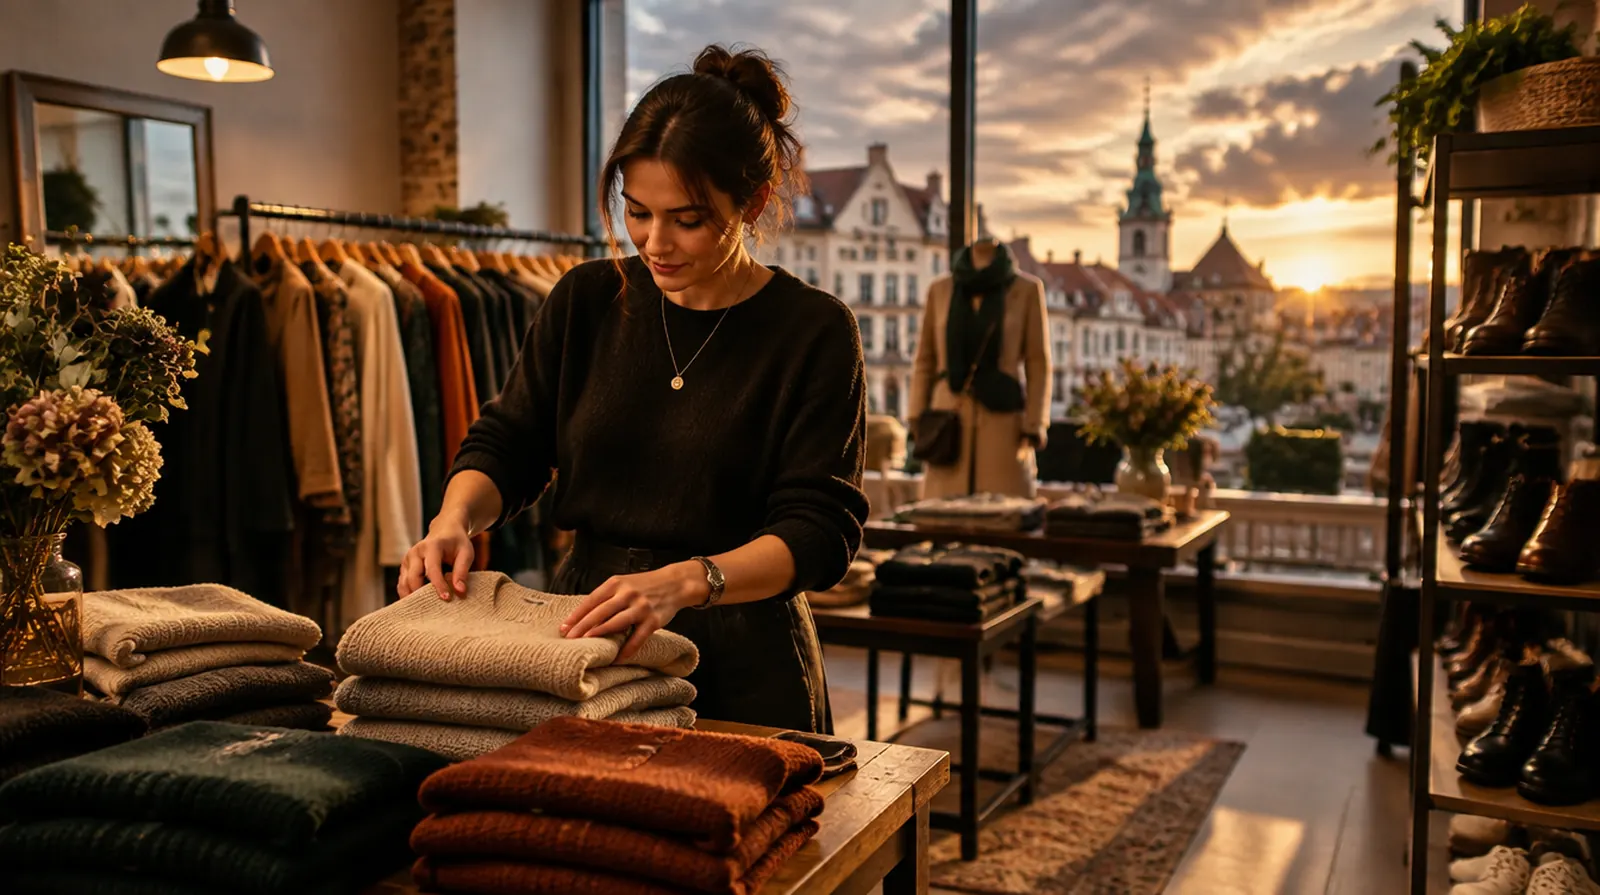
In a fashion shop the value hangs on the rails: new collections, paid for months in advance and often worth more than all the fittings put together. One leak in the stockroom or a fire next door, and the season's stock is unsaleable before it has been sold. This page explains how to protect stock, shop and takings, and what it costs.
Is my stock insured if someone walks out of the shop with it?
Generally not. Contents insurance pays for burglary, meaning someone breaks into the shop, and for robbery involving force or threats. Ordinary shoplifting during opening hours is not covered and remains a business risk. Security tags, mirrors and fitting rooms you can see into are what help here.
What goes wrong in this trade
01
Water in the stockroom
A burst pipe in the flat upstairs, and the winter collection in the basement is soaked, discoloured and smells musty.
02
Fire and smoke
Textiles take on the smell of smoke immediately. Even a fire in the neighbouring shop can make your entire stock unsaleable.
03
Break in after closing
Designer labels, leather jackets and trainers are easy to sell on. Burglars often come through the back door or the shop window.
04
Smashed shop windows
Vandalism, a runaway shopping trolley or a storm: large shop windows quickly cost several thousand euros to replace.
05
Trips and falling stock
A customer trips over a shoebox, a shelf of boots comes loose: people get hurt in fashion retail too.
06
A season without a shop
If the shop has to close after a loss in October, the Christmas trade is gone, and by January the stock only sells at a discount.
For the till system, label printer and anti theft gates, against power surges and operating errors.
What it costs: example prices
Contents insurance is usually the largest item, because stock values are high. Liability is cheap in fashion retail, since customers are rarely seriously hurt.
Insurance
Example
Typical range
Business liability
Boutique or shoe shop with up to three staff
around 80 to 250 euros a year
Business contents
Stock and fittings worth 150,000 euros, including burglary
around 400 to 1,000 euros a year
Business contents
Glass cover for two large shop windows and the entrance door
around 80 to 250 euros a year on top
Business interruption
Loss of income for up to twelve months, combined with contents insurance
around 100 to 350 euros a year
Business legal expenses
Boutique with legal expenses cover for employment and contract law
around 95 to 400 euros a year
For comparison: For a small boutique, liability and contents insurance cost about as much a year as five good pairs of jeans from your own shelves.
Guide figures excluding insurance tax, as of September 2026,
based on published tariff examples for clothing and shoe retailers and our own quoting practice.
Location, security and stock value set the premium; we obtain the exact quote for you.
Six losses that clothing retailers actually suffer, all on one Saturday in November. Tap through and see who pays.
Damage so far€51,800
Water has been dripping from the flat above into the stockroom since the night. Two racks of winter coats are soaked through.
€18,000 · Paid by: Business contents
A customer bumps into a badly fixed clothes rail, and the metal arm hits a child on the head.
€4,000 · Paid by: Business liability
The till system crashes after lightning strikes nearby, and the power supply is scorched.
€1,800 · Paid by: Electronic equipment
The landlord refuses a rent reduction for the water damage, and your lawyer writes to him.
€1,500 · Paid by: Business legal expenses
Drying out keeps the stockroom closed for three weeks and new deliveries arrive too late. Christmas takings are lost.
€12,000 · Paid by: Business interruption
Burglars smash the shop window and take leather jackets and trainers.
€14,500 · Paid by: Business contents
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €51,800
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Agree automatic seasonal cover or a declaration based policy for your peaks, so the full stockroom in autumn is not underinsured.
Add glass breakage for shop windows, display cases and mirrors, as many basic policies leave it out.
Ask about compensation for stock that is only unsaleable because of smoke or smell, not just for goods that actually burned.
Check the security conditions for burglary cover: locks, roller shutters and the maximum cash you may leave in the shop overnight.
Expressly include stock at fashion shows, markets and in an external store, or the cover applies only inside the shop.
Choose 3 to 5 million euros of liability cover; in fashion retail the extra cost between the two is usually small.
Why NAMMERT for your business
We work out the sum insured with you
Underinsurance is the most common mistake in fashion retail. We go through your stock values across the year with you and compare several insurers.
We know how claims are settled
In boat insurance we handle claims ourselves. After water damage, we know that purchase invoices and stock lists make the difference, and we help you prepare them.
Shop and private life together
We look after the shop, online store, car and your personal cover from one place, so there is only one number to call: +49 3375 29 12 77.
A family business since 1989
We are a family firm ourselves and know how much goes into a shop of your own. For you, our advice is free of charge.
Frequently asked questions
Questions and answers
Which insurance does a small fashion shop need?
Public liability and contents insurance for stock and fittings,
usually with glass cover for the shop windows.
Business interruption cover makes sense as soon as a month's closure would put you in difficulty.
What does insurance cost for a boutique?
Liability starts at around 80 euros a year.
With contents insurance, small shops usually pay 350 to 800 euros,
depending on stock value and location.
Is stock held on commission covered?
Only if third party property is included in the contents policy.
Many policies cover only your own stock, so name consignment goods explicitly.
What happens if the shop is underinsured?
The insurer then reduces every claim in proportion.
If your stock is worth 150,000 euros but insured for only 100,000,
a loss of 30,000 euros pays out only about 20,000.
Will insurance pay for stock that smells of smoke?
Yes, if the smoke comes from an insured fire, even in the building next door.
What matters is that the policy includes loss of value and cleaning.
Are my temporary staff insured?
At work they are covered by the BGHW, the statutory accident insurer for retail,
and that includes minijobbers.
You must register the shop there as soon as you employ anyone.
NAMMERT insurance broker
Request quotes for Fashion shop
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.