Business liability
Pays for injury and property damage caused by falling or breaking panes, installation errors and consequential water damage.
Insurance broker / Business types / Construction and trades
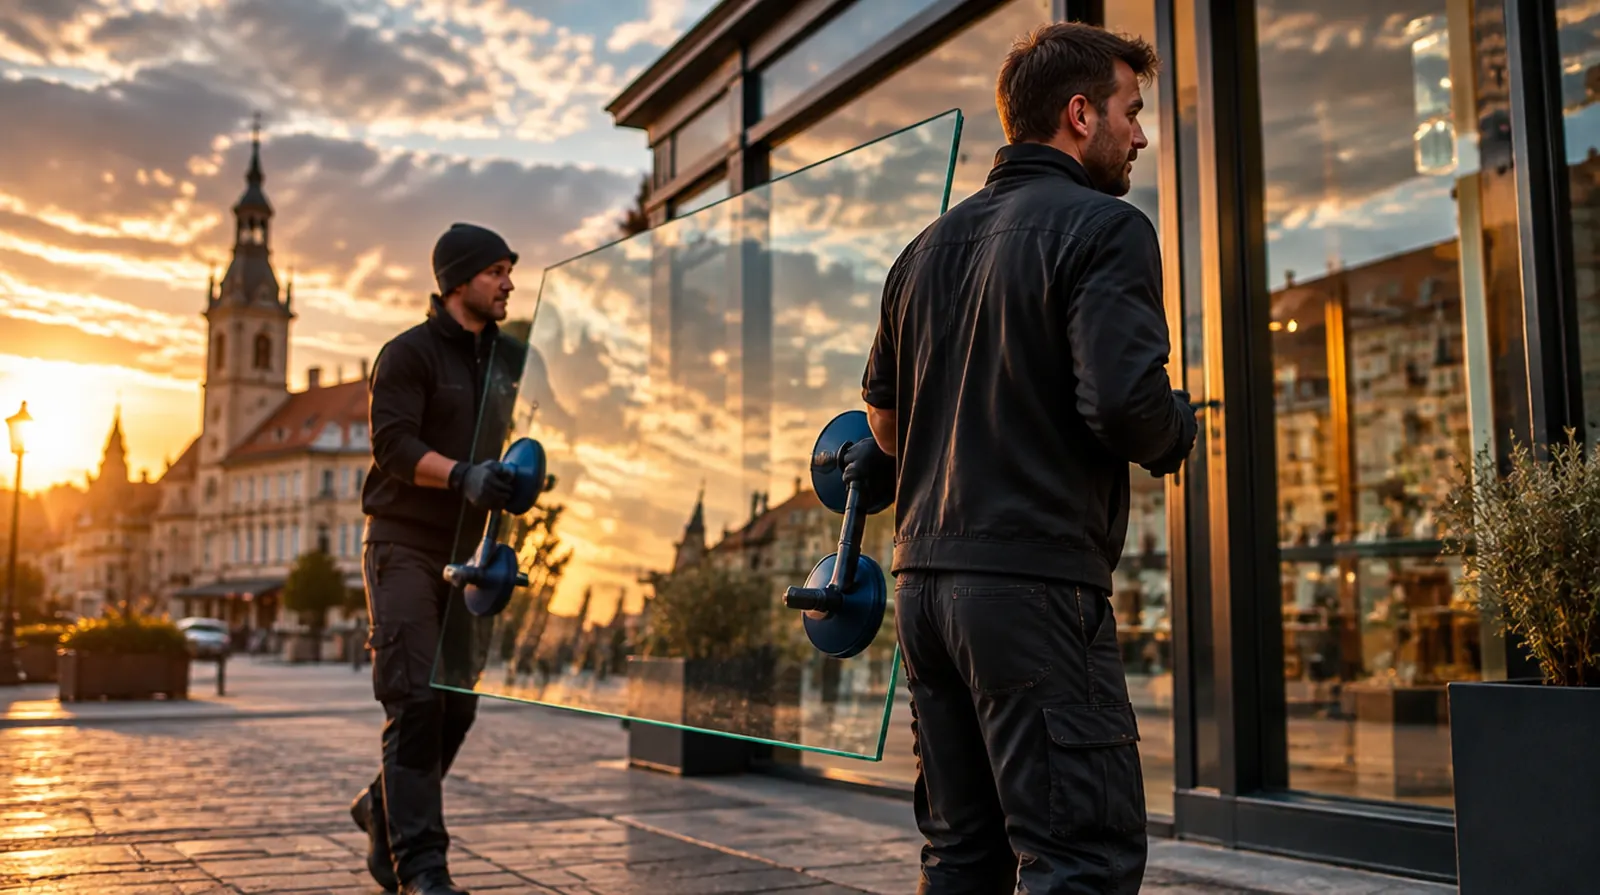
Glass is heavy, sharp and expensive, and it breaks exactly when nobody needs it to: on the glass rack of the van, while being lifted into a facade, or years later when an all-glass door gives way. This page explains which insurance a glazing business needs and what it costs.
The question almost everyone asks first
The broken pane itself is your risk as long as it has not been installed and accepted; liability insurance does not pay for it. But if the falling pane damages the floor or furniture or injures someone, your public liability policy pays for that damage. For the pane on its way to the customer, transit insurance helps, and for large commercial jobs, erection insurance.
Large insulating and safety glass panes on the external rack: one emergency stop, one pothole, and the load is lost.
When lifting with a vacuum lifter, a pane can fall and hit people, cars or floors.
A wrongly fixed all-glass door, a balustrade without safety glass: cuts can be severe and happen years after installation.
During night-time emergency glazing you are alone in a customer's shop. Lost keys or doors not secured again lead to burglaries.
Installation mistakes let rain run into the reveal. The consequential damage to plaster and floors only shows later.
Heavy panes and sharp edges cause cuts and back injuries.
Compared with other trades, 1 low to 5 high.
Essential
Pays for injury and property damage caused by falling or breaking panes, installation errors and consequential water damage.
Strongly advised
Covers breakage of glass on the transport rack and tools in the vehicle.
Replaces the glass store, cutting table and workshop after fire, storm and burglary.
Glass cutting, edge grinding and insulating glass lines are expensive and break down after operating errors.
Depends on the business
Keeps paying if the workshop stands still after a fire or machinery breakdown.
A cut to the hand or tendons can end your work with glass; income protection keeps your earnings going.
Business legal expenses cover for disputes over delivery times, measuring errors and sign-off on facade and commercial jobs.
Glaziers sit in the middle of the finishing trades for liability premiums. It gets considerably more expensive with facade work, all-glass systems and emergency call-outs.
| Insurance | Example | Typical range |
|---|---|---|
| Business liability | small business, repairs and window replacement | about €210 to €500 a year |
| Business liability | three to eight employees with all-glass systems and facades | about €600 to €1,800 a year |
| Cargo insurance | two vehicles with glass racks, up to €10,000 per claim | about €200 to €500 a year |
| Business contents | Workshop with glass store and cutting worth €80,000 | about €300 to €800 a year |
For comparison: Liability and transit cover for a small glazing business costs about as much per year as two fitted double-glazed units for a living room window.
Guide prices excluding German insurance premium tax, as of September 2026. The entry price comes from a published tariff example; the other ranges are guide values from our quoting practice and from comparable finishing trades, because hardly any tariff examples for glaziers are published. We obtain the exact quote for you.
01
For: glazier working alone, repairs and emergency call-outs
Together about €400 to €1,000 a year
Request this package02
For: workshop with cutting and three to eight employees
Together about €1,300 to €3,500 a year
Request this package03
For: facades, all-glass systems and commercial projects
Together about €3,500 to €8,000 a year
Request this packageSix claims that glazing businesses really experience, all on a single Friday. Go through the day and see who pays.
After emergency glazing at a shop, the back door is left unlocked. There is a break-in that night.
During an emergency stop, three large double-glazed units break on the external rack.
While lifting in a shop window, the vacuum lifter slips. The pane shatters on the natural stone floor.
An all-glass shower door fitted last year comes out of its hinge. The customer suffers cuts.
The cutting head of the glass cutting table fails after an operating error.
A storm pushes in the workshop's roller door and the glass store topples over.
Which package would you have had?
Illustrative amounts before any excess. Whether and how much is paid depends on the policy terms.
Transit breakage, installation and emergency call-outs are the gaps for glaziers. We compare several insurers on exactly these points.
In boat insurance we settle claims ourselves, including broken windows and hatches. We know what surveyors check with glass.
Workshop, vehicles, liability and your private provision are handled by one contact person.
We are a family business and not an agent of any insurer. The insurer pays our remuneration, so the advice is free for you.
Questions and answers
Not by law, but it is required for every larger job. Glass breakage with injuries can threaten your livelihood without insurance.
Published tariffs start at around €210 a year. With employees, facades and all-glass systems, premiums in our experience usually range from €600 to €1,800.
Not under liability and not under motor insurance. For that you need transit or tools in transit cover that includes breakage.
If it is down to your installation or the wrong glass, your public liability policy pays for the injury, even years after fitting.
The activity is, if it is in the policy. Pay attention to lost keys and to damage if premises are not properly secured after the call-out.
It depends on your main activity, usually BG Holz und Metall or BG BAU, both statutory accident insurers. Your notice of competence gives the answer.
NAMMERT insurance broker
The recommended covers are already ticked. Change what does not fit; we obtain quotes and come back with a comparison. You can write in English.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.
Boat or yacht? Here we are not the broker but the underwriting agency, with our own policies and our own claims handling.
Boat insuranceNAMMERT Assekuradeur GmbH, insurance broker licensed under section 34d(1) of the German Trade Regulation Act, broker register no. D-C08Q-TOSD4-37. For boat and yacht insurance we act as underwriting agency, not as broker. Statutory disclosure (German) · Updated