Insurance for nurseries, childminders and childcare in Germany
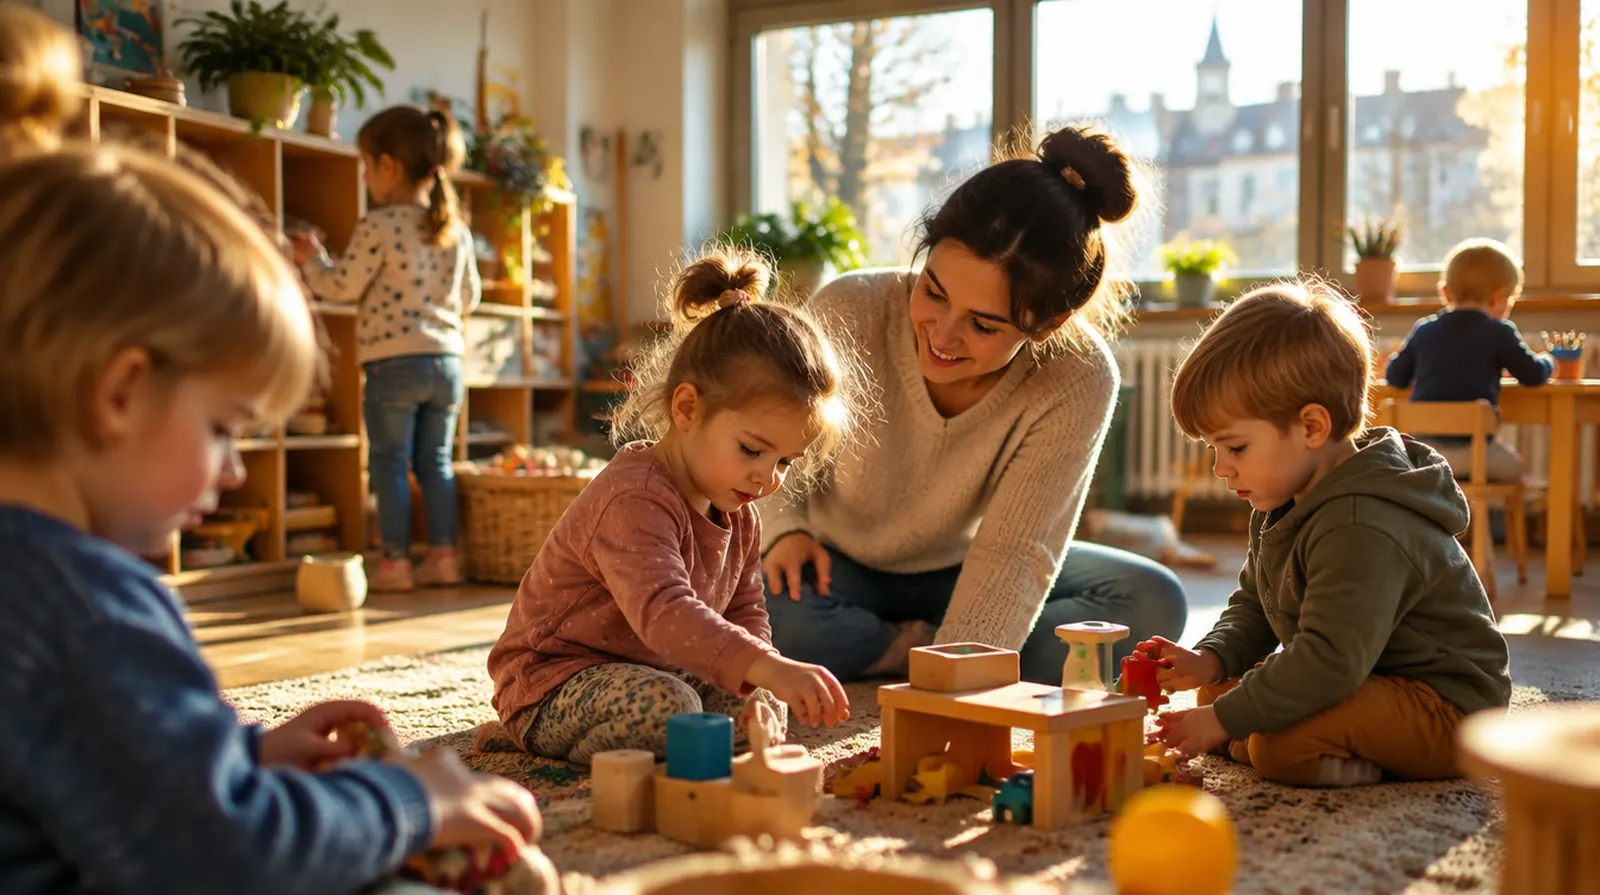
Looking after small children carries a responsibility you cannot hand on to anyone else. The children themselves are covered for accidents by law through the Unfallkasse, but your liability towards parents and third parties is not. On top of that come premises, play equipment, outings and, in parent run nurseries, a volunteer board that makes a lot of decisions.
Treatment, rehabilitation and any pension for the child are paid by the statutory accident insurance, because children in nurseries and with suitable childminders are covered there. It does not pay compensation for pain and suffering, and the Unfallkasse can claim money back from you in cases of gross negligence. In that case, and for damage to property and third parties, for example when a child scratches a car, your liability policy pays.
What goes wrong in this trade
01
Duty of supervision
A child climbs over the fence, swallows a magnet or falls off the changing table. The question is always whether supervision was right for the child's age.
02
Damage caused by children
One child throws a stone at a parked car, another locks themselves in the bathroom and leaves the tap running. As the supervising adult, you are liable for the children in your care.
03
Outings and walks
The walk to the playground, the trip to the woods, crossing a road with ten children: outside, the risk goes up.
04
Water and fire on the premises
Children's kitchen, a washing machine for bibs, hot water at the changing area: burst pipes and fires hit furnishings and the rented rooms.
05
Data and photos
Development reports, allergies, photos in the nursery app: children's data enjoys special protection, and a breach affects many families.
06
Strain on carers
Backs, infections, noise: childminders and nursery staff are off sick more often, and with a childminder the care then stops.
Covers liability from your duty of supervision, damage that children in your care cause to third parties and damage to rented rooms, including on outings.
Helps independent providers attract and keep qualified staff, who are in demand everywhere.
What it costs: example prices
Childminders pay little for their liability cover, often through group schemes run by associations. Nurseries run by independent providers are priced by number of places, staff and turnover; parent run nurseries are usually cheaper to insure than large providers.
Insurance
Example
Typical range
Business liability
Childminder with up to five children in their own home
about 50 to 120 euros a year
Business liability
Parent run nursery with 25 places, liability including a financial loss module
about 250 to 600 euros a year
D&O insurance
Board of a provider association with a budget of up to 500,000 euros
about 150 to 400 euros a year
Business contents
Furnishings and play materials of a nursery worth 50,000 euros
about 150 to 300 euros a year
Cyber insurance
Provider with nursery app and digital billing, 250,000 euros cover
about 350 to 550 euros a year
For comparison: A childminder's liability cover costs about as much a year as one pack of nappies a month.
Guide prices excluding German insurance tax, as of September 2026,
based on published tariff examples for associations and contents and on our own quoting experience.
Childminders can often join low cost group schemes through associations,
Six things that really happen in nurseries and with childminders, all on a single Wednesday. Tap through the day and see who pays.
Damage so far€86,100
At drop off, a child pushes the car door into a parked car, leaving a deep scratch in the neighbour's paintwork.
€1,400 · Paid by: Business liability
On an outing, a child runs into the road and is hit by a cyclist; the cyclist falls and breaks a collarbone.
€8,500 · Paid by: Business liability
A blocked basin in the washroom overflows, and the water seeps into the doctor's surgery on the ground floor.
€7,200 · Paid by: Business liability
A short circuit in the children's kitchen sets the kitchen and group room on fire.
€35,000 · Paid by: Business contents
Through the hacked nursery app, photos and allergy data of 60 children are sent out.
€12,000 · Paid by: Cyber insurance
The board of the parent run nursery has accounted for grants incorrectly; the state reclaims the money and the association holds the board liable.
€22,000 · Paid by: D&O insurance
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €86,100
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Have damage caused to third parties by children in your care, and your duty of supervision on outings, expressly included.
Childminders should cover damage caused by the children to their own home, which many policies exclude.
Choose at least 5 million euros of cover; injuries to children can have lifelong consequences.
Apply to the Jugendamt for reimbursement of your accident insurance contributions and half of your pension contributions under § 23 SGB VIII (German Social Code Book VIII).
Check whether damage to rented rooms from water and fire is covered.
Take out D&O cover for the board of a parent run nursery, even though it works on a voluntary basis and changes every year.
Why NAMMERT for your business
We compare association schemes too
Many childminders are insured through group schemes. As a broker we check whether these are enough and get alternatives from several insurers.
We know claims from the inside
In boat insurance we handle claims ourselves, including with children on board. We know which questions about supervision an insurer asks and how to answer them.
One contact for work and family
Childminding often happens in your own home. We match liability, household contents, buildings cover and income protection so there is no gap between work and private life.
A family business since 1989
We take time for parent run nurseries with changing boards. Our work is free for you, as the insurer pays our commission.
Frequently asked questions
Questions and answers
Are children with a childminder covered for accidents?
Yes.
With a suitable childminder within the meaning of SGB VIII,
children are covered by law through the Unfallkasse, just as they are in nurseries.
This pays for treatment and consequences, but not for pain and suffering.
Does a childminder need their own liability insurance?
Yes.
Personal liability insurance usually does not cover looking after other people's children
professionally, or only to a limited extent.
The Jugendamt usually asks for proof before granting the childminding licence.
Who pays if a child in our care breaks something?
If you breached your duty of supervision, your liability insurance.
If you supervised properly, often nobody is liable.
Good policies still pay such claims up to a limit, to avoid disputes with parents.
Is the childminder personally covered for accidents?
Self employed childminders are insured with the BGW and pay contributions there.
The Jugendamt reimburses proven accident insurance contributions.
Is the board of a parent run nursery personally liable?
Under § 31a BGB (German Civil Code),
volunteer board members are only liable for intent and gross negligence.
Such mistakes do happen, though, with grants, staff and tax.
D&O cover protects your private assets.
What does insurance for a nursery cost?
A small parent run nursery usually pays about 550 to 1,300 euros a year for liability,
contents and D&O.
Large providers with their own buildings pay considerably more.
NAMMERT insurance broker
Request quotes for Nursery
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.