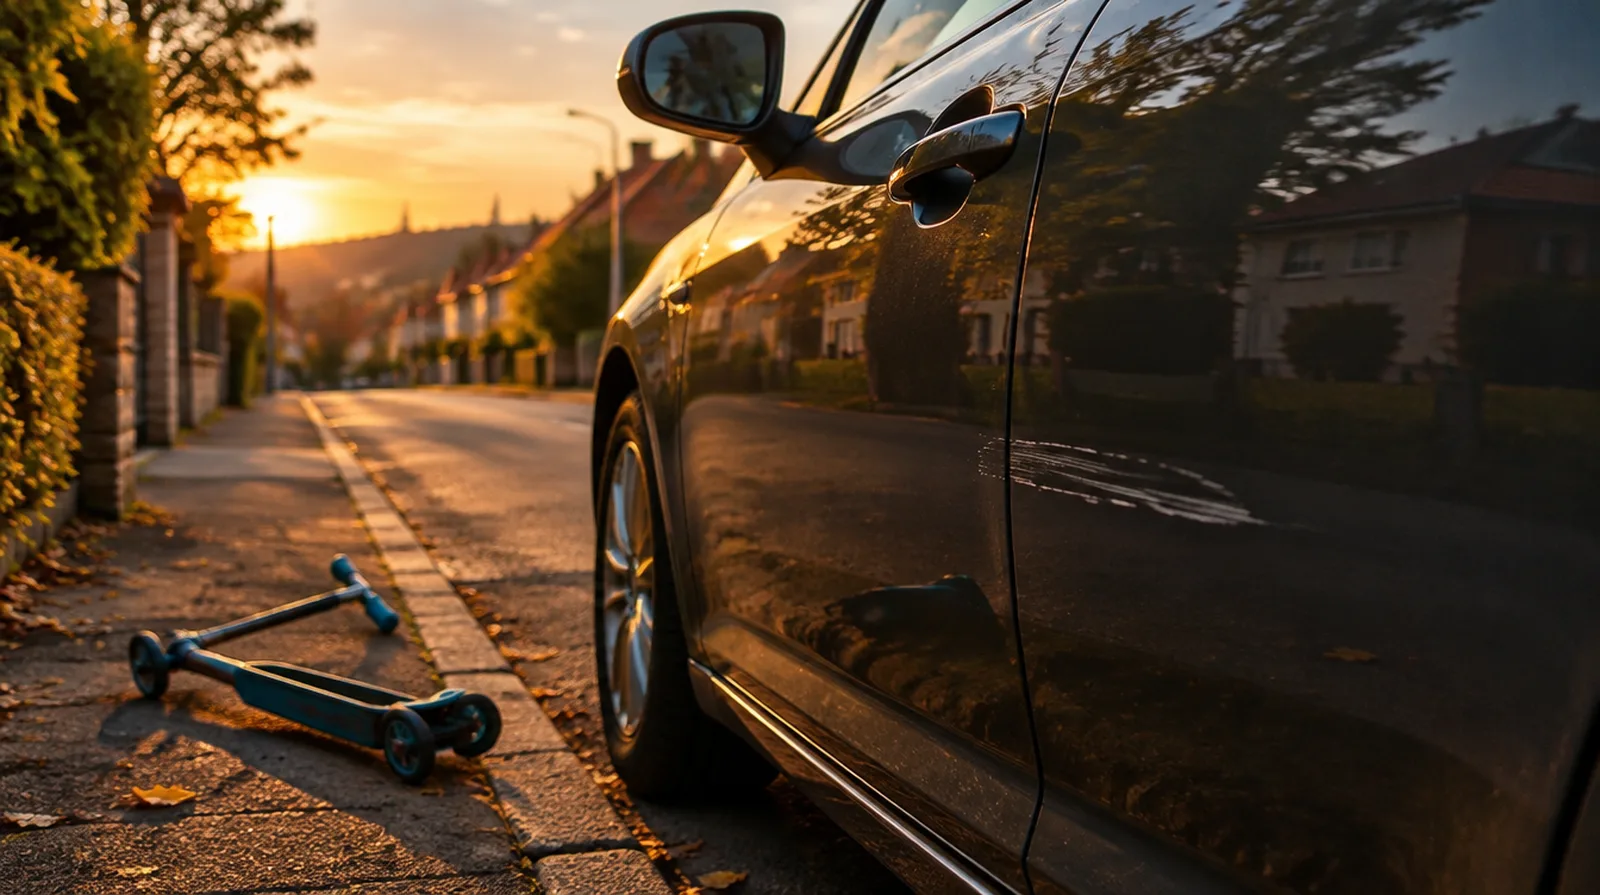
Often nobody. Under German law (§ 828 BGB) children under seven are not liable, and parents only pay if they failed in their duty to supervise (§ 832 BGB). So that the other person still gets paid, many liability policies also cover damage caused by such children, usually up to a sub-limit between EUR 10,000 and the full sum insured.
What a family policy with this option costs, based on published tariff examples and test results.
Example
Typical range
Family with children, cover EUR 10 to 50 million
about EUR 60 to 180 a year
Very good family tariffs in a consumer test
from about EUR 48 a year, average around EUR 99
Sub-limit for children under seven in basic tariffs
about EUR 10,000 to 25,000
Sub-limit in good family tariffs
EUR 50,000 up to the full sum insured
Guide values as of September 2026 from publicly quoted tariff examples and test results.
The extra cost of a higher sub-limit is a guide value from our quoting practice;
we obtain the exact quote for you.
Worked example
Four-year-old throws a stone at the neighbour's car
Her mother was within sight, so the duty to supervise counts as fulfilled. This is how the bill works out.
Paint damage to door and wing
about EUR 2,800
Liability of the child under § 828 BGB
none
Liability of the mother under § 832 BGB
none
Policy with the option, sub-limit EUR 50,000
pays EUR 2,800
Without the option the neighbour would be left with EUR 2,800. With it the damage is paid, minus any deductible.
What German law says
A child who is not yet seven is not responsible for damage. For accidents involving a car, a train or a suspension railway this limit applies up to the tenth birthday, unless the child acted on purpose. Both rules are in § 828 BGB.
Parents are not automatically liable. They only have to pay if they breached their duty to supervise (§ 832 BGB). What counts as proper supervision depends on the child's age and character and on the situation. A five-year-old must not play alone by the road, but nobody has to stand next to a child every second.
What is different if you come from abroad
In the UK or US there is no fixed age at which a child becomes responsible; courts decide case by case. Germany uses clear age limits. The familiar sign on German building sites saying parents are liable for their children (Eltern haften für ihre Kinder) is therefore misleading.
For families from abroad this often comes as a surprise: if your child breaks something at a friend's home and you were supervising properly, the law says nobody has to pay. Many German families still expect the damage to be settled, which is why the policy option described here is common.
Why the other person often gets nothing
If neither the child nor the parents are liable, liability insurance has nothing to pay. Its job is to pay justified claims and fight unjustified ones. For the neighbour with the scratched car that is bitter, and often for the friendship too.
That is why there is cover for damage by children under seven. The insurer then pays voluntarily, as if the child were liable, up to the amount stated in the policy.
Case
Who pays without the option
With the option
Child, 4, scratches a car while playing, parents were watching
nobody
the parents' liability insurance up to the sub-limit
Child, 5, alone by the road, a cyclist falls
the parents' liability insurance, because supervision failed
the parents' liability insurance
Child, 8, rides a bike into a parked car
the parents' liability insurance, because the child is liable
the parents' liability insurance
Child, 3, damages the parents' own things
nobody, no third person was harmed
nobody
Which sub-limit makes sense
Sub-limits range from EUR 10,000 to the full sum insured. A broken vase needs little, a damaged car quickly costs five figures. If a person is injured, EUR 10,000 is rarely enough.
Good family tariffs pay up to the full sum insured. The extra cost is usually small.
When you do not need the option
Once your children are older than seven and no longer in the special road traffic age, the option matters less. Older children are liable themselves if they understood what they were doing, and they are covered by your family policy. You do not need to switch for that.
Step by step
Look for damage by children under seven (deliktunfähige Kinder) in the benefits overview.
Read the sub-limit and check whether it also covers injuries to people.
If it is below EUR 30,000, compare a newer tariff.
In a claim, describe honestly who was supervising and where.
Report the damage even if you think nobody is liable.
Checklist
Option for children under seven included
Sub-limit at least EUR 30,000, better the full sum insured
Also applies in road traffic up to the tenth birthday
Also applies to grandchildren or visiting children if they often stay with you
Deductible for this option known
Common mistakes
Promising the other person payment straight away instead of reporting the claim
Assuming parents are always liable for their children
Settling for a EUR 10,000 sub-limit although injuries to people are possible
Questions and answers
Frequently asked
Are parents always liable for their children?
No.
The sign on building sites is not accurate.
Parents are only liable if they failed to supervise properly.
From what age is a child liable?
From the seventh birthday, if the child had the necessary understanding.
For accidents with cars and trains only from ten, unless it was intentional.
Does liability insurance pay if my child breaks something at a friend's home?
With the option for children under seven usually yes, up to the sub-limit.
Without it only if supervision was neglected.
What if the child is with the grandparents?
Then the grandparents usually have the duty to supervise.
Whether their policy pays depends on their contract and on how they supervised.
Do I have to pay myself although I am not liable?
Legally no.
Many people pay anyway to keep the peace.
This is exactly what the option is for, so it does not come out of your own pocket.
Can a child be liable for reasons of fairness?
In exceptional cases yes, under § 829 BGB, for example if a child is very wealthy.