Insurance for demolition, strip-out and earthworks in Germany
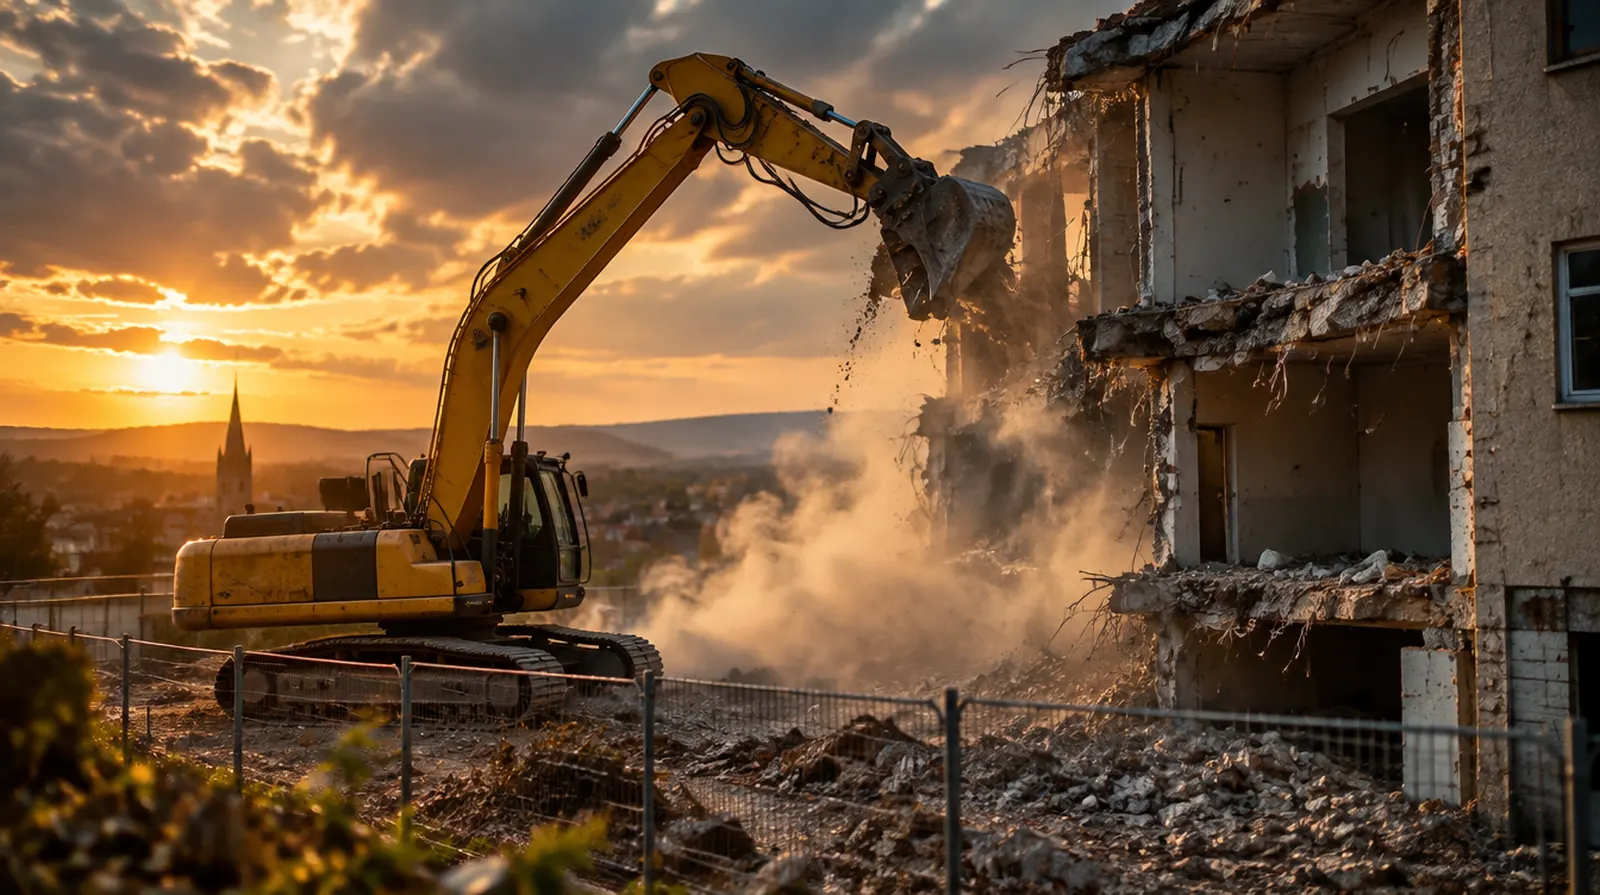
Demolition means working against the structure, right next to houses that are meant to stay standing. Vibration, dust, asbestos and heavy machinery make demolition one of the most expensive risks insurers take on in the building trades. This page explains what your firm needs, what it costs and where policies often have gaps.
Will my liability policy pay if the neighbour's gable wall cracks during demolition?
Only if your policy expressly includes demolition and pulling-down work as well as vibration damage. Many standard policies for building trades exclude or heavily restrict exactly these activities because they are expensive. Insurers also often require a safety distance or a pre-demolition condition survey. Compare your policy with the job before the excavator arrives.
What goes wrong in this trade
01
Vibration and collapse
Demolishing next to standing buildings causes cracks; in the worst case, walls fall uncontrolled onto neighbouring plots.
02
Asbestos and hazardous substances
Undetected asbestos sheets, tar-containing roofing felt or oil in the ground: contaminating neighbouring land and groundwater is expensive and hard to insure.
03
Dust on cars and facades
Demolition dust drifts across whole streets. Cleaning cars, windows and solar panels adds up.
04
Live services in old buildings
Gas, power or water lines that were not disconnected in the building lead to explosions, fires and outages.
05
Heavy machinery
Demolition excavators, shears and crushers are expensive, get damaged or are stolen from the site at night.
06
People in the danger zone
Onlookers, workers from other firms or your own staff are hit by falling debris.
Pays for damage to neighbours, vibration damage and damage to underground lines, if demolition, pulling down and blasting are expressly insured and environmental liability and environmental damage are included.
Business legal expenses cover for disputes with neighbours, authorities and clients about damage, conditions and disposal costs.
What it costs: example prices
Demolition firms are among the most expensive risks in construction. Even with a small turnover, liability premiums run into four figures, and not every insurer writes demolition at all.
Insurance
Example
Typical range
Business liability
€50,000 turnover, €3 to €5 million cover, €250 excess
about €1,400 to €3,650 a year
Business liability
€200,000 turnover, €3 to €5 million cover
about €1,550 to €3,900 a year
Business liability
€500,000 turnover, €3 to €5 million cover
about €2,600 to €7,900 a year
Machinery breakdown
Demolition excavator with attachments worth €250,000
about €2,500 to €6,000 a year
For comparison: Liability insurance for a small demolition firm costs roughly as much per year as demolishing a precast concrete garage including disposal.
Guide prices excluding German insurance premium tax, as of September 2026.
Liability comes from published tariff comparisons;
machinery is a guide value from our quoting practice.
Asbestos, blasting and hazardous substance work change the premium considerably.
Six claims as demolition firms really experience them, all on a single Tuesday. Go through the day and see who pays.
Damage so far€200,500
Overnight, the hydraulic breaker was removed from the parked excavator and stolen.
€24,000 · Paid by: Machinery breakdown
While pulling down the warehouse wall, cracks appear in the gable wall of the adjoining house.
€88,000 · Paid by: Business liability
A water pipe in the basement that was never disconnected bursts and floods the neighbour's cellar.
€16,000 · Paid by: Business liability
Demolition dust settles on twenty cars at the car dealership next door. All of them need valeting.
€9,500 · Paid by: Business liability
The hydraulic pump of the demolition excavator bursts. A hired machine for two weeks keeps the site running.
€21,000 · Paid by: Business interruption
Oil leaks from a damaged heating oil tank into the soil. The ground has to be excavated and disposed of.
€42,000 · Paid by: Business liability
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €200,500
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Check that demolition, pulling-down and, if relevant, blasting work are expressly named in the policy; standard tariffs for building trades often exclude them.
Environmental liability and environmental damage insurance belong in every demolition firm's policy, with a separate limit for soil and groundwater.
Choose at least €5 million cover, and preferably €10 million for inner-city demolition.
Have asbestos and hazardous substance removal included if you do it yourself; otherwise exactly that loss stays with you.
Secure machines with immobilisers and tracking; many insurers lower the premium for it or require it for theft cover.
Commission a condition survey of neighbouring buildings before you start and give it to the insurer.
Why NAMMERT for your business
We find insurers who write demolition
Many insurers decline demolition or exclude the core work. As a broker we approach several insurers that genuinely want to carry the risk.
Difficult claims are our craft
In boat insurance we handle claims ourselves, including environmental damage from spilt fuel. We know how to document cause and costs properly.
Machinery, fleet and liability together
In demolition everything is connected. We look after liability, machinery and vehicles in one view, so no gap is left between the policies.
Family business since 1989
Our advice costs you nothing; the insurer pays our remuneration. You have one fixed contact person who knows your sites.
Frequently asked questions
Questions and answers
Why is liability insurance so expensive for demolition firms?
Because the potential damage to neighbouring buildings,
underground lines and the environment is very high.
Published comparisons show premiums of about €1,400 to €3,650 a year even at €50,000 turnover.
Does ordinary building trades liability cover demolition work?
Often not, or only to a small extent.
Demolition and pulling down must be named as activities, or a claim may be refused.
Is asbestos damage covered?
Only if expressly included.
Many policies exclude asbestos.
If you remove asbestos, you need a specialist policy and the required proof of expertise.
What is the difference between environmental liability and environmental damage insurance?
Environmental liability pays for damage claimed by third parties,
such as a neighbour with a contaminated well.
Environmental damage insurance pays for remediation ordered by an authority under the German
Environmental Damage Act, for example to waters or protected land.
Is my demolition excavator insured against overturning?
Not under liability.
Damage to your own machine from overturning,
operating errors or theft is covered by machinery insurance.
Do I need different insurance for earthworks?
Earthworks can sit in the same policy but must be named.
What matters then is damage to underground lines and subsidence caused by excavation.
NAMMERT insurance broker
Request quotes for Demolition
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.