Insurance for laundries and dry cleaners in Germany
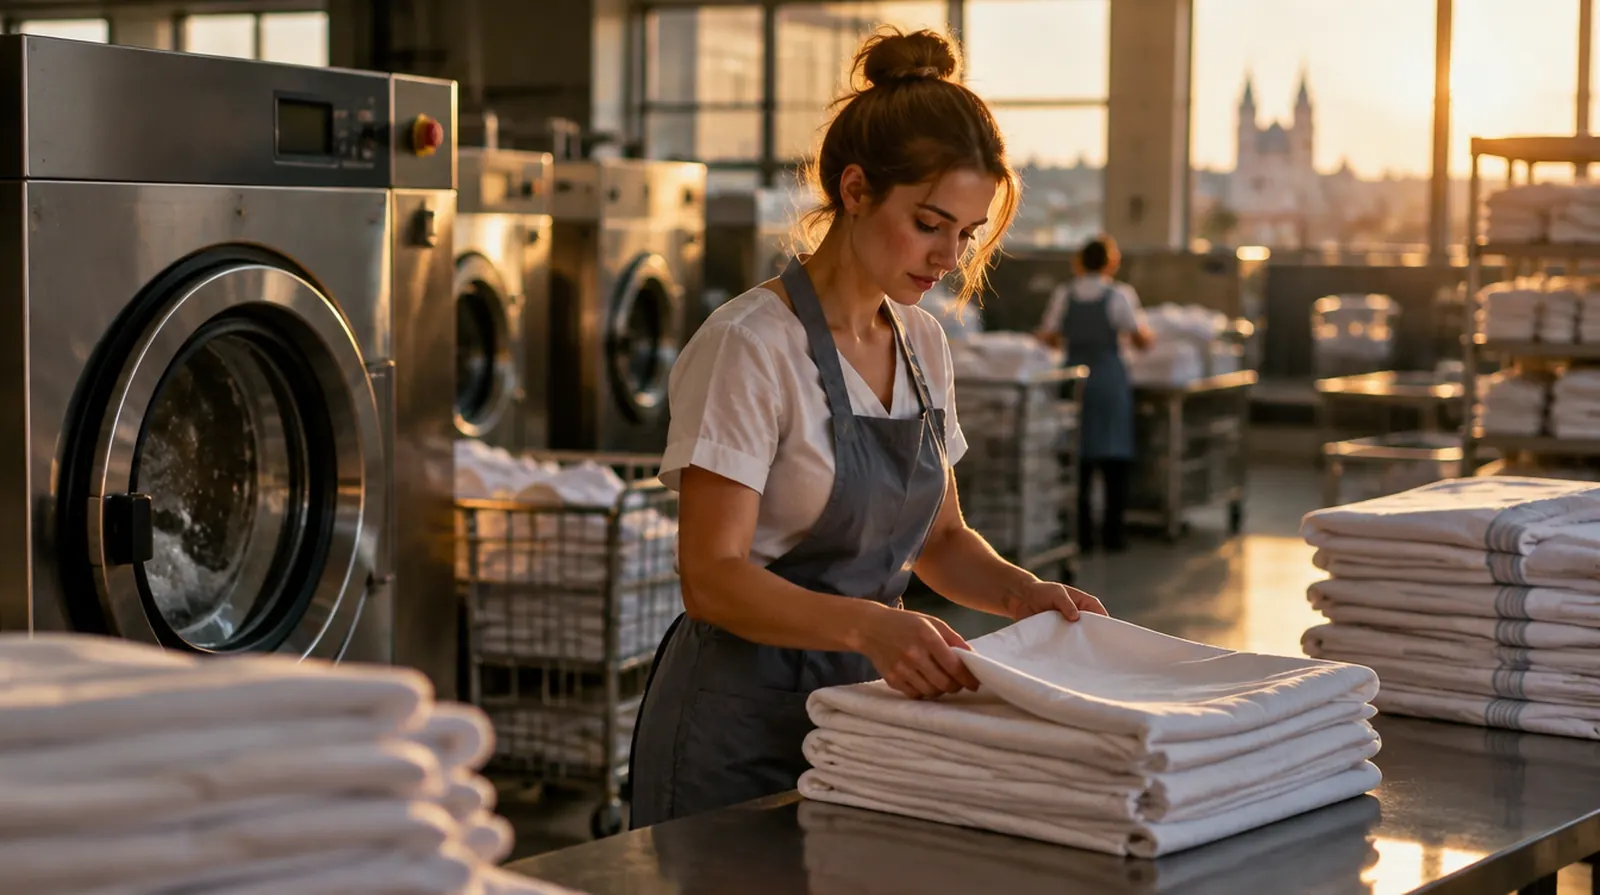
Every day your rails hold valuables that are not yours: suits, wedding dresses, furs, hotel linen. One wrong programme, a mix up at the counter or a dryer fire, and you owe your customers. Add solvents that can contaminate soil and groundwater. This page shows what you should cover and what it costs.
Does my insurance pay if a garment is ruined during cleaning?
Only if damage to customers' items you treat is expressly written into your public liability policy, because items you work on are excluded in basic tariffs. The insurer then pays the current value, provided you made a mistake. If the care label was wrong or the fabric already damaged, you are often not liable. Clauses that limit your liability very heavily do not always stand up in court.
What goes wrong in this trade
01
Shrunk, discoloured, torn
A cashmere coat on the wrong programme, sequins come off, a lining runs. Damage to items you treat is the daily argument at the counter.
02
Mixed up or gone
A suit is handed to the wrong customer or never turns up again. That is damage to property in your custody, which many policies only cover if agreed separately.
03
Fire in the dryer
Lint and oily towels from beauty salons can ignite by themselves. Dryer fires are among the most common major losses in laundries.
04
Solvents in the ground
Older dry cleaning machines used perchloroethylene. If solvent gets into the soil or groundwater, the clean up becomes very expensive.
05
Machines at a standstill
If the big washer extractor or the ironer breaks down, the hotel linen piles up. Contract penalties and lost customers follow.
06
Heat, steam and chemicals
Burns on the ironer and press, skin problems from cleaning agents, heavy lifting: the work is physically demanding.
For disputes with customers over compensation, with landlords and with machine suppliers.
What it costs: example prices
The premium depends heavily on the business: a drop off shop with a small cleaning unit pays little, a commercial laundry with hotel clients considerably more. Machine values, turnover and the value of customers' items on the premises are the main factors.
Insurance
Example
Typical range
Business liability
Dry cleaner with counter, one to three employees, including damage to treated items
about 250 to 600 euros a year
Business liability
Commercial laundry with 15 employees and hotel clients
about 1,200 to 3,500 euros a year
Business contents
Fittings and customers' items worth 60,000 euros
about 250 to 600 euros a year
Machinery breakdown
Cleaning and washing machines worth 120,000 euros
about 600 to 1,500 euros a year
Business interruption
Loss of income for up to twelve months after fire or machinery breakdown
about 200 to 700 euros a year on top
For comparison: Public liability and contents cover for a small dry cleaner cost roughly as much per year as cleaning forty men's suits.
Guide figures from our own quoting experience, excluding German insurance premium tax,
as of September 2026.
Comparison sites rarely give fixed premiums for dry cleaners, because turnover,
Six things that really happen at laundries and dry cleaners, all on one single Tuesday. Tap through the day and see who pays.
Damage so far€176,000
A customer collects her wedding dress. The beadwork has come loose during cleaning and the fabric is stained.
€2,400 · Paid by: Business liability
A made to measure suit has vanished, apparently handed to another customer. The owner wants it replaced.
€1,600 · Paid by: Business liability
Solvent leaks from a faulty pipe on the cleaning machine and seeps into the soil of the neighbouring property. Expert report and clean up.
€65,000 · Paid by: Business liability
The control unit of the large ironer burns out. The machine is down for two weeks and the hotel linen has to be sent elsewhere.
€14,000 · Paid by: Machinery breakdown
Because of the breakdown a hotel client leaves, and the income is missing for months.
€18,000 · Paid by: Business interruption
Oily towels ignite in the dryer. Shop, fittings and the customers' items on the rails are covered in soot.
€75,000 · Paid by: Business contents
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €176,000
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Have damage to customers' items you treat expressly included and agree a limit that matches your most expensive pieces.
Check that lost and mixed up customer items are covered too, not only damaged ones.
Include other people's property in the contents policy, otherwise the customers' items are exactly what is missing after a fire.
Include environmental liability and environmental damage cover if you work with solvents now or did in the past.
Never put towels from beauty and massage businesses away without cooling them, and record the cool down cycle; it lowers the fire risk and helps with the claim.
For delicate items, warn customers in writing about the risks before you accept them, for example when the care label is missing.
Why NAMMERT for your business
We read the exclusions for customers' items
Whether damage to treated items and items in your custody is covered decides every second argument at your counter. As a broker we compare exactly these clauses across several insurers.
We know claims handling from our own work
In boat insurance we handle claims ourselves. After a dryer fire with other people's items on the premises, we know which lists and records the insurer needs.
Machines, shop and vehicles together
Liability, contents, machinery, business interruption and delivery vans are coordinated by us, so there are no gaps between the policies.
A family business since 1989
Our advice costs you nothing; the insurer pays our commission. You have fixed contacts who know your business.
Frequently asked questions
Questions and answers
Does a dry cleaner have to be insured in Germany?
There is no legal obligation.
Without public liability that covers damage to treated items, though,
you pay for every damaged customer item yourself.
How much do I have to pay for a damaged garment?
Usually the current value, not the price new.
A five year old coat is worth considerably less than when it was bought.
Very strong limits on liability in your terms and conditions are often invalid.
What does insurance for a dry cleaner cost?
For a small dry cleaner with a counter,
liability and contents together are usually between 500 and 1,100 euros a year.
With machinery insurance and business interruption, correspondingly more.
Are customers' items insured in a fire?
Only if other people's property is included in your contents policy.
Public liability usually does not pay after a fire, because you are not liable without fault.
Which statutory accident insurer is responsible?
For laundries and dry cleaners it is BG ETEM.
It will get in touch as soon as you register your first employees.
Does the insurance also cover the delivery service?
Damage at the customer's premises and during loading and unloading belongs in public liability,
the vehicle itself in motor insurance.
Linen in transit is often only covered with a goods in transit clause.
NAMMERT insurance broker
Request quotes for Laundry
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.