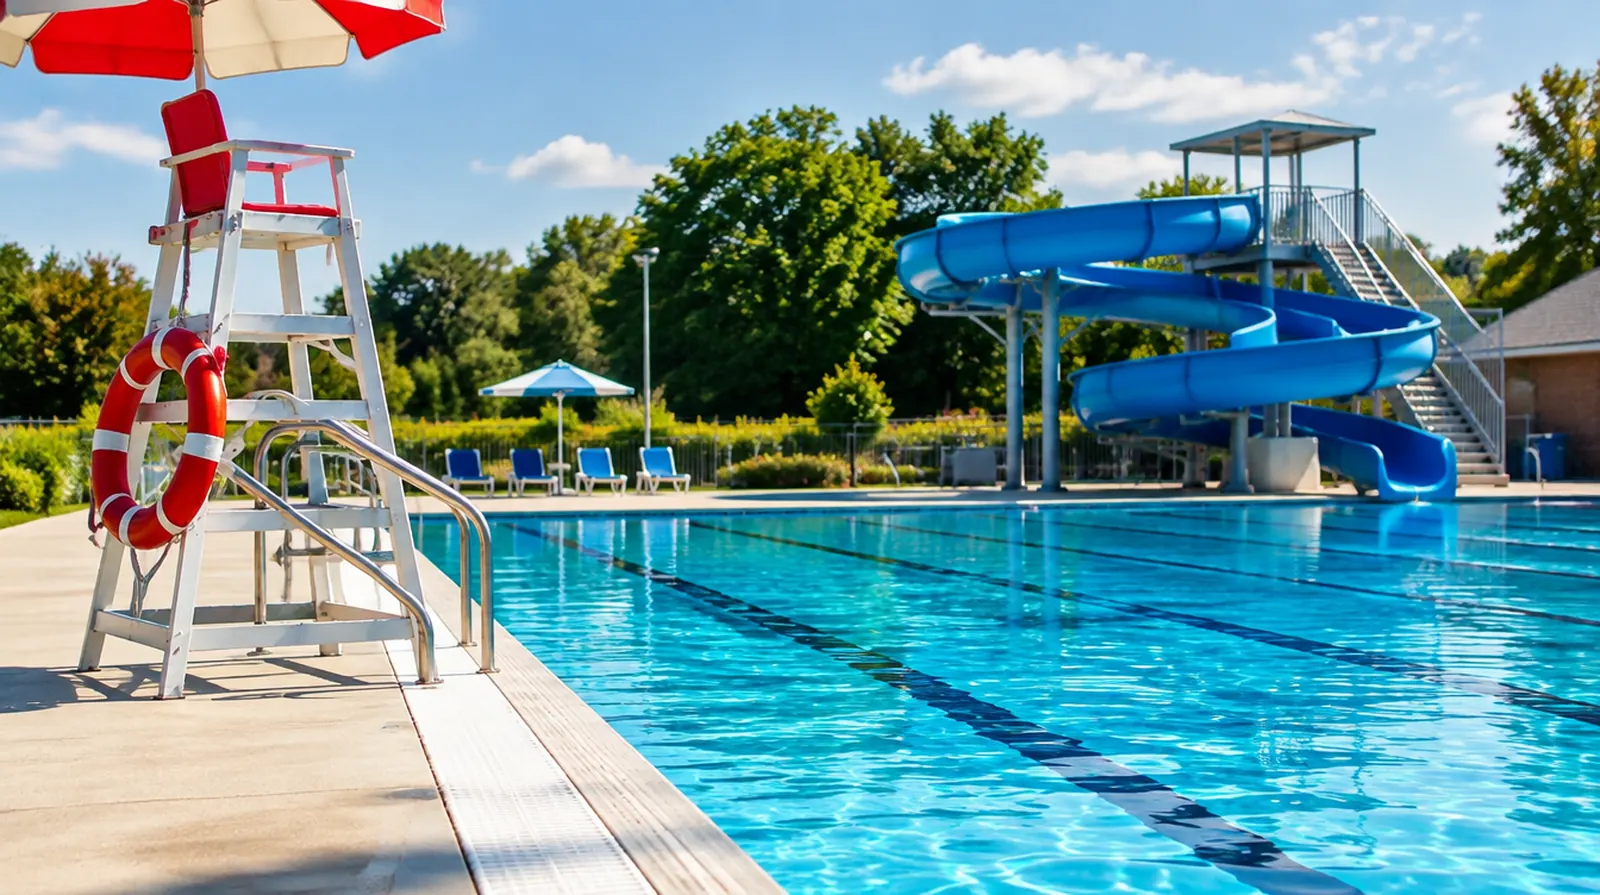
Running a swimming pool means giving people access to water, and the duty of supervision grows with every metre of poolside. A child drifting unnoticed into the deep end, or a dive from the tower that goes wrong, can threaten the whole operation. On top of that come chlorine storage, filter plants and a season in which every lost day eats into turnover.
Are we automatically liable if something happens in the pool?
Not automatically, but quickly. Parents and adult guests carry a share of their own responsibility, but as soon as supervision, signage or water quality fell short, the operator's duty of care applies. After a drowning incident or a fall from the slide, the sums involved are ones a single pool could never carry on its own. Public liability insurance investigates the claim, pays justified ones and defends against unjustified ones.
What goes wrong in this trade
01
Drowning and near drowning
A single unwatched moment at the non-swimmers' pool or in the toddlers' area can turn life threatening within minutes. This is the most serious risk in running a pool.
02
Falls from the diving tower and slide
A dive into water that is too shallow, a collision at the bottom of the slide, a slip on wet tiles: spinal and head injuries are not unusual here.
03
Water treatment and chlorine
Chlorine gas or chemical incidents in the plant room endanger staff and sometimes guests, and can bring the whole operation to a halt along with regulatory action.
04
Filter and pump failure
If water treatment fails, the pool must close until the readings are right again. Spare parts for older plants often take a long time to arrive.
05
Weather at outdoor pools
Hail and storms hit pools, sunbathing lawns and outdoor plant directly, and a wet summer also hurts turnover.
06
Staff in and around the water
Lifeguards work under a heavy duty of supervision themselves, perform rescues under time pressure and are exposed to accidents and psychological strain in the process.
07
Hygiene and water quality
Contaminated water or an outbreak of infection among guests can lead to closure by the health authority and raise questions of liability.
Covers injuries to guests from drowning, falls and slide accidents; given the risk of lasting harm the sum insured should be well above standard levels.
For online booking of lanes and courses and member data, which can be down for days after an attack.
What it costs: example prices
Premiums vary sharply between a small club-run pool with one basin and a leisure pool with several slides and a diving tower. Visitor numbers, staffing and turnover drive the rating, and differences of several hundred per cent between quotes are common.
Insurance
Example
Typical range
Business liability
small outdoor or club pool with one basin, volunteer supervision
about 60 to 200 euros a year
Business liability
municipal indoor pool with employed pool staff, several basins
about 800 to 2,500 euros a year
Business liability
leisure pool with slides and diving tower, high visitor numbers
usually from about 3,000 euros a year, on request only
Machinery breakdown
filter and chlorination plant with a replacement value of 150,000 euros
about 800 to 2,000 euros a year
Business interruption
outdoor pool with 200,000 euros business interruption cover, 12 month indemnity period
from about 700 euros a year
For comparison: Public liability for a small club-run pool costs about as much a year as 30 to 100 day tickets for guests.
Guide figures excluding insurance tax, as of September 2026.
The figures for small pools come from a published comparison for small businesses in Germany;
the others are cautious guide figures from our own quoting experience.
Six things that really happen at pools, all on a single day in the school holidays. Tap through the day and see who pays.
Damage so far€275,000
A child drifts unnoticed into the deep end and is rescued just in time. Resuscitation, intensive care and lasting after-effects.
€180,000 · Paid by: Business liability
The chlorine dosing unit fails and replacement parts have to be sourced by express delivery.
€18,000 · Paid by: Machinery breakdown
Because of the faulty plant the pool stays closed for ten days during the summer holidays.
€35,000 · Paid by: Business interruption
A teenager collides with another guest at the bottom of the slide and breaks a leg.
€12,000 · Paid by: Business liability
A hailstorm damages the pool surround and the plant room container.
€22,000 · Paid by: Commercial buildings
The online booking system for lane bookings is hacked and customer data is affected.
€8,000 · Paid by: Cyber insurance
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €275,000
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Choose at least 10 million euros of cover for bodily injury, since after-effects from drowning or head injuries can run for decades.
Have the duty of supervision and the staffing level for each basin described expressly in the policy, otherwise a claim can turn into a dispute over whether it was met.
Have the chlorine store expressly included in both building and liability cover, it is one of the biggest single risks in running a pool.
Keep thorough records of water samples, maintenance logs and rescue drills: after a claim this is your most important evidence that you met your duty of care.
Set the indemnity period for business interruption to at least 12 months if spare parts for the filter plant have long delivery times.
Check whether seasonal staff and volunteer supervisors are covered through group accident insurance; the statutory accident insurer only covers accidents at work.
Why NAMMERT for your business
Injury claims are part of our daily work
In boat insurance we handle claims ourselves, including injuries and drowning incidents on the water. We know how assessors, lawyers and insurers negotiate after a serious accident.
We get several quotes
Many insurers shy away from drowning risk. As a broker we know the insurers who accept pool operations, and we compare exclusions, not just price.
Season first
We handle policy changes before the outdoor season starts, so new slides or plant are covered before the first guest arrives.
Family business since 1989
Many club and municipal pools are run for years by the same people. So are we, and we remain the same contacts over the years.
Frequently asked questions
Questions and answers
Does a swimming pool need compulsory insurance?
There is no nationwide legal requirement,
but municipalities, clubs and operators almost always require public liability cover with a high
sum insured internally, because a single serious accident can exceed all of a pool's equity.
Is the pool liable if parents were not watching?
Parents' own responsibility does not automatically release the operator.
As soon as a failure in supervision, signage or water quality can be shown,
the pool's duty of care applies regardless of what the parents did or failed to do.
What does insurance for a small outdoor pool cost?
Public liability for a small club-run pool is often between 60 and 200 euros a year.
A municipal indoor pool with staff and several basins usually pays 800 to 2,500 euros.
Are lifeguards covered at the pool?
Employed lifeguards are covered through public liability and the statutory accident insurer.
Volunteer supervisors need extra cover, for example through group accident insurance.
Does insurance pay after a chlorine incident?
Bodily injury and property damage from a chemical incident are covered by public liability
insurance, provided the chlorine store is expressly included.
Damage to the plant itself belongs under machinery breakdown cover.
Do I need to keep insuring the outdoor pool over winter?
Yes, the building, basins and plant need protection against frost,
storm and burglary even outside the season, even when there is no bathing operation.
NAMMERT insurance broker
Request quotes for Swimming pool
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.