Natural hazard cover
In the vineyard this role is taken by hail and frost insurance, which replaces losses in yield and quality for the vintage.
Insurance broker / Business types / Farming and nature
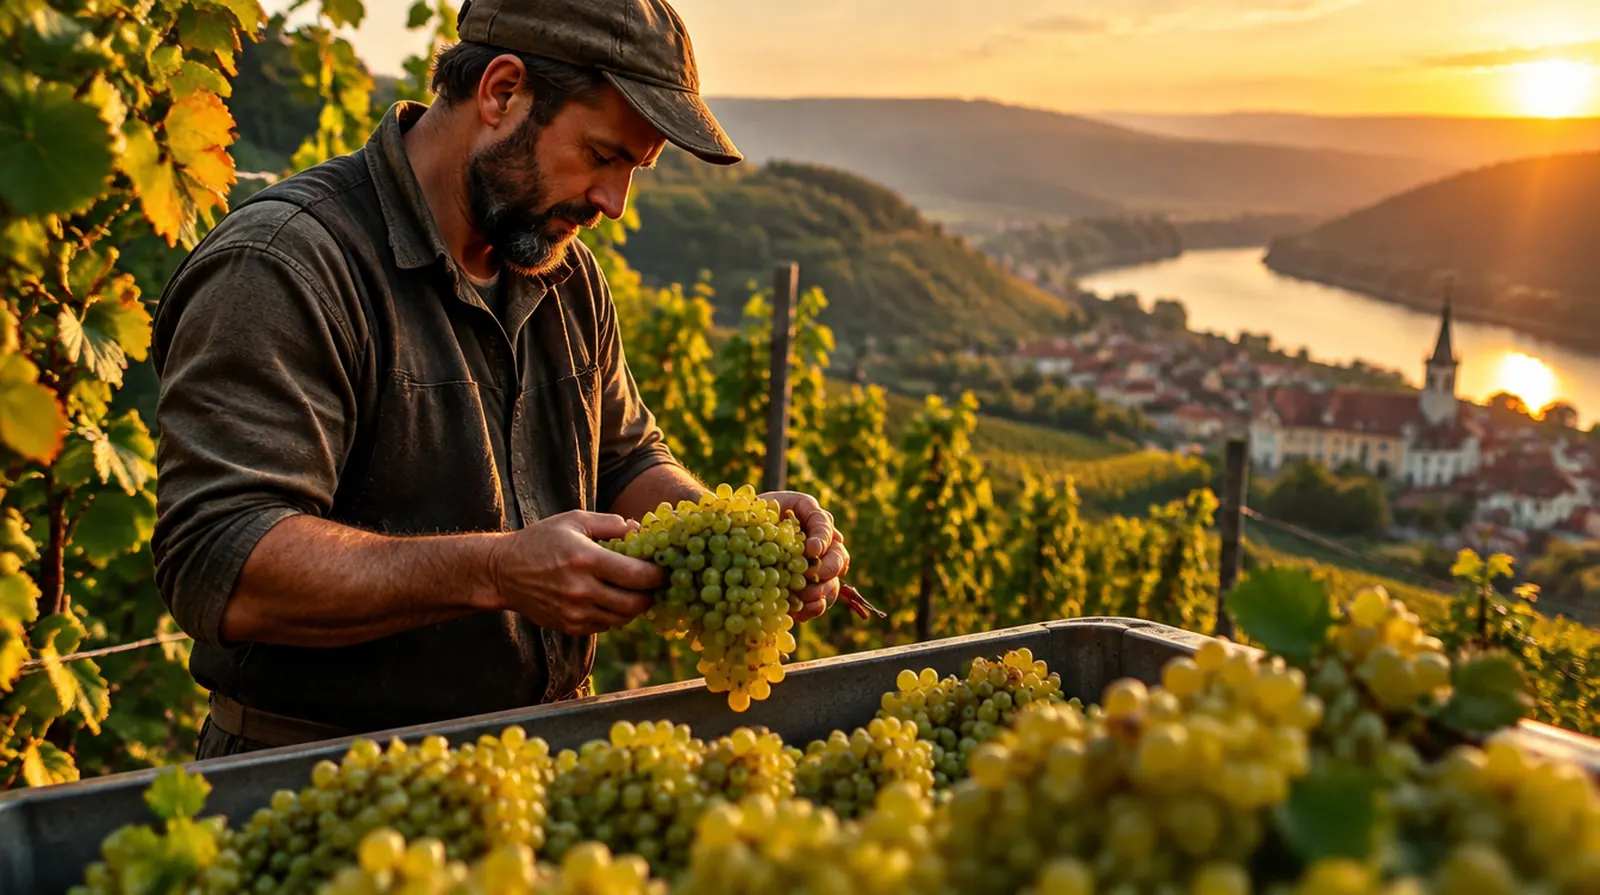
One frosty night in April or ten minutes of hail in July, and the vintage is lost. Meanwhile the cellar holds the wine of recent years in tanks, barrels and bottles, often worth more than the building. This page shows how winegrowers in Germany protect vines, cellar and sales, and where the federal state helps with the premium.
The question almost everyone asks first
In winegrowing, frost is now a bigger risk than hail, and hail insurance on its own does not pay for frost. Combined hail and frost insurance costs more, but Rhineland-Palatinate and other federal states subsidise it with up to 50 percent of the premium. For sites in hollows or with early budburst it almost always pays off. We compare the quotes and keep an eye on the subsidy deadline.
After budburst, one night below minus two degrees is enough to freeze the young shoots. Whole sites are lost for the vintage.
Hail damages grapes and wood, the yield drops and the fruit rots. Often the following vintage is affected too.
An open valve, a cracked tank, a forklift against a pallet of bottles: vintages are stored in a small space and are expensive.
Drift onto housing, gardens or neighbours' organic vineyards leads to complaints and claims for damages.
Wine tastings, a seasonal wine tavern (Straußwirtschaft), a harvest festival: falls on stairs and in the cellar are classic liability cases.
Rollovers with narrow track tractors and winch accidents are among the most serious accidents in winegrowing.
Compared with other trades, 1 low to 5 high.
Essential
In the vineyard this role is taken by hail and frost insurance, which replaces losses in yield and quality for the vintage.
Covers product liability for wine and sparkling wine, spray drift, guests at tastings and in the wine tavern, and environmental damage.
Insures wine stocks, tanks, barrels and cellar equipment against fire and burglary and, with an extension, against wine running out.
Compulsory for narrow track tractors, grape harvesters and delivery vehicles on public roads.
Strongly advised
Press house, cellar, tasting room and farmhouse against fire, storm and hail at index linked new value.
For grape harvester, press, cooling and narrow track tractor against breakdown and accidents in the vineyard.
Depends on the business
Secures running costs if the press house or tasting room is out of action after a fire during harvest.
Adds to the SVLFG for family and seasonal workers who work on steep slopes.
In winegrowing, crop insurance is priced per hectare and site, while cellar and liability depend on stock and turnover. An estate with a tasting room and wine tavern also needs the building blocks of hospitality.
| Insurance | Example | Typical range |
|---|---|---|
| Natural hazard cover | Hail insurance for vineyards, per hectare | around €60 to €120 a year |
| Natural hazard cover | Combined hail and frost insurance, per hectare, before subsidy | around €200 to €500 a year |
| Business liability | Wine estate with 10 hectares, direct sales and tastings | around €200 to €600 a year |
| Business contents | Wine stock and cellar equipment worth €400,000, including tank rupture | around €700 to €1,800 a year |
| Machinery breakdown | Grape harvester with a new value of €250,000 | around €1,200 to €3,000 a year |
For comparison: Hail insurance for one hectare of vines costs about as much a year as ten to twenty bottles of estate wine bought at the cellar door.
Guide figures excluding German insurance tax, as of September 2026. The hail range comes from published market examples; frost, cellar and machinery are guide figures from our own quoting. Rhineland-Palatinate subsidises combined hail and frost insurance with 50 percent of the premium up to a maximum per hectare. We obtain the exact quote.
01
For: Small winegrowers delivering grapes to a cooperative or winery
Together around €500 to €1,500 a year for 3 hectares
Request this package02
For: Estates bottling and selling their own wine, with cellar, tasting room and 10 to 20 hectares
Together around €4,000 to €12,000 a year, less subsidy
Request this package03
For: Estates with a wine tavern, harvest festivals and seasonal workers
Together around €7,000 to €18,000 a year, less subsidy
Request this packageSix things that really happen to winegrowers, squeezed into one single day between budburst and harvest. Tap through and see who pays.
After a frosty night the young shoots in the valley site have frozen. 4 hectares are largely lost for the vintage.
During pumping over, a valve is left open. 6,000 litres of Riesling run into the cellar drain.
The sprayer catches the washing and garden pond in the new housing estate below.
A guest at a tasting falls down the cellar stairs and breaks an arm.
The afternoon hailstorm smashes grapes on 6 hectares just before harvest.
The grape harvester tips over on the slope, and hydraulics and cab are badly damaged.
Which package would you have had?
Illustrative amounts before any excess. Whether and how much is paid depends on the policy terms.
Which site is worth insuring depends on budburst, hollows and grape variety. As a broker we obtain quotes from several insurers and factor in the subsidy.
In boat insurance we settle claims ourselves. We know how to prove quantities and values properly after a tank rupture.
We look after harvest, buildings, guests, vehicles and your private cover with one contact, and can do it in English.
Wine estates are often family affairs, and so are we. Our work is free for you; the insurer pays our commission.
Questions and answers
According to published market examples, around €60 to €120 per hectare a year. With frost it becomes considerably more expensive, but several federal states offer a subsidy.
Yes, for example in Rhineland-Palatinate with 50 percent of the premium up to a maximum per hectare, if hail and frost are insured in one policy. Bavaria and other states also offer subsidies.
Only with an extension for escaping liquids or tank rupture. Burst pipe cover does not include it.
It must be included in your general liability. An extension to the farm policy is often enough; for larger hospitality you need a separate block.
At work they are covered by the SVLFG accident insurance as soon as they work for you. Register seasonal workers correctly.
Breakage in shipping is paid by transport insurance or by the parcel service within its liability. If someone is injured by a bursting bottle, product liability pays.
NAMMERT insurance broker
The recommended covers are already ticked. Change what does not fit; we obtain quotes and come back with a comparison. You can write in English.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.
Is the beer covered if a fermentation tank cracks?
Is hail or multi peril crop insurance worth it for my farm?
Are my plants covered if the heating fails in winter?
This page covers the following classes of the German WZ 2025 (identical to NACE at four digits):
Source: Federal Statistical Office of Germany (Destatis), WZ 2025. All business types
Boat or yacht? Here we are not the broker but the underwriting agency, with our own policies and our own claims handling.
Boat insuranceNAMMERT Assekuradeur GmbH, insurance broker licensed under section 34d(1) of the German Trade Regulation Act, broker register no. D-C08Q-TOSD4-37. For boat and yacht insurance we act as underwriting agency, not as broker. Statutory disclosure (German) · Updated