Business liability
Covers injury and property damage to customers and third parties, with environmental liability (Umwelthaftpflicht) and an environmental damage extension for soil and water.
Insurance broker / Business types / Energy and environment
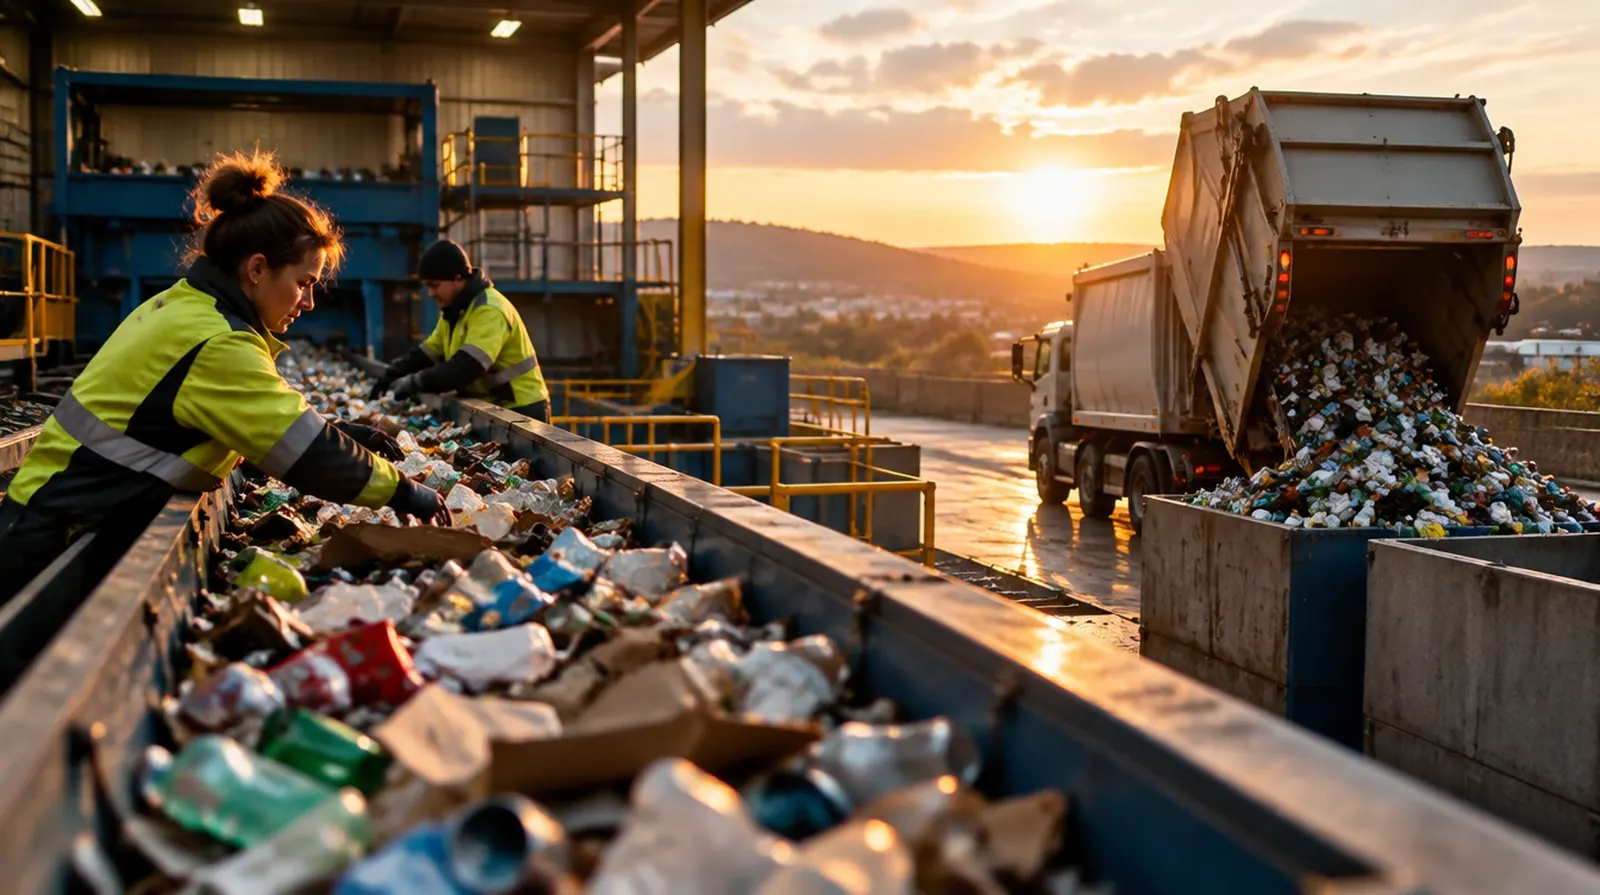
Few trades carry a fire risk as high as recycling: a single lithium battery in a packaging waste bag is enough to set the sorting hall ablaze. Add lorries driving through narrow residential streets every day, substances that threaten soil and water, and plant without which the whole business stops. Many insurers now only cover the trade under strict conditions.
The question almost everyone asks first
Because fires at recycling businesses have risen sharply in recent years, mostly caused by lithium batteries thrown away in the wrong bin. Many insurers now only offer cover with conditions: fire compartments, fire detection with thermal imaging cameras, limited storage volumes, space between piles. If you already have this technology and can document it, you get much better offers.
Lithium batteries in electronic scrap and packaging waste catch fire when pressed or shredded. Within minutes a spark becomes a fire across the whole hall.
Oil from a lorry, contaminated firefighting water, leachate from a store: damage to soil and groundwater leads to expensive clean-up orders.
Refuse lorries and skip loaders reverse every day between parked cars, cyclists and children on their way to school.
Shredders, balers, screens and sorting lines wear hard. If the central plant fails, waste piles up in the yard.
Jumping onto the vehicle, working at running conveyors, needlestick injuries from syringes in the waste: the trade has a high accident risk.
Skips damage paving and driveways, a chain snaps during collection, a customer demands compensation for recyclables that were disposed of wrongly.
Compared with other trades, 1 low to 5 high.
Essential
Covers injury and property damage to customers and third parties, with environmental liability (Umwelthaftpflicht) and an environmental damage extension for soil and water.
Insures refuse lorries, skip loaders, hook loaders and vans in one fleet policy with liability and own damage cover.
Strongly advised
Protects halls and stores against fire, storm and escape of water; for recycling only available with an agreed fire protection plan.
Pays for damage to shredders, balers, sorting plants, wheel loaders and pumps caused by breakage, operating errors and short circuits.
Pays running costs and the extra cost of sending waste to other plants while your own plant is out of action after a loss.
As goods in transit liability it covers damage to goods and recyclables you carry for others; usually compulsory for commercial haulage over 3.5 tonnes.
Depends on the business
For stock, sorted recyclables, containers and workshop equipment.
For route planning, weighbridge systems and plant control, whose failure brings operations to a halt.
Premiums in waste management are well above the average for business insurance. What counts is the types of waste, storage volumes, fire protection, the number and age of vehicles and your claims history. For recycling halls with combustible material there are often only a few offers.
| Insurance | Example | Typical range |
|---|---|---|
| Business liability | Skip hire firm with five vehicles, environmental liability and environmental damage extension | about 1,500 to 4,000 euros a year |
| Fleet insurance | Fleet of eight lorries and skip loaders, liability and partial own damage cover | about 12,000 to 25,000 euros a year |
| Commercial buildings | Sorting hall with a rebuild value of 1.5 million euros and fire protection technology | about 6,000 to 18,000 euros a year |
| Machinery breakdown | Shredder and sorting plant with a replacement value of 800,000 euros | about 5,000 to 12,000 euros a year |
| Cyber insurance | Waste company with around 7 million euros turnover, 1 million euros cover | about 1,800 to 3,500 euros a year |
For comparison: Public liability for a small skip hire firm costs about as much a year as five to ten skips of building rubble, delivered and disposed of.
Cautious guide prices excluding insurance premium tax, as of September 2026, from the quotes we see in practice and published examples for comparable businesses. Very few premiums for waste companies are published; recycling halls are almost only insured after a site survey.
01
For: Skip hire firm or small waste company with a few vehicles
Together about 8,000 to 20,000 euros a year
Request this package02
For: Waste company with its own recycling yard, hall and wheel loader
Together about 25,000 to 60,000 euros a year
Request this package03
For: Recycling or sorting plant with several sites and networked controls
Together calculated individually, usually six figures a year
Request this packageSix things that really happen to waste and recycling companies, all on a single day. Click through the day and see who pays.
Reversing down a narrow street, the refuse lorry clips three parked cars and a garden wall.
A skip loader damages the natural stone paving of a driveway while setting down a skip.
The shredder's rotor breaks, and spare parts will take six weeks to arrive.
While the shredder is down, the waste has to be driven to more expensive external plants.
Oil from a leaking hydraulic hose runs into the storm drain, and the authority orders a clean-up.
A battery in the packaging waste store ignites, and despite the fire suppression system part of the hall burns out.
Which package would you have had?
Illustrative amounts before any excess. Whether and how much is paid depends on the policy terms.
Only a few insurers still cover recycling businesses. As a broker we know who does, and we prepare your documents so that a request has a real chance.
In boat insurance we handle claims ourselves, up to total losses after fire. That experience helps when rebuilding and loss of revenue are negotiated after a hall fire.
We align fleet, goods in transit, environmental liability and property cover so that no loss falls between two policies.
Many waste companies are family firms in their second or third generation. So are we. The insurer pays for our work, so it is free for you.
Questions and answers
Motor liability for every vehicle. If you carry waste for others in lorries over 3.5 tonnes, you usually need goods in transit liability under § 7a GüKG. For landfills, the Circular Economy Act requires a financial security.
Yes, fire is covered by buildings and contents insurance whatever the cause. But the insurer checks whether the agreed fire protection conditions were met; if not, it can reduce the payment.
Only with an environmental damage extension. Environmental liability pays for damage that third parties suffer through pollution. The environmental damage extension pays for the clean-up of soil, water and biodiversity that the authority orders, even when no third party was harmed.
Because fire losses in the trade have piled up and many insurers have pulled out. If you invest in early fire detection, you can lower your premium noticeably.
Only if extra costs are agreed in your business interruption cover. Every waste plant should have this, because your duty to accept waste continues.
Yes, through the statutory accident insurer, usually BG Verkehr in waste management. Group accident insurance can top up the statutory benefits for serious cases.
NAMMERT insurance broker
The recommended covers are already ticked. Change what does not fit; we obtain quotes and come back with a comparison. You can write in English.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.
Do I need goods in transit liability even with just one lorry?
Will my liability policy pay if the neighbour's gable wall cracks during demolition?
Are our excavators and wheel loaders protected by motor insurance?
This page covers the following classes of the German WZ 2025 (identical to NACE at four digits):
Source: Federal Statistical Office of Germany (Destatis), WZ 2025. All business types
Boat or yacht? Here we are not the broker but the underwriting agency, with our own policies and our own claims handling.
Boat insuranceNAMMERT Assekuradeur GmbH, insurance broker licensed under section 34d(1) of the German Trade Regulation Act, broker register no. D-C08Q-TOSD4-37. For boat and yacht insurance we act as underwriting agency, not as broker. Statutory disclosure (German) · Updated