Insurance for gravel works, sand pits, quarries and open-pit mining in Germany
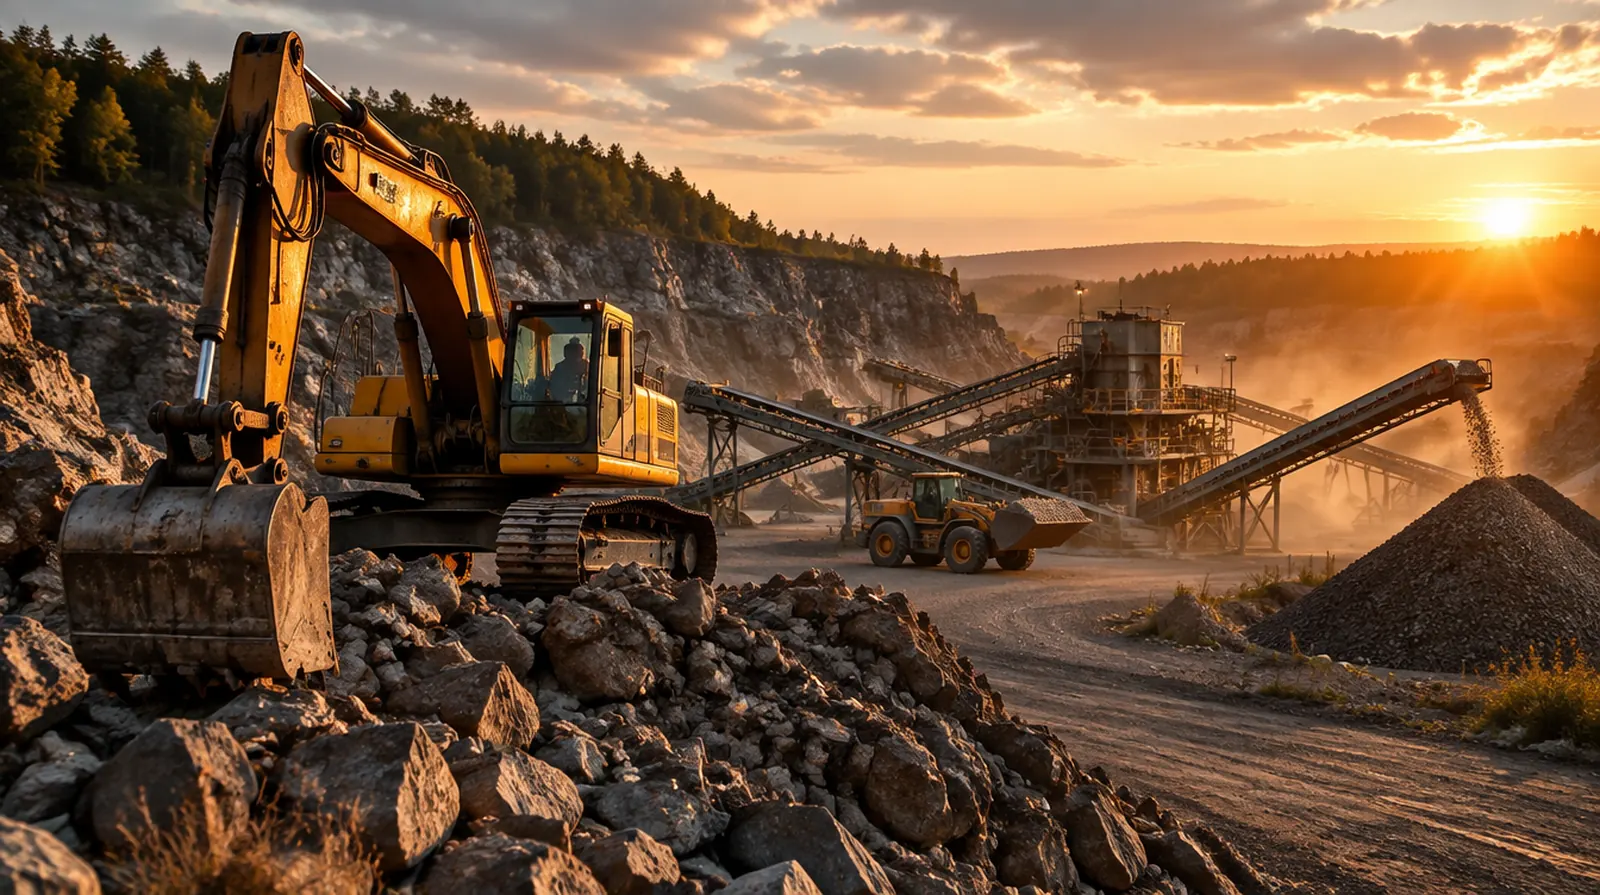
In a quarry or gravel pit, machines worth more than a family home work in dust, in water and on slopes. Blasting shakes the houses next door, a conveyor belt catches fire, a dump truck slides down the embankment. And when the crusher stops, the whole works stops, while customers on building sites wait for their material.
Are our excavators and wheel loaders protected by motor insurance?
Only in part. Registered vehicles and fast machines have motor liability, often with own damage cover. Slow machines that only move on site, and all fixed plant such as crushers, screens and conveyors, belong in machinery insurance. It also pays for operating errors, material breakage and short circuits, which own damage motor cover does not.
What goes wrong in this trade
01
Blasting
Flying rock hits a car at the gate, vibrations cause cracks in a neighbour's house. Without measurement records it is almost impossible to prove the cracks were already there.
02
Machinery breakdown
Crusher shafts, screen decks, hydraulics and engines run under constant load in the dust. A major crusher failure easily costs six figures.
03
Slopes and water
Embankments slip after heavy rain, a dump truck tips over at the working face, a floating dredger springs a leak: terrain and water are part of the risk here.
04
Conveyor fires
Friction heat on belts and drums, oil in the engine bay of a wheel loader: fires in plant and vehicles often break out at night.
05
Environment
Diesel spilt while refuelling, hydraulic oil in the gravel pit lake, silt in a stream: with wet extraction and groundwater, every drop of oil becomes environmental damage.
06
Theft on open sites
Diesel from tanks, GPS kit from excavator cabs, copper from plant: remote pits are an easy target at night.
Covers damage to neighbours, customers and lorry drivers on your site, including blasting damage, environmental liability (Umwelthaftpflicht) and an environmental damage extension.
Pays for damage to crushers, screens, conveyors, excavators, wheel loaders and floating equipment caused by breakage, operating errors, fire and theft.
Tops up the statutory accident insurer's benefits for staff in a trade with a high accident risk.
What it costs: example prices
Premiums depend mainly on the value of the machinery, whether you blast or extract wet, the neighbourhood and the deductible. Machinery insurance is usually priced per thousand of the replacement value, for older machines often at current value.
Insurance
Example
Typical range
Business liability
Gravel works with wet extraction and ten employees, environmental liability and environmental damage extension
about 2,000 to 5,000 euros a year
Business liability
Quarry with blasting and housing nearby
about 4,000 to 10,000 euros a year
Machinery breakdown
Crushing and screening plant with a replacement value of 1.5 million euros
about 7,500 to 20,000 euros a year
Machinery breakdown
Mobile machines: two wheel loaders and a crawler excavator, 900,000 euros in total
about 5,000 to 12,000 euros a year
Business interruption
Loss of revenue after machinery damage, 12 month indemnity period
about 2,500 to 7,000 euros a year
For comparison: Machinery insurance for a crushing plant costs about as much a year as the gross profit the works loses in one or two days of standstill.
Cautious guide prices excluding insurance premium tax, as of September 2026,
from the quotes we see in practice and published examples for comparable businesses.
Very few premiums for extraction businesses are published;
we calculate from your machinery list and a site visit.
Six things that really happen at gravel works and quarries, all on a single working day. Click through the day and see who pays.
Damage so far€318,500
Overnight, thieves have taken 3,000 litres of diesel from the tank and the GPS control unit from the excavator.
€16,000 · Paid by: Machinery breakdown
After the blast, a resident reports new cracks in the front of his house, and an expert confirms a link.
€28,000 · Paid by: Business liability
The eccentric shaft of the primary crusher breaks, and the plant comes to a standstill.
€140,000 · Paid by: Machinery breakdown
Six weeks without the primary crusher: material has to be bought in to meet supply contracts.
€95,000 · Paid by: Business interruption
While loading, a wheel loader damages the trailer of a customer's lorry.
€7,500 · Paid by: Business liability
A dump truck leaks hydraulic oil on the bank of the gravel pit lake; an oil barrier and soil replacement are ordered.
€32,000 · Paid by: Business liability
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €318,500
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Have blasting damage, vibration and flying rock expressly included in your public liability, with a sum that fits the buildings nearby.
Carry out vibration measurements and a pre-blast condition survey of neighbouring buildings: this decides every crack claim later on.
Name floating dredgers and pontoons expressly in your machinery insurance, otherwise they often slip through the net.
Include the extra cost of buying in material and outside processing in your loss of revenue cover, so you can keep your supply contracts.
Secure tanks and machines against diesel theft; many insurers require lockable fuel caps and lighting.
Check which working machines can go faster than 20 km/h: motor liability is compulsory for them, even if they rarely go on the road.
Why NAMMERT for your business
We know heavy equipment
In boat insurance we handle claims to engines, drives and hydraulics ourselves. We know how loss adjusters assess machinery damage and where the line runs between wear and breakage.
We ask the specialists
Not every insurer covers extraction businesses. As a broker we get quotes from those that really insure blasting, wet extraction and floating equipment.
Everything aligned
We set up liability, machinery, fleet and loss of revenue so that a claim does not get stuck between two policies, for example the wheel loader out on the road.
A family business since 1989
Many gravel works have been in family hands for generations. So have we, with the same people for you to talk to. The insurer pays our commission.
Frequently asked questions
Questions and answers
Which insurance is compulsory for a quarry in Germany?
Motor liability for registered vehicles and working machines faster than 20 km/h.
Mining law (the Federal Mining Act) requires a financial security for restoring the land,
usually as a bank guarantee.
Public liability and machinery insurance are not required by law, but you cannot do without them.
Is blasting damage to a neighbour's house covered?
Only if it is included in your public liability policy.
Many standard policies exclude blasting.
Clear this up before the first blast and record the vibration readings.
What does insurance for a gravel works cost?
A small works pays about 2,000 to 5,000 euros a year for liability with environmental extension.
With machinery, fleet and loss of revenue it quickly comes to 20,000 to 45,000 euros,
depending on the value of the machines.
Does machinery insurance cover wear and tear?
No.
Wear on crusher jaws, screen linings and belts is an operating cost.
What is covered is sudden damage such as breakage, operating errors, short circuits,
fire and theft.
Are floating dredgers covered by machinery insurance?
Only if they are expressly named.
Floating equipment has its own risks such as sinking and springing a leak,
which must be written into the policy.
Who pays if oil runs into the gravel pit lake?
Damage to third parties, for example a fishing tenant, is paid by environmental liability.
Clean-up of water and soil ordered by the authority is only paid by an environmental damage
extension.
NAMMERT insurance broker
Request quotes for Gravel and quarrying
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.