All about this insurance: Car insurance
Can I use my no-claims bonus from abroad in Germany?
Insurance broker / Insurance questions / Car insurance
In short
In Germany hail damage to your own car is paid by partial cover (Teilkasko), which is also part of comprehensive cover. Your deductible is subtracted and your no-claims class stays the same. With liability only, you pay yourself. In 2025 a natural hazard claim on a car averaged about EUR 3,400, while light hail dents can often be fixed for a few hundred euros.
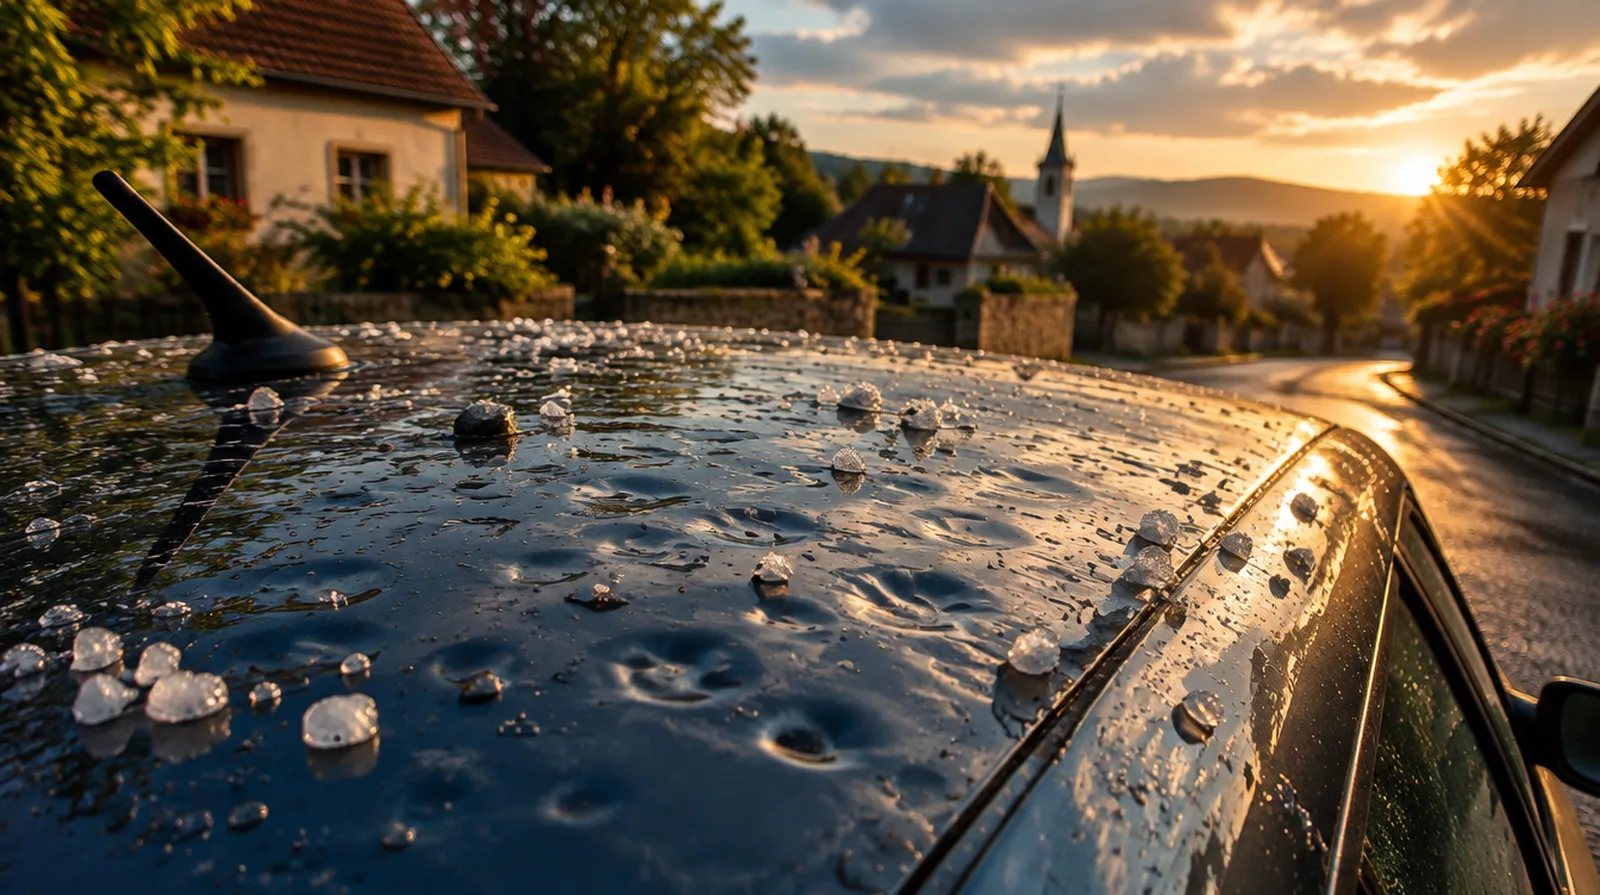
Published figures for natural hazard claims on cars in Germany and guide prices for paintless dent repair.
| Example | Typical range |
|---|---|
| Natural hazard claims on insured cars, 2025 | about 190,000 claims, together about EUR 650 million |
| Average per claim for storm, hail, lightning and flood, 2025 | about EUR 3,400 |
| One small dent up to 2 cm | about EUR 70 |
| Roof with 50 dents up to 3 cm | about EUR 380 to 510 |
| Usual deductible in partial cover | about EUR 150 to 300 |
Figures from published insurance industry statistics and garage prices as of September 2026. The average covers all natural hazards, not only hail. The amounts in the worked example are guide values from our quoting practice.
Worked example
About 60 small dents on roof and bonnet, paint intact. This is how the bill is split with partial cover.
| Paintless dent repair, roof and bonnet | about EUR 1,200 |
| Your deductible | EUR 150 |
| Paid by partial cover if repaired | about EUR 1,050 |
| Cash settlement without VAT | about EUR 860 |
| Effect on no-claims class | none |
With the repair you pay EUR 150. Without partial or comprehensive cover you pay everything. Calculation with guide values.
Hail is a natural event and part of the basic cover of every German partial cover policy, together with storm, lightning and flooding. It pays for dents in panels and roof, cracked glass, broken lights and mirrors, minus your deductible.
Partial cover has no no-claims class, so a hail claim costs you no discount. Liability insurance, the only cover required by law, pays nothing for your own car.
| Hail damage | Liability only | Partial cover | Comprehensive cover |
|---|---|---|---|
| Dents on roof, bonnet and doors | no | yes | yes |
| Cracked windscreen | no | yes | yes |
| Broken lights and mirrors | no | yes | yes |
| Branch falls on the car in the storm | no | yes, as storm damage from wind force 8 | yes |
| Your car then damages another car | yes | yes, via liability | yes, via liability |
If the paint is intact, a specialist pushes the dents out from behind without repainting, known as paintless dent repair. A single small dent costs about EUR 70 to 100. With many dents, prices are per panel or as a package, so a roof with 50 small dents is more likely around EUR 400 to 500 than several thousand.
It gets expensive when the paint cracks or aluminium panels are hit. Then filling, painting or replacing parts is needed, and damage across roof, bonnet and tailgate quickly reaches four figures.
In Germany you may settle on paper: take the money based on an expert report and skip the repair. The insurer then pays the net amount without VAT, minus the deductible. The dents stay and will lower the resale price.
If the repair costs more than the car is worth, it is an economic total loss. This happens with older cars after heavy hail more often than people expect. You then receive the replacement value minus the salvage value and the deductible.
Partial cover pays the current value, not the new price, unless your policy has a new-value rule for young cars. A loss in value because the car now has a hail history is usually not paid.
If you left the sunroof open despite a storm warning and water gets in, the insurer may reduce payment for gross negligence unless your policy waives that defence.
If your car is almost always in a garage and is older with a low value, you can often carry the hail risk yourself. A few dents on an old car do not have to be repaired.
If you park on the street, especially in regions with frequent thunderstorms, or the car is financed or leased, partial cover belongs in the contract. A hail cover sheet helps but does not replace insurance.
Questions and answers
No, as long as partial cover pays. It has no no-claims class, and in comprehensive cover hail runs through the partial cover part.
No. You can take the money without VAT based on an expert report. Leasing and finance contracts usually require the repair.
Report it as soon as possible, many policies mention one week. Waiting long invites disputes about where the dents came from.
Yes, but only above the deductible. If the cost is lower, reporting is not worth it.
Partial cover pays the replacement value minus salvage value and deductible. You can often keep the damaged car.
Against small and medium hailstones, yes. It does not lower your premium and does not replace partial cover.
NAMMERT insurance broker
We compare several insurers and come back with a proposal. Free for you; the insurer pays our fee. You can write in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.
All about this insurance: Car insurance
Can I use my no-claims bonus from abroad in Germany?
What is the difference between Teilkasko and Vollkasko?
Teilkasko (partial cover) pays for damage you did not cause yourself: theft, storm, hail, fire, broken glass and colli …
Does partial cover pay for marten damage to my car in Germany?
Yes. In Germany almost every partial cover policy (Teilkasko) pays for cables, hoses and insulation chewed by a marten …
What does insurance pay for a total loss?
Usually you receive the replacement value minus the salvage value: the price of a comparable used car minus what the w …
Which insurance pays for a stone chip in Germany?
In Germany a stone chip in the glass is paid by partial cover (Teilkasko), which is also part of every comprehensive p …
NAMMERT Assekuradeur GmbH, insurance broker licensed under section 34d(1) of the German Trade Regulation Act, broker register no. D-C08Q-TOSD4-37. For boat and yacht insurance we act as underwriting agency, not as broker. Statutory disclosure (German) · Updated
Was this useful?