All about this insurance: Car insurance
Can I use my no-claims bonus from abroad in Germany?
Insurance broker / Insurance questions / Car insurance
In short
If the driver who hit your car is known, their liability insurance pays the full repair. If they drove off unknown, only your comprehensive cover (Vollkasko) pays, minus your deductible and with a higher premium later. Partial cover (Teilkasko) does not pay for parking damage. If you hit a parked car yourself, a note on the windscreen is not enough.
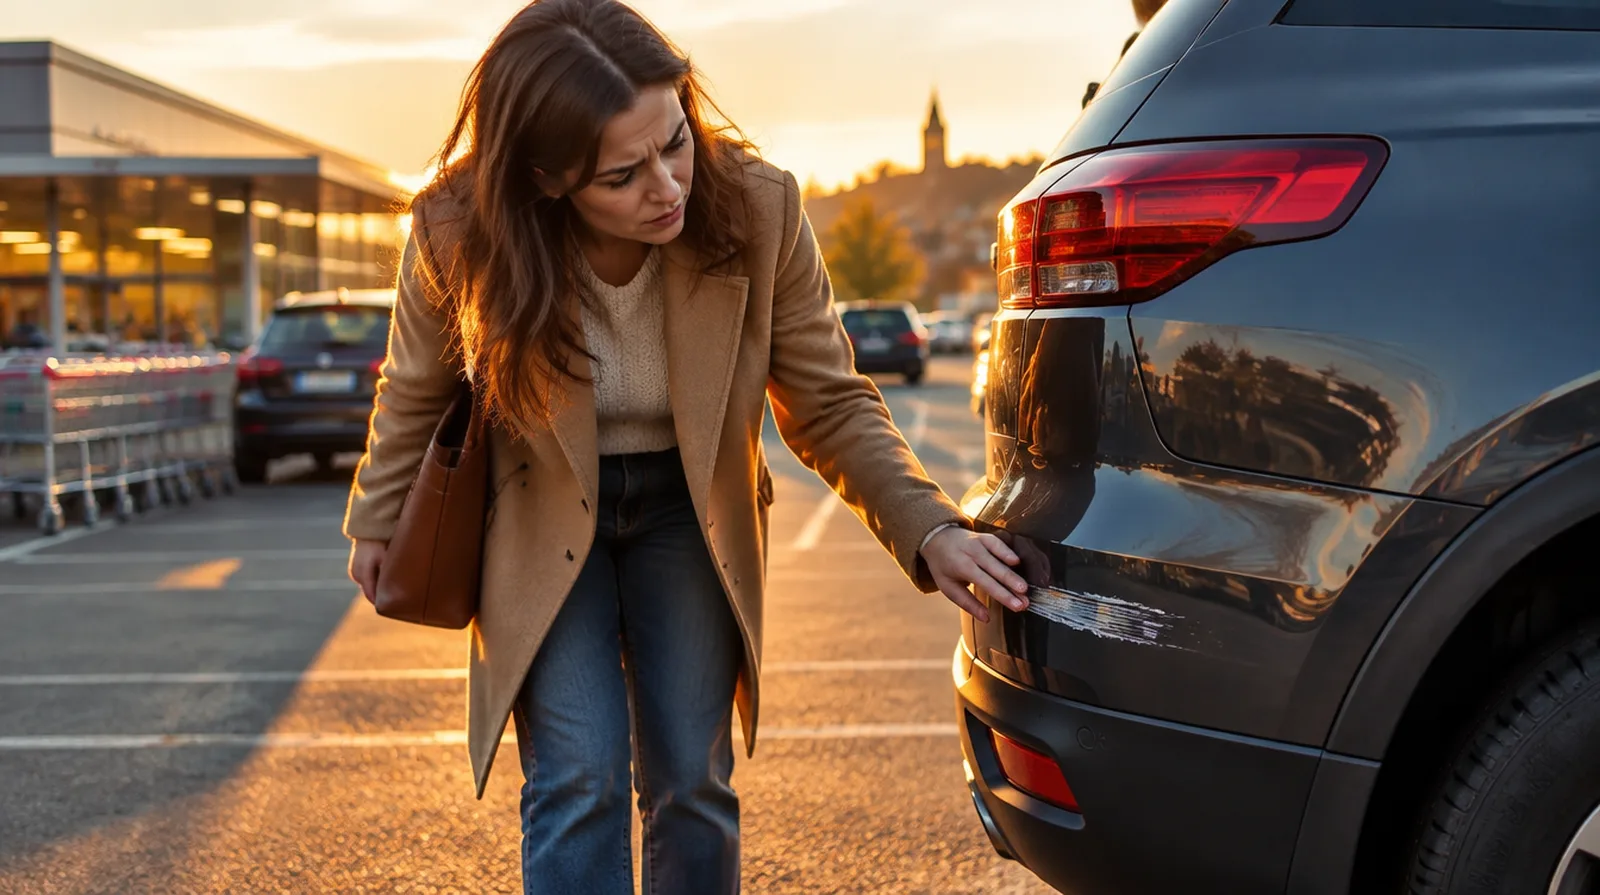
Repair costs for typical parking bumps from a German workshop survey, 2026.
| Example | Typical range |
|---|---|
| Smaller parking damage without electronics | about EUR 1,000 to 2,500 |
| Rear bump, bumper with sensors | about EUR 2,100 to 5,100 |
| Front bump, bumper and headlight, small car | about EUR 3,000 to 3,100 |
| Front bump, bumper and laser headlight, mid-size car | about EUR 7,800 to 8,000 |
Workshop prices from a market survey published in February 2026. The deductible and extra premium after a drop in class in the worked example are guide values from our quoting practice. Your figure depends on the model, the workshop and your policy.
Worked example
You find the dent in the supermarket car park in the evening, no note left. This is how a comprehensive claim works out.
| Repair of bumper with sensors | about EUR 2,800 |
| Deductible on comprehensive cover | EUR 300 |
| Paid by your insurer | about EUR 2,500 |
| Extra premium over three years after the drop in class | about EUR 400 to 900 |
Claiming clearly pays here. For a scratch costing EUR 700, paying yourself is often cheaper.
Whoever damages a parked car is liable. If they come forward or the police trace them, their motor liability insurer (Kfz-Haftpflicht) settles your claim. Your own policy is not touched and your no-claims class (Schadenfreiheitsklasse) stays the same.
If nobody is found, there is no one else to claim from. The German fund for traffic victims (Verkehrsopferhilfe) does not normally pay for damage to your own car after a hit-and-run. Only comprehensive cover pays, because it includes damage by unknown persons and vandalism.
If you touched another car while parking, your liability insurance pays the other owner. The scratch on your own car is only covered by comprehensive cover.
| Situation | Who pays | Your share |
|---|---|---|
| Your car hit, other driver known | their liability insurer | nothing |
| Your car hit, driver unknown, with comprehensive cover | your comprehensive cover | deductible and higher premium later |
| Your car hit, driver unknown, no comprehensive cover | nobody | the whole repair |
| You hit another car | your liability insurer for the other car | drop in no-claims class |
| Your own car after your bump | your comprehensive cover, or you | deductible and higher premium later |
Modern bumpers carry parking sensors, radar and cameras, and headlights are often expensive units with their own control module. A dent that used to cost a few hundred euros can now run into thousands.
A repair cost survey from February 2026 puts a front bump with headlight and bumper at roughly EUR 3,000 to almost 8,000 depending on the model. A rear bump with bumper and sensors costs about EUR 2,100 to 5,100.
After a comprehensive claim your no-claims class drops, no matter whether the repair cost EUR 900 or 9,000. For small damage the extra premium over the next years can be higher than the repair. Do the maths before you claim.
Many insurers let you buy back a claim they have already paid, usually within six months. That way you keep your class if paying yourself turns out cheaper.
Wait a reasonable time at the scene. If nobody turns up, report it to the police. A note under the wiper does not meet the legal duty and does not protect you from a case for leaving the scene of an accident under section 142 of the Criminal Code (StGB).
Driving off can also cost money: your own liability insurer can claw back part of what it paid, usually up to EUR 2,500 and up to EUR 5,000 in serious cases.
Questions and answers
No. Partial cover pays for things like theft, glass, hail or animals, not for damage caused by another car.
Normally not. It only pays for damage to your car after a hit-and-run in exceptional cases with serious injuries.
Usually not for damage caused by other customers. It is more likely liable if the facility itself was faulty, for example a broken barrier.
For an older car of low value usually not. Paying small repairs yourself is often cheaper than the premium.
The police report and the claim are handled in German. Keep the report number and ask for help with the forms if needed.
NAMMERT insurance broker
We compare several insurers and come back with a proposal. Free for you; the insurer pays our fee. You can write in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.
All about this insurance: Car insurance
Can I use my no-claims bonus from abroad in Germany?
Who pays for the damage after a hit-and-run in Germany?
If the driver who fled is traced, their liability insurance pays your damage in full. If they stay unknown, only your …
Should I pay for car damage myself in Germany?
Paying yourself makes sense when the damage costs less than the extra premium a downgrade in your no-claims class woul …
When is comprehensive car insurance worth it in Germany?
Comprehensive cover (Vollkasko) is usually worth it for new, financed, leased and expensive cars, roughly in their fir …
What is the difference between Teilkasko and Vollkasko?
Teilkasko (partial cover) pays for damage you did not cause yourself: theft, storm, hail, fire, broken glass and colli …
NAMMERT Assekuradeur GmbH, insurance broker licensed under section 34d(1) of the German Trade Regulation Act, broker register no. D-C08Q-TOSD4-37. For boat and yacht insurance we act as underwriting agency, not as broker. Statutory disclosure (German) · Updated
Was this useful?