Skip to content

Private office · Yacht and superyacht

Superyacht insurance. Worldwide, no upper limit.

Monaco, Palma, Fort Lauderdale or an anchorage only the captain knows: we build the insurance programme for your yacht and place it worldwide on the international insurance market.

There is no upper limit on hull value, and there is no online quote either. Superyacht insurance starts with a conversation, and your contact is Norman Nammert in person.

Captain and first officer on the bridge of a superyacht at blue hour
Whoever runs the bridge knows the risk best. That is why we talk to the captain first.
No

upper limit on hull value

Worldwide

from the Riviera to Florida

One name

Norman Nammert, in person

Confidential

undertaking to download first

Who calls us

Who we work with

Owners rarely shop for insurance themselves. The call usually comes from the captain, the management company, the family office or the company that owns the yacht. Each of them needs something different, so we ask different questions.

01

Captains

You run the ship and you know every risk on board.

You know where she winters, who is on the crew list and what the last survey found. We build the risk picture with you before the owner signs. And if something happens in port at three in the morning, you reach a person who already knows the file.

  • Crew cover with MLC 2006 certificates
  • Claims taken up with you and filed in full
  • Certificates for marinas, flag and charter
02

Yacht management

Several yachts, many deadlines, one contact.

You manage yachts for owners who want results, not paperwork. We keep renewals, certificates and changes together for every vessel, so yard periods, season changes and charter moves run without a gap.

  • Renewal calendar across your fleet
  • Changes in cruising area, crew or charter
  • Documents for flag state and ports
03

Family offices and wealth managers

The yacht is an asset. Insure it like one.

For your mandate what matters is the agreed value, the owner’s liability and what is on board: art, tenders, equipment. We set the quotes side by side, with every difference in wording, so the decision rests on paper rather than on trust.

  • Agreed value, not market value
  • Art and valuables on board with their own sum
  • No names in the first correspondence
04

Owning companies and corporates

If a company owns her, the policy has to say so.

Many yachts sit in a company, some host corporate guests, some go out on charter. Then the policyholder, the co-insured persons and the use must match exactly, or after a loss the contract describes a different yacht from the one that sank.

  • Company as policyholder
  • Shareholders, guests and crew clearly defined
  • Commercial charter named in the policy
05

Owners

You call yourself. We like that best.

Some owners call in person because they want to know who they are dealing with before the captain or the office gets involved. Then we talk about the yacht and your plans for the next few years first, and about policies afterwards.

  • A conversation, not a questionnaire
  • On board or by video if you prefer
  • Captain and management only if you wish
06

Shipyards, new build and refit

She needs cover before she floats.

During build, refit and delivery the risk changes hands several times: yard, owner, project manager, carrier. We arrange cover for the build period, yard time and delivery so nothing is left open at handover.

  • Builder’s risk for new build and refit
  • Delivery on her own keel or as deck cargo
  • Seamless handover into the running programme

What goes into it

A programme, not a policy

A superyacht is a floating business with crew, guests and machinery. What gets insured is everything attached to her. These are the building blocks we put together for each yacht and each use.

Hull and machinery, agreed value

Hull, engines and equipment at a value fixed in advance. In a total loss nobody argues about depreciation.

Liability and P&I

Third party claims, pollution, wreck removal and liability towards crew and guests, with limits that fit the size of the yacht.

Crew

Wages, repatriation, sickness and injury of the crew, plus the financial security the Maritime Labour Convention requires.

Charter

Commercial charter written into the policy, with the duties owed to charter guests and brokers.

Tenders and toys

Tenders, jet skis, Seabobs and everything else she carries, each with its own sum rather than in the small print.

Fine art and valuables

Paintings, sculpture and valuables face different risks at sea: humidity, motion, transit between homes.

War, piracy, seizure

If the route passes through high risk waters, these perils need to be arranged on purpose, not excluded and forgotten.

Yard, refit and delivery

Months in the yard and passages between seasons, under her own power or shipped as cargo.

People on board

Personal accident for owner, family and guests, matched to what is already in place ashore.

Where she lies

From Monaco to Florida

Every cruising ground raises its own questions. They belong in the submission, before an insurer raises them after a claim.

Monaco and the Côte d’Azur

Berths are scarce, the season is packed and the Yacht Show arrives in September. Marinas ask for proof of liability cover that fits the size of the yacht.

Balearics

Palma is one of the Mediterranean’s big refit hubs. Anchoring on the Posidonia seagrass meadows is banned, and no policy pays the fine.

Adriatic

Croatia and Montenegro: bora in the winter months, charter permits country by country, winter berths often far from the owner.

Florida and the Bahamas

The Atlantic hurricane season runs from 1 June to 30 November. What counts is where the yacht spends those months and what the programme says about it.

Caribbean

A winter season between islands, many jurisdictions in a small sea. Cross-border charter and customs need settling in advance.

Northern Europe and ice

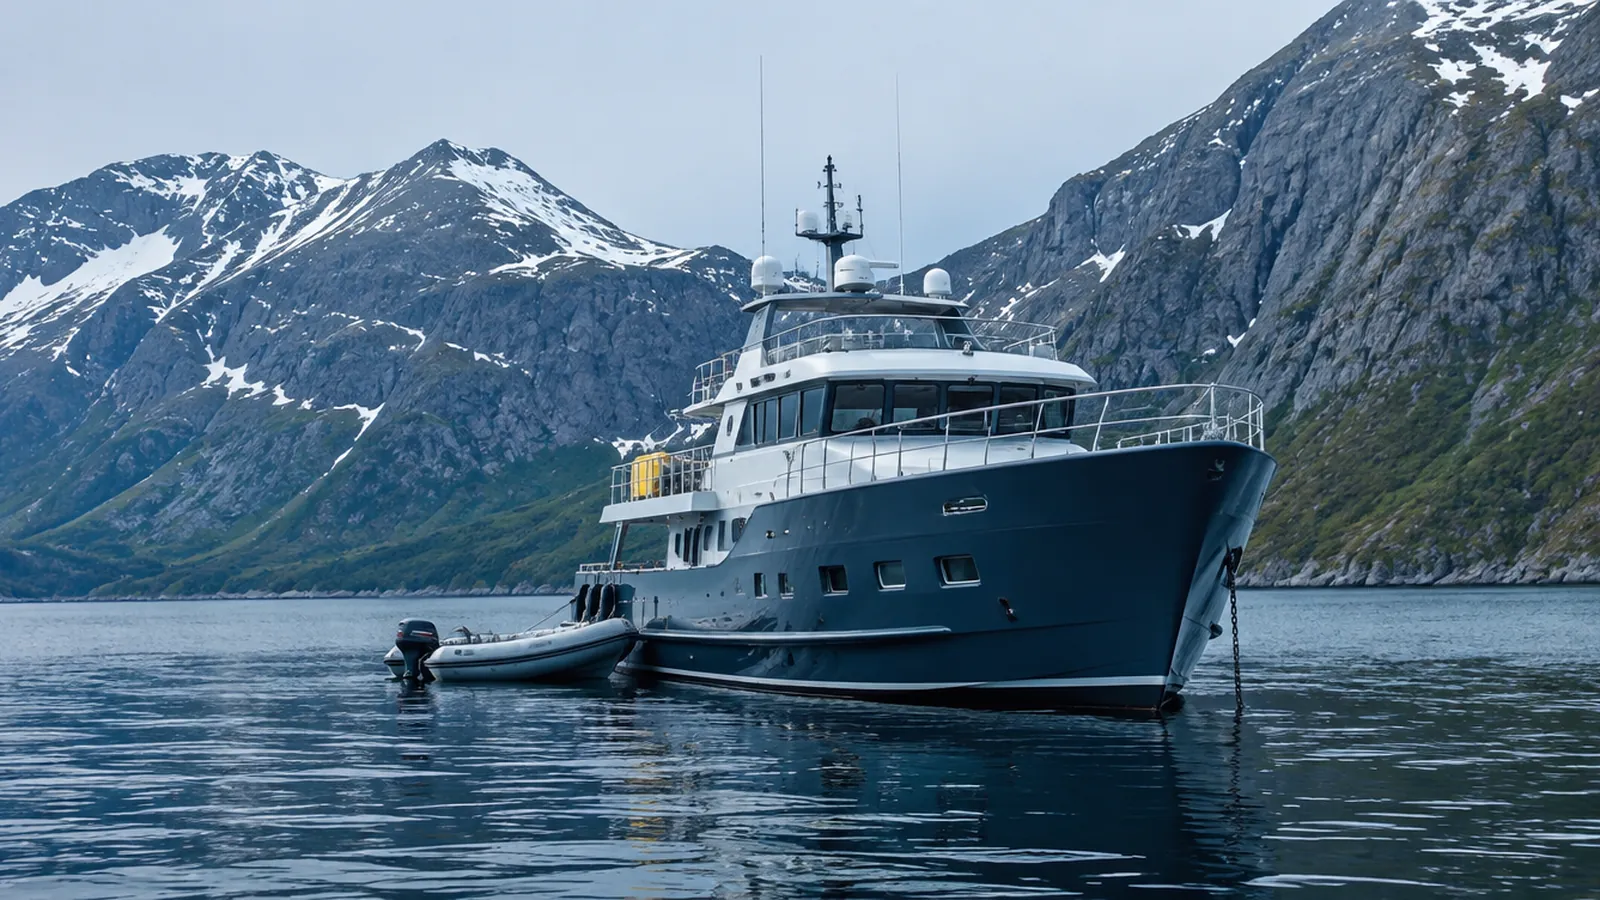
Explorer yachts head to Norway, Svalbard or Antarctica. Cruising limits, ice and evacuation belong in the programme before departure.

In transit

Atlantic crossings, world voyages, the run to the yard: the biggest risks of the year often sit between two seasons.

Northern Europe and ice

How we work

Four steps, one contact

1

A confidential call

By phone, by video or on board. Our confidentiality undertaking applies from the first word, and we send it to you signed beforehand.

2

The risk picture

With the captain or the manager: the yacht, survey, crew, itinerary, current contracts and claims history.

3

The submission

We approach the right insurers on the international market and set the quotes side by side, with every difference.

4

Ongoing service

Renewals, changes and certificates run through us. After a loss we take up the claim and file it in full, and the insurer decides on payment.

Discretion is not an extra

The name of the yacht and of her owner do not need to appear in the first enquiry. A project name is enough.

Documents only go to insurers who can write your risk, and only with your consent.

We do not talk about clients. Least of all famous ones.

Download our confidentiality undertaking (PDF)

A one-sided undertaking by us. You do not need to sign anything.

Norman Nammert, owner and insurance broker

Your contact

Norman Nammert runs the family firm in its second generation; the brokerage started in 1989 near Berlin. He has been on the water since his school days.

He acts as an insurance broker, which means he works for you, not for an insurer. No call centre and no hotline: he reads your enquiry himself.

Insurance broker under section 34d (1) of the German Trade Regulation Act, register no. D-C08Q-TOSD4-37

Enquiry

Enquire in confidence

Tell us who you are and the form only asks what we need for the first step. Your enquiry goes straight to Norman Nammert.

Rather talk?

+49 3375 29 12 77
I am writing as

Download our confidentiality undertaking (PDF)

We use your details for this enquiry only. Privacy

Questions and answers

Frequently asked

Is there an upper limit on the value of the yacht?

No.

We place superyachts on the international insurance market, outside our own tariffs.

Large values are usually shared between several insurers there,

so there is no fixed ceiling on hull value.

Where does the yacht have to be based or registered?

Berth and cruising area are open, whether Monaco, Palma, Florida or the Caribbean.

Flag and the seat of the owning company go into the submission,

because they help decide which insurers can write the risk.

Can the captain make the enquiry?

Yes, and it is often the best route, because the captain knows the yacht in the most detail.

The instruction to place cover then comes from the owner or the owning company.

What does the Maritime Labour Convention require for crew?

Since 18 January 2017 the Maritime Labour Convention (MLC 2006) has required ships within its

scope to carry evidence of financial security for crew repatriation and for claims on death or

long-term disability.

The certificates are kept on board.

For yachts in commercial use this cover is part of the programme.

What does superyacht insurance cost?

It depends on value, cruising area, crew, charter and claims record.

We quote a premium after the submission, with all offers side by side,

not beforehand from a rate table.

Will our details stay confidential?

Yes.

A project name is enough for the first enquiry.

Documents only go to insurers with your consent,

and after our signed confidentiality undertaking if you wish.