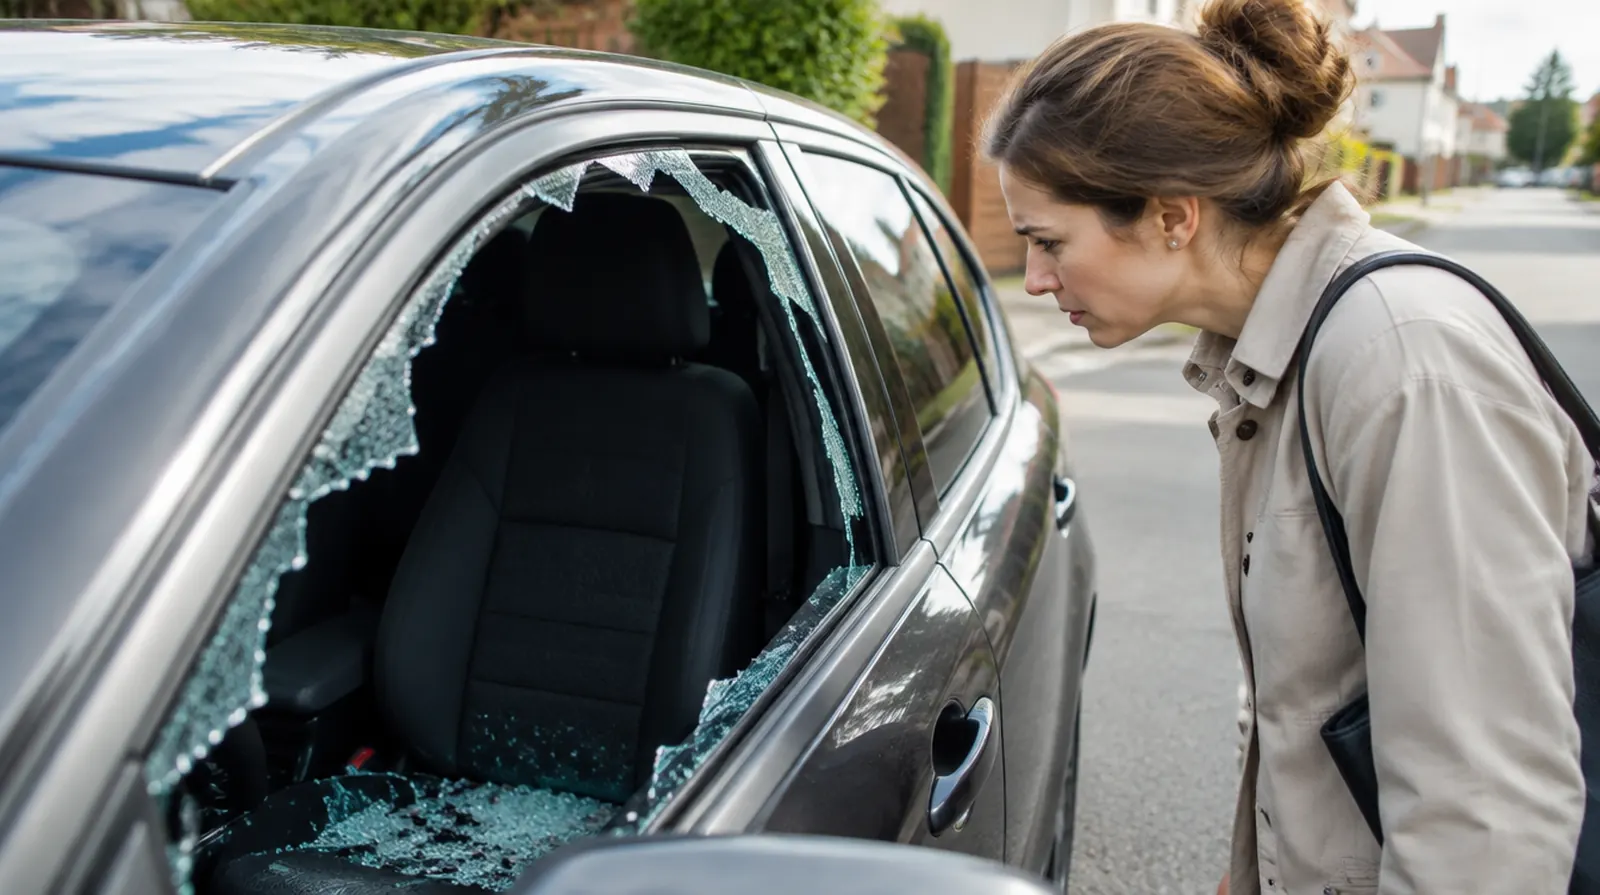
Does German contents insurance pay for theft from a car?
In short
German contents insurance (Hausratversicherung) does pay for theft from a car, but only if your policy includes a specific car clause and the locked vehicle was broken into. Basic policies often leave this out. Where it is included, a separate limit applies, often around EUR 1,000 to 1,300 or 2 percent of the sum insured. Cash and jewellery are usually excluded.
The clause is usually part of better tariffs at no separate price. What matters is how much it pays. Figures from published policy terms and a tariff review.
Example
Typical range
Basic policy without a car clause
EUR 0 for items from a car
Fixed limit in older terms
EUR 1,000 per claim and year
Tariff review: 57 of 116 policies
at least EUR 1,300
Percentage limit on a EUR 60,000 sum insured
2 percent, so EUR 1,200, worldwide
Electronics stowed out of sight: 36 of 116 policies
at least EUR 750
Car opened by jamming or relay attack
EUR 0 to 500 depending on the policy
As of October 2026, from published policy terms and a tariff review.
The worked example is a guide figure from day-to-day quoting.
Your own policy terms are what count.
Worked example
Break-in at a station car park
A commuter has a EUR 60,000 sum insured and a car clause limited to 2 percent. During the day someone smashes the rear window and takes her backpack from the covered boot.
Laptop, replacement value
EUR 1,300
Backpack, jacket, headphones
EUR 350
Cash in her wallet
EUR 80, not covered
Car clause limit (2 percent of EUR 60,000)
EUR 1,200
Smashed window
via Teilkasko, minus the excess
Contents insurance pays EUR 1,200. She bears EUR 450 of the loss plus the cash herself. Without a car clause she would have received nothing for the contents.
When contents insurance pays for items from your car
Your contents insurance covers your flat first. Things you take with you are protected by the outside-the-home cover (Außenversicherung), but a car does not count as a building. That is why most policies need a separate clause for theft from vehicles. If your terms do not mention it, a laptop taken from the boot is normally not covered.
Where the clause exists, the terms almost always require a break-in: the car was locked and the thief smashed a window, forced the lock or used a false key. If you leave the door unlocked or park a convertible with the roof down, you get nothing.
Situation
Paid with a car clause?
Window smashed, bag taken from the back seat
yes, up to the limit, but a cut is possible if it was in plain view
Boot forced open, laptop stowed away
yes, up to the limit; electronics sometimes only at current value
Car was not locked
no, there was no break-in
Wallet with cash taken from the glovebox
the cash usually not, valuables are excluded
Key signal jammed, car stayed unlocked
often no; some newer policies pay up to EUR 500
No car clause in your policy
no
What your car insurance covers
Damage to the car itself is a matter for your car insurance. A smashed window counts as glass breakage and is handled by partial cover (Teilkasko). Permanently fitted parts such as a built-in radio or factory navigation system are also replaced by Kasko.
Loose items such as a phone, bag, child seat or sunglasses are usually not covered by Kasko. For those, only contents insurance with a car clause helps. After a break-in you therefore often file two claims: the car with your car insurer, the contents with your contents insurer.
The limits in the small print
The payout is almost always capped. In a review of 116 German policies, 57 paid at least EUR 1,300 for theft from a car. Other terms set EUR 1,000 per claim and year, or 2 percent of the sum insured, which is EUR 1,200 on a EUR 60,000 policy.
Electronics often face stricter rules. Some policies exclude devices left in the car entirely, others pay for a camera, phone or laptop only at current value or only if it could not be seen from outside. Some also have a night-time clause, which means a break-in at night is only covered in a garage.
Gross negligence: the bag on the passenger seat
Leaving a laptop in plain view invites a break-in, and insurers often treat it as gross negligence. Under section 81 (2) of the German Insurance Contract Act (VVG), the insurer may then reduce the payout according to how serious the fault was.
Many policies waive this reduction up to a set amount. Check that the waiver also applies to items in a car, and put valuables in the boot before you set off, not in the car park where someone may be watching.
When the clause is worth it and when it is not
The car clause makes sense if you regularly leave a laptop, tools, sports gear or shopping in the car, for example on your commute or on road trips. Look for a limit that matches what you carry and for worldwide cover.
If you almost never leave anything in the car, you hardly need it. For expensive camera gear or instruments that often travel by car, the contents limit is rarely enough; specialist policies exist for that. A company laptop is first a matter for your employer's insurance.
Step by step
Call the police straight away, report the theft and hand over a list of what was taken.
Photograph the damage before the car is moved or repaired.
Report the damage to the car to your car insurer and the contents to your contents insurer.
Gather receipts, photos or bank statements for the stolen items.
Block cards, report stolen keys and have locks changed if needed.
Checklist
The car clause is written into your policy terms
The limit matches what you leave in the car
No night-time clause, or a garage for overnight parking
Electronics are included and not only at current value
The gross negligence waiver also applies in the car
Cover applies abroad if you drive on holiday
Common mistakes
Assuming outside-the-home cover automatically includes the car
Leaving a laptop or bag visible on the seat
Not checking the car actually locked, although jammers can block the signal
Claiming only on the car insurance and forgetting the contents
Putting off the police report
Questions and answers
Frequently asked
Is my phone covered if it is stolen from my car?
Only if your policy includes theft from a car and does not exclude electronics.
A lower limit or current value often applies.
Does Kasko pay for a stolen laptop?
Usually not.
Kasko covers fitted parts and the smashed window; loose items belong to contents insurance.
Am I covered on holiday abroad?
It depends on the clause.
Many apply worldwide, some only in Germany or Europe.
Check your terms before the trip.
What if there are no signs of a break-in?
Then a claim is difficult.
Most clauses require a break-in, and you must show the car was locked.
Are belongings in a camper van covered the same way?
Not necessarily.
Many terms treat camper vans and caravans separately, sometimes with their own list of countries.
Can I add the car clause later?
Often yes, by switching to a better tariff or adding an extra module.