All about this insurance: Personal liability
Do I really need personal liability insurance in Germany?
Insurance broker / Insurance questions / Personal liability
In short
No, it does not. In Germany, personal liability insurance (Privathaftpflicht) only pays if you damage someone else's things. If you damage your own things, such as your phone, TV or glasses, the loss stays with you. Only other policies can help: contents insurance for fire, water or burglary, or phone insurance from about EUR 2 a month for breakage.
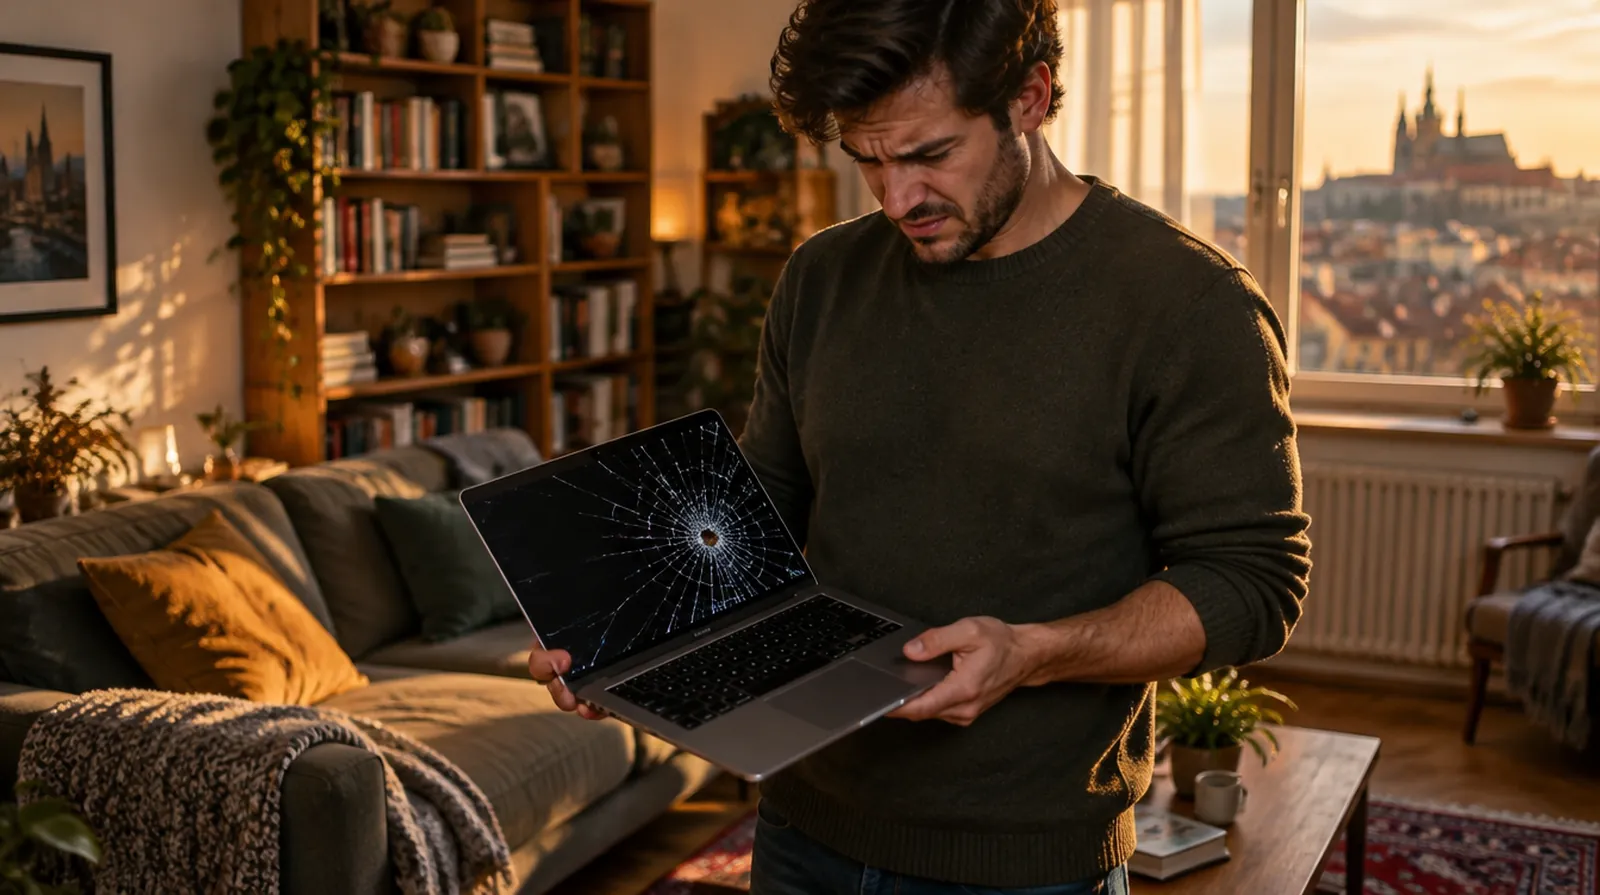
What insurance for your own things costs in Germany, based on figures published in 2026:
| Example | Typical range |
|---|---|
| Phone insurance with screen, drops and water | about EUR 2.19 to 19.99 a month |
| Glass insurance, 70 to 90 square metres | about EUR 40 to 65 a year |
| Contents insurance, 65 square metres | about EUR 70 to 140 a year |
| Contents insurance, 90 square metres | about EUR 90 to 190 a year |
| For comparison: personal liability, single | about EUR 40 to 120 a year |
Guide values as of October 2026 from published tariff examples.
The repair costs in the example are guide values from our quoting practice.
Your premium depends on cover and deductible; we obtain the exact quote.
Worked example
Your one-year-old smartphone slips out of your pocket and the screen cracks. This is how the options compare.
| Personal liability insurance | EUR 0, it is your own phone |
| Contents insurance | EUR 0, dropping is not an insured peril |
| Screen replacement without insurance | about EUR 250 to 400 |
| Phone insurance, EUR 8 a month for two years | EUR 192 in premiums plus a deductible of about EUR 50 |
With one damage in two years, you end up in a similar place with or without insurance. Phone insurance only pays off for expensive devices or several incidents.
Personal liability insurance steps in when a third party claims compensation from you. That is how the model terms of the German insurance association GDV put it (A1-3.1). You cannot claim against yourself, so there is no liability claim when your own laptop falls off the table.
The same applies in a family policy: under A1-7.3 and A1-7.4, claims among co-insured persons and from relatives living in the same household are excluded. If your child knocks your partner's glasses off the table, the liability insurer does not pay either.
| What is broken? | Which policy can pay? |
|---|---|
| Your own phone dropped | phone insurance, not contents insurance |
| Your own mirror or window broken | glass insurance |
| TV destroyed by a lightning surge | contents insurance with surge cover |
| Furniture damaged by fire or a burst pipe | contents insurance |
| Your own car damaged while parking | comprehensive car cover (Vollkasko) |
| Your own boat damaged when mooring | hull insurance for boats |
| Your partner's glasses, same household | no liability cover |
German contents insurance (Hausratversicherung) is not all-risk cover. The VHB 2022 model terms list fire, lightning, surge from lightning, explosion, burglary, vandalism after a break-in, robbery, escaping tap water, storm and hail. Something that simply slips out of your hand is not included.
If you cause the loss through gross negligence, for example an unattended candle, the insurer may reduce the payment under § 81(2) of the Insurance Contract Act (VVG). Good policies waive this fully or up to a limit. If you cause it on purpose, nothing is paid, § 81(1) VVG.
Rented and borrowed things do not belong to you. Damage to a rented flat is covered by many policies as rental property damage (Mietsachschäden), and modern policies often cover borrowed things up to a limit. That is the difference from your own belongings.
Relatives with their own home are third parties. If you break something at your parents' place, your liability insurer can pay, provided you are liable.
Phone insurance costs about EUR 2 to 20 a month according to published tariff lists, with deductibles from EUR 0 to 149. Screen damage, drops and water are usually included, theft is often extra and loss is not covered. For a new, expensive smartphone it can pay off in the first years.
Glass insurance costs about EUR 40 to 65 a year for 70 to 90 square metres. A ceramic hob is often not included automatically, so check the terms.
For an older or cheap phone, simple glasses or tableware, a separate policy rarely pays off. Two years of premiums can quickly exceed the repair. Set the money aside yourself instead.
A second liability policy does not help either: your own things are not covered by any liability insurance, however expensive.
Questions and answers
No.
No liability policy pays for your own things.
Some glasses insurance or optician plans cover breakage, which is a separate contract.
Not if you live in the same household or are on the same policy.
The model terms exclude this.
No.
Contents insurance only pays for the listed perils such as fire, water or burglary.
Damage to your own vehicle is a matter for comprehensive cover: Vollkasko for cars,
hull insurance for boats, depending on the terms also when it was your fault.
Sometimes for new, expensive devices.
Compare the premiums over the planned period of use with the repair costs.
No, they belong to the lender.
Modern liability policies often cover borrowed items up to a limit.
NAMMERT insurance broker
We compare insurers and come back to you, in English.
Free; the insurer pays our fee.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.
All about this insurance: Personal liability
Do I really need personal liability insurance in Germany?
When does personal liability insurance not pay in Germany?
Personal liability insurance (Privathaftpflicht) does not pay for damage caused on purpose, d …
Does personal liability insurance cover borrowed items in Germany?
Only if your tariff includes it explicitly. Older and basic German policies exclude damage to …
Does liability insurance pay for damage within the family?
Mostly no. Liability insurance does not pay for damage within the family if the injured perso …
Should you combine contents and liability insurance in Germany?
In Germany a bundle rarely saves much: around 5 percent discount is usual, often just EUR 5 t …
Your broker: Norman Nammert, trading as NAMMERT.
Insurance broker licensed under section 34d(1) of the German Trade Regulation Act.
Broker register no. D-C08Q-TOSD4-37.
NAMMERT Assekuradeur GmbH is a separate company.
It does not arrange your contract.
Statutory disclosure (German) · Updated
Was this useful?