Does personal liability insurance pay for damage that develops slowly over time?
In short
In many newer German policies, yes: personal liability insurance (Privathaftpflicht) does pay for damage that develops slowly over time, for example damp from your flat soaking a neighbour's ceiling for months. Germans call this Allmählichkeitsschaden. Older policies often exclude it, and wear and tear is never covered. A policy costs about 40 to 120 euros a year.
Gradual damage has no separate price, it is part of the policy. Published examples for personal liability insurance in Germany:
Example
Typical range
Single person, typical policies
about 40 to 120 euros a year
Couple or family
about 60 to 180 euros a year
Single, age 28, at least 10 million euros cover, several policies compared
about 30 to 93 euros a year
Guide values as of May to October 2026 from publicly quoted tariff examples.
Amounts in the worked example are guide values from quoting practice.
Whether gradual damage is included is in your policy terms; we obtain the exact quote for you.
Worked example
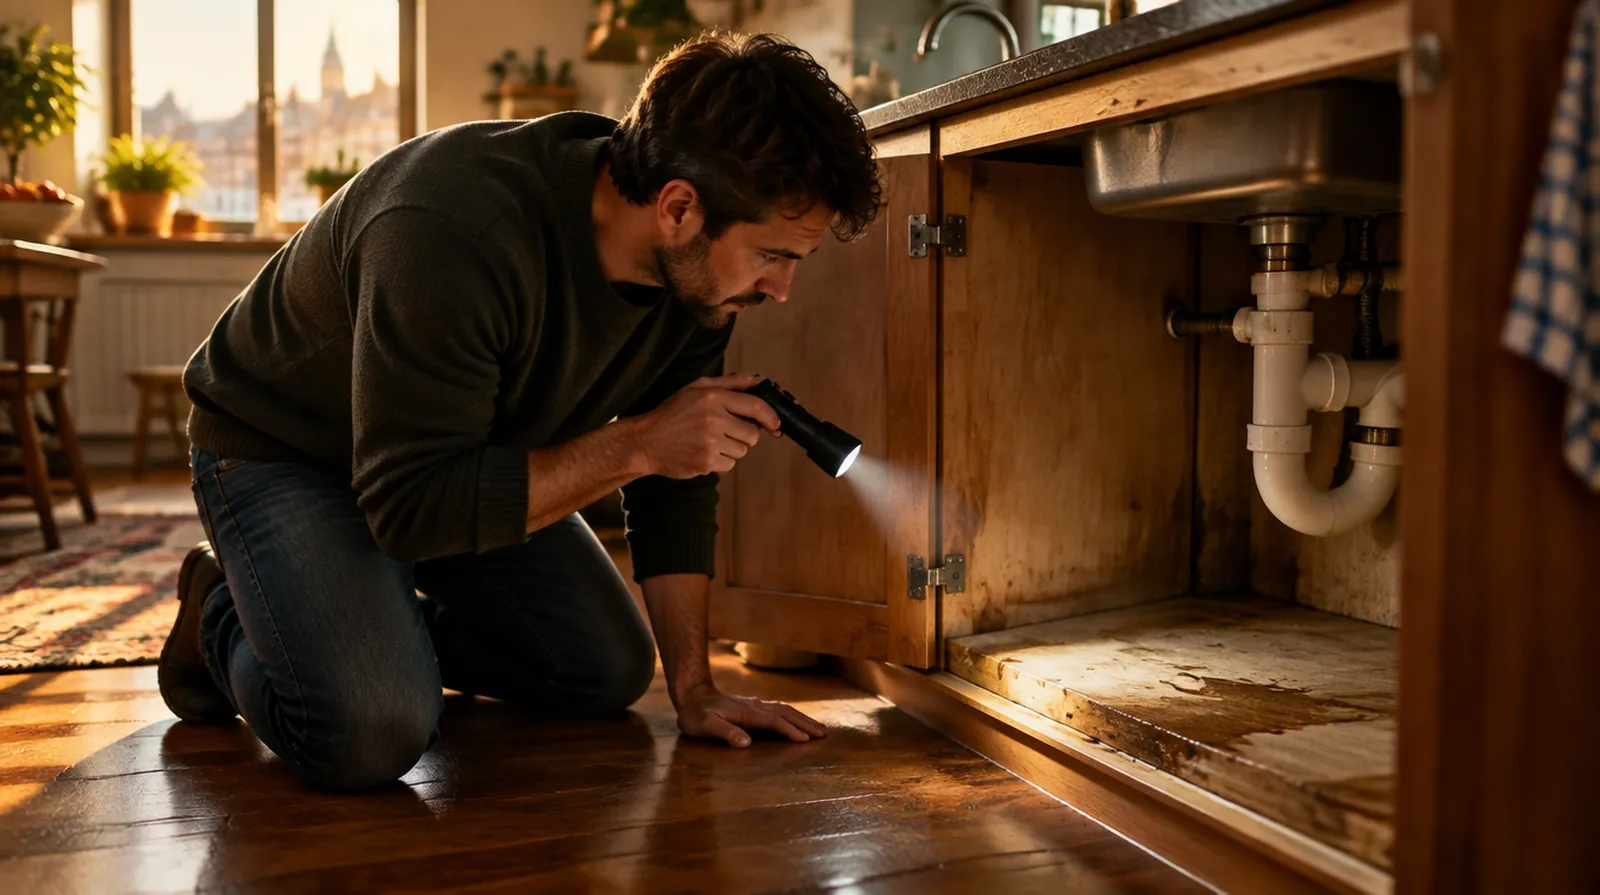
Dripping connection under the sink
A connection under your sink has been dripping for months. You noticed damp in the cupboard but did nothing. A large water stain appears in the flat below.
Drying and decorating at the neighbour's
about 4,500 euros
Older policy with gradual damage exclusion
no payment, you pay yourself
Newer policy with cover, 150 euros deductible
insurer pays about 4,350 euros
If you could not have noticed the damp
insurer checks liability and otherwise rejects the claim
With a current policy you only pay the deductible. With an old one, the same case can cost you thousands.
What gradual damage is
Gradual damage does not happen with a bang. The German Insurance Association describes it as property damage that develops over a longer period, from a few days to years, and often goes unnoticed for a long time.
Examples are damp from a leaking connection creeping into a neighbour's wall, soot from a stove staining someone else's facade, or cooking steam yellowing the ceilings of a rented flat. Because it is found late, repair costs are often high.
Case
Gradual damage?
What usually applies
Hose drips for months, neighbour's ceiling damp
yes
covered in newer policies if you are liable
Pipe bursts, water comes through at once
no, sudden damage
standard liability case
Soot from a stove stains the wall next door
yes
depends on the policy
Mould after damp in a rented flat
often yes
some policies exclude mould separately
Carpet in the rented flat worn out
no, wear and tear
never covered
Old policy or new policy
In the past, gradual damage was excluded from personal liability insurance in Germany. Many current policies now include it. If your contract is several years old, search the terms for the words Allmählichkeit, allmähliche Einwirkung or Feuchtigkeit.
If you find an exclusion, switching to a current policy is worth it. Check rental property damage (Mietsachschäden) as well: damage to your own rented flat is a separate item, damage to the flat below is ordinary third party damage.
The limits: wear and no fault
Wear and tear is not gradual damage. Worn floors, faded wallpaper and normal signs of use are not paid by any liability insurer.
The policy also only pays if you are legally responsible. Under § 823 of the German Civil Code (BGB) that requires intent or negligence. If the cause was a hidden pipe belonging to your landlord that you could not notice, you are usually not liable. Your insurer then rejects the claim on your behalf instead of paying.
When you do not need it
If you run no water appliances, have no stove and live in a detached house, your risk is small. For tenants in blocks of flats the cover is almost always worth having, because water and damp cause most large claims from neighbours.
Damage to your own house is never covered by personal liability insurance. That is the job of buildings insurance (Wohngebäudeversicherung).
Step by step
Search your policy terms for Allmählichkeit, Feuchtigkeit and Schimmel.
Check whether rental property damage is included too.
If excluded, choose a current policy that includes gradual damage.
Have damp patches, drips and smells fixed at once.
Report a discovered claim within one week and promise nothing.
Checklist
Gradual damage expressly included
No separate exclusion for mould
Damage to the rented flat covered
Cover of at least 10 million euros
Water appliances checked regularly for drips
Common mistakes
Keeping an old contract without reading the exclusions
Ignoring visible damp for weeks and so acting negligently
Treating wear and tear in a rented flat as an insured loss
Promising the neighbour full payment straight away
Questions and answers
Frequently asked
What is gradual damage?
Property damage that does not happen suddenly but builds up over time, for example through damp,
steam, soot or gases.
Is mould gradual damage?
Often yes.
Some policies exclude mould separately, so the wording of your terms decides.
How do I know whether my policy covers it?
Look for Allmählichkeit or allmähliche Einwirkung in the terms.
If it appears under exclusions, you are not covered.
If in doubt, ask in writing.
Does liability insurance pay for wear and tear?
No.
Wear, tear and excessive use are not gradual damage and are not insured.
Who pays for slow damage to my own house?
Never personal liability insurance, which only covers damage to others.
Buildings insurance is responsible for your own property and has its own rules.
What should I do if a neighbour reports damp damage?
Stop the cause, take photos and report it to your insurer within one week,
as § 104 of the Insurance Contract Act (VVG) requires.
Do not promise payment.
Does switching policy help with damage that has already happened?