All about this insurance: Bicycle and e-bike
Is my bike covered by my German contents insurance?
Insurance broker / Insurance questions / Bicycle and e-bike
In short
Is your bike on a car bike rack insured in Germany? Usually not through your car insurance. Comprehensive cover (Kasko) often includes the rack but not the bike, and liability cover only pays for damage to others. For theft from the rack you need bike insurance or the bike add-on to contents insurance. Accident damage needs bike cover with damage, from about EUR 70 a year.
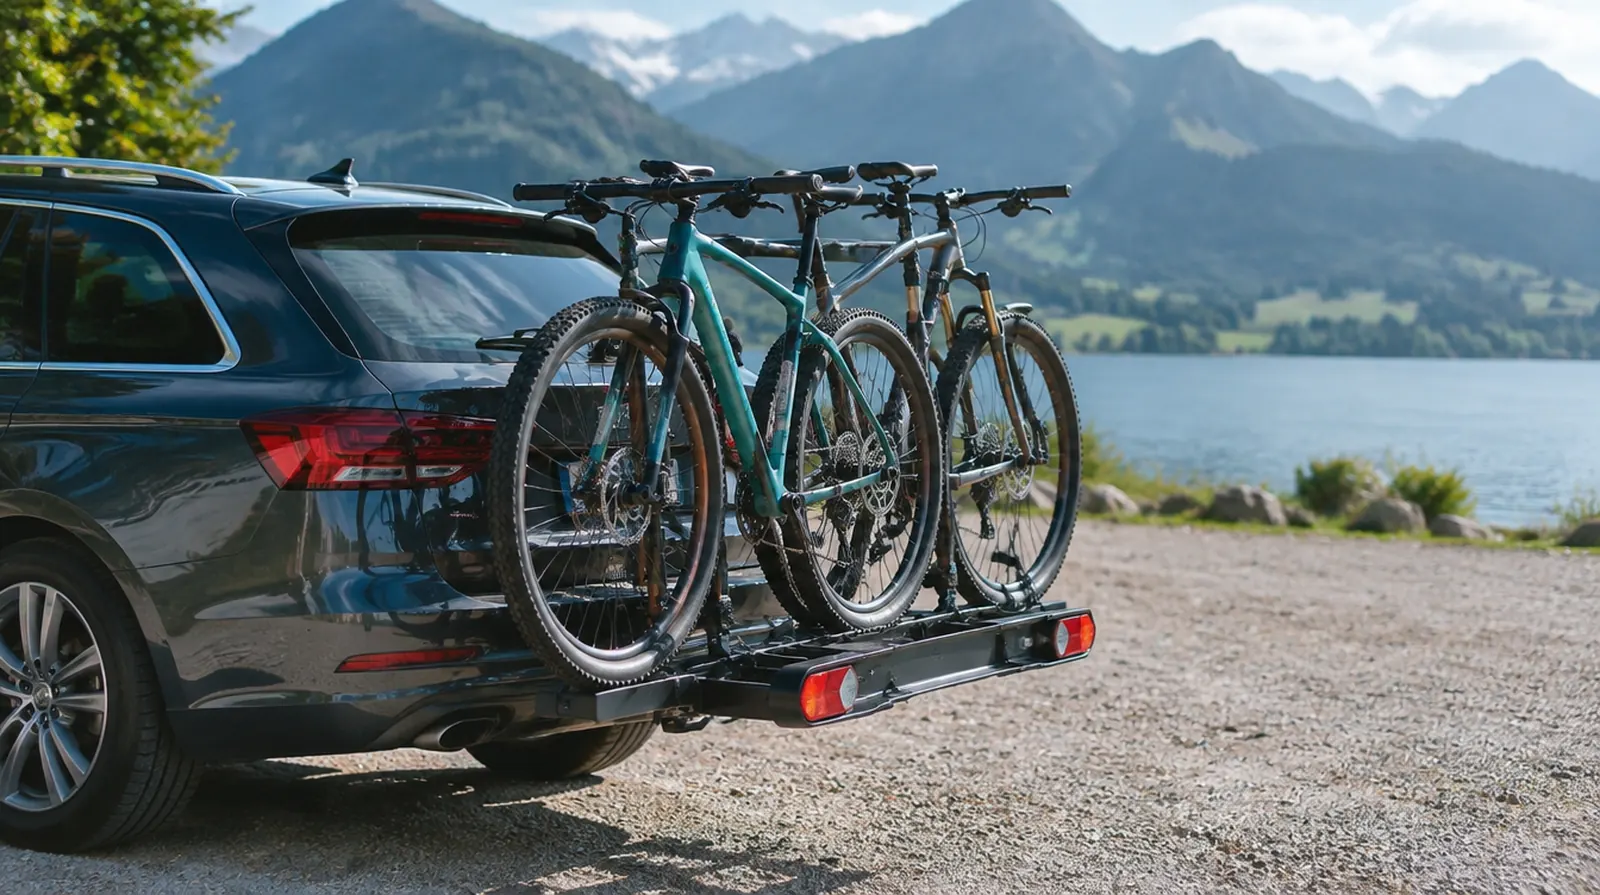
Published annual premiums for bike cover in Germany, as of 2026.
| Example | Typical range |
|---|---|
| Separate bike insurance for a EUR 1,500 bike | about EUR 48 to 370 a year |
| Theft-only policy for an everyday bike | usually well under EUR 50 a year |
| Theft policy for an e-bike | from about EUR 50 a year |
| Policy with damage cover and extra services | from about EUR 70, sometimes over EUR 250 a year |
| Bike add-on to contents insurance | about EUR 20 to 50 extra a year |
Guide values as of October 2026 from published premium examples.
The price of the bike add-on and the worked example are guide values from quoting practice.
Your premium depends on the bike's value, where you live and the scope of cover;
we obtain the exact quote for you.
Worked example
How differently the contracts pay when something happens on the way.
| Two e-bikes, combined value when new | EUR 6,000 |
| Theft from the locked rack, contents insurance with bike add-on up to EUR 1,000 | at most EUR 1,000 |
| Same theft, separate bike insurance at new value | up to EUR 6,000 |
| Rear-end collision you caused, bikes crushed, no bike damage cover | EUR 0 |
| Bike damage cover for both bikes | from about EUR 140 a year |
With the bike add-on, EUR 5,000 stays uncovered after a theft, and the whole loss after an accident you caused. Bike cover with damage closes both gaps.
To an insurer, a bike on the rack is load. Partial and full comprehensive cover (Teilkasko and Vollkasko) protect the car with its fixed parts and accessories. Many policy terms name roof and rear racks expressly, but not items that do not serve the use of the car. Your bike falls through that gap.
Car liability insurance (Kfz-Haftpflicht) pays for damage you cause to others with the car. If the bike comes loose on the motorway and hits the car behind you, that is such a case. It never pays for your own bike.
Less well known: many German car policy terms also exclude damage to items carried in or on the car. The only exception is what passengers normally have with them, such as clothing, glasses or luggage. If you take a friend's bike along and cause an accident, your liability cover will not pay for it. If the other driver is at fault, their liability insurance also pays for your bikes.
| What happens | Who pays |
|---|---|
| Bike stolen from a locked rack | bike insurance or the bike add-on to contents insurance |
| Bike crushed in a rear-end collision you caused | only bike cover with damage |
| Bike crushed in an accident caused by the other driver | the other driver's car liability insurance |
| Bike falls off and damages another car | your car liability insurance |
| Rack stolen or damaged in an accident | often your partial or full comprehensive cover |
| Bike slips and scratches your own paintwork | usually nobody, as this often counts as operating damage |
Without an add-on, contents insurance (Hausratversicherung) only pays for a stolen bike after a break-in to your flat, cellar or garage. On a rack at a motorway service area, it is simple theft, which needs the bike add-on. That add-on often pays only up to a fixed sum, for example EUR 1,000, or a percentage of the sum insured.
Separate bike policies sometimes name the rack expressly: theft from a rack mounted on the car is covered if the holder was locked. Some also pay for theft from a locked car. If your contract has a night-time clause, a theft at night may still not be paid.
A rear-end collision with two e-bikes on a rear rack can easily cost several thousand euros. Contents insurance never pays here, as it does not cover accidents. A theft-only bike policy does not help either.
Only bike cover that expressly includes accidents, including accidents of the means of transport, can pay. Check that the battery and the on-board computer are covered.
Under section 22 (1) of the road traffic regulations (StVO), load must be secured so that it does not slip or fall even in an emergency stop. Check the straps and frame holders before every trip.
If the rack or the bikes hide the rear number plate, section 12 (10) of the vehicle registration regulation (FZV) requires the plate to be repeated on the car or the rack. This third plate needs no official stamp. If the load sticks out more than one metre beyond the rear reflectors, section 22 (4) StVO requires it to be marked.
If you only take an inexpensive bike on short trips to the lake and never leave the car unattended, the bike add-on or no extra cover at all is often enough.
If you take expensive e-bikes on holiday, stop on the way and park overnight at a hotel, the risk is different. Then bike insurance with theft from the rack and accident cover is worth it.
Questions and answers
No.
Teilkasko pays for theft of the car and covered parts.
The rack itself is often included, the bike is not.
Your car liability insurance pays for damage to other cars or people.
Only bike cover with damage replaces your own bike.
Yes, if the rack or bikes fully or partly hide the rear plate.
Section 12 (10) FZV requires this, and no stamp is needed.
Against theft, sometimes, as some bike policies also pay for theft from a locked car.
In an accident it is the same as on the rack: only bike cover with damage pays for the bike.
Some bike policies apply worldwide around the clock.
The exact area is set out in the terms, so look before you travel.
For theft cover, almost always.
Many contracts require a locked holder or a separate bike lock.
NAMMERT insurance broker
We compare insurers and come back to you, in English.
Free; the insurer pays our fee.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.
All about this insurance: Bicycle and e-bike
Is my bike covered by my German contents insurance?
Contents insurance or a separate bike policy: which is better?
Up to a bike value of about EUR 1,000 the bike add-on in your contents insurance (Hausratvers …
How much does bike insurance cost in Germany?
For a bike worth EUR 1,000, the bike add-on of your contents insurance often costs only aroun …
What should I do if my bike is stolen in Germany?
File a police report (Anzeige) the same day, within 48 hours at the latest, and notify your i …
What is the night-time clause in bike insurance?
What is the night-time clause in bike insurance? If your policy has it, bike insurance or the …
Your broker: Norman Nammert, trading as NAMMERT.
Insurance broker licensed under section 34d(1) of the German Trade Regulation Act.
Broker register no. D-C08Q-TOSD4-37.
NAMMERT Assekuradeur GmbH is a separate company.
It does not arrange your contract.
Statutory disclosure (German) · Updated
Was this useful?