Car detailing businesses work on other people's property every day, often on cars worth more than the whole workshop. A few seconds too long with the polisher on an edge, the wrong product on leather, a knock while moving a car: these are exactly the losses many standard policies in Germany leave out. Here is what to look for and what the cover costs.
Does my public liability pay if I damage a client's paint while polishing?
Only if damage to items you work on is included. Damage to the very thing you are working on is excluded in many basic policies, and in detailing it is the most common loss. The same goes for cars parked overnight in your unit: if there is a break in or a fire, you need a goods in care extension. Get both confirmed in writing.
What goes wrong in this trade
01
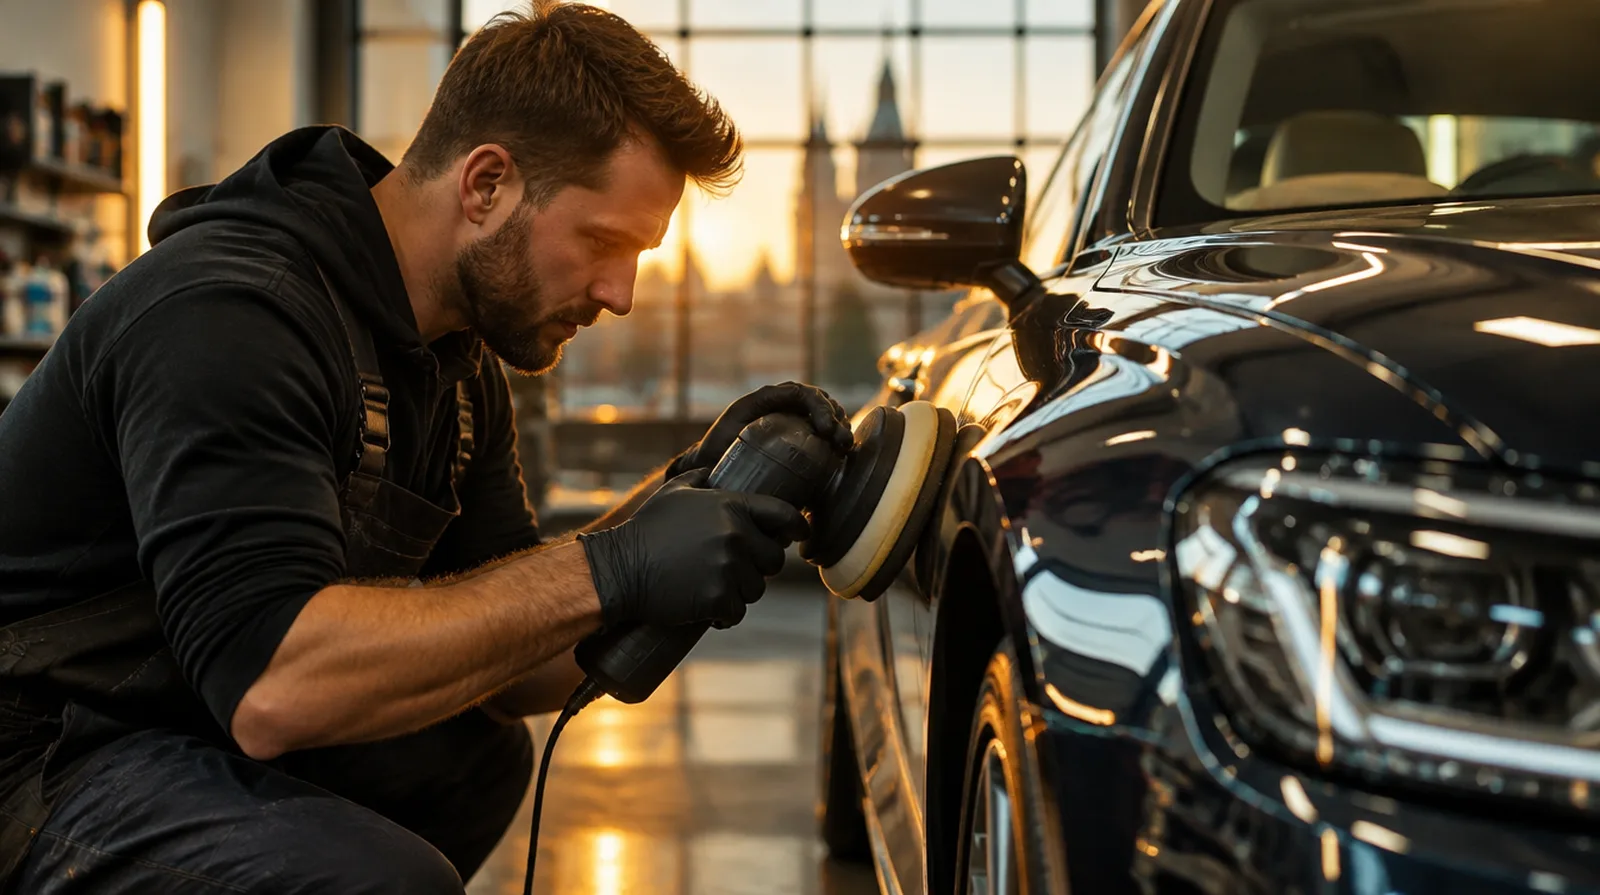
Paint polished through
On edges and creases the clear coat is thin. A few seconds too long with the machine, and the panel needs a respray.
02
Wrong product
Acidic wheel cleaner on anodised parts, solvent on leather or Alcantara: the damage often shows only once the client is home.
03
Client cars in your unit
Break in, fire or a collapsing shelf: your clients' cars spend the night with you and are often worth more than your equipment.
04
Moving cars
A post at the wash bay entrance, a touch with the next car: manoeuvring damage to client cars is expensive.
05
Mobile work
Water and chemicals on paving, a scratched garage door, a cable across the path: with mobile detailing the damage happens on someone else's property.
06
Disputes over the result
The client sees holograms in the paint and refuses to pay, or says a scratch is new. Without photos it gets difficult.
Not compulsory, but essential. What matters is damage to worked on items and to cars in your care; without these the most common losses are not covered.
For you as owner, if you are not voluntarily insured with the Berufsgenossenschaft (statutory accident insurer): chemicals, wet floors and lifts carry real risks.
Income protection: kneeling, bending and machine vibration take their toll on back, knees and hands.
What it costs: example prices
Few insurers publish tariffs for car detailing. The premium depends mainly on how many client cars are in your care at once, what they are worth and whether damage to worked on items is included.
Insurance
Example
Typical range
Business liability
Sole trader, €3 million limit, without goods in care or worked on items
about €250 to €450 a year
Business liability
Unit with two employees, including worked on items and goods in care up to €100,000 per car
about €600 to €1,400 a year
Business contents
Machines, equipment and products worth €40,000
about €200 to €450 a year
Car insurance
Panel van for mobile detailing with water tank, business use, third party and partial cover
about €700 to €1,400 a year
Business legal expenses
Small business with contract, employment and tenancy legal cover
about €350 to €800 a year
For comparison: Public liability with goods in care cover costs about as much per year as one ceramic coating on a luxury saloon.
All premiums are guide values from our quoting work, excluding German insurance premium tax,
as of October 2026.
The minimum motor liability limits are set in the Compulsory Insurance Act
Six things detailers really go through, all on one Friday before the weekend. Tap through and see who pays.
Damage so far€35,000
Driving a client's SUV into the wash bay, an employee scrapes the door post.
€2,900 · Paid by: Business liability
The clear coat on the bonnet edge is polished through; the bonnet needs a respray.
€1,400 · Paid by: Business liability
A solvent leaves stains on the leather bench of a classic car.
€3,800 · Paid by: Business liability
On a mobile job the neighbour trips over the polisher's cable and breaks her wrist.
€7,000 · Paid by: Business liability
A client refuses to pay for a paint correction and threatens to sue.
€1,900 · Paid by: Business legal expenses
A short circuit in a dryer starts a fire; machines and stock are destroyed.
€18,000 · Paid by: Business contents
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €35,000
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Have damage to worked on items and goods in care written into your public liability policy, with a limit per car that matches the most valuable car you take in.
Photograph every car all round on arrival and have existing damage signed off on the job sheet.
Measure paint thickness before polishing and record the reading.
Check whether drives in client cars, for example to the petrol station or for collection, are covered.
Store chemicals separately and safely; good fire protection also lowers your contents premium.
Keep client keys overnight in a locked key safe.
Why NAMMERT for your business
We know the gap with client cars
Worked on items and goods in care are excluded in many policies. As an insurance broker, Norman Nammert compares the wording of several insurers and shows you where cover is missing.
Unit, van and business
Liability, contents, service van and your personal cover all run through one contact.
We know paint claims
In boat insurance we handle claims ourselves, including paint and gelcoat. We know which photos and reports an insurer wants to see.
Broker since 1989
A family business, not tied to any insurer. Our service is free for you; the insurer pays our commission. We advise in English.
Frequently asked questions
Questions and answers
Which insurance is compulsory for car detailers in Germany?
None for the business itself.
Motor liability is compulsory for your own vehicles.
Public liability is not required by law,
but without it you pay for every damaged client car yourself.
What are damage to worked on items and goods in care?
The first is damage to the thing you are working on, such as paint polished through.
The second covers cars entrusted to you, for example in a fire or break in at your unit.
Many basic policies exclude both.
What does public liability cost for a car detailer?
Without extensions about €250 to €450 a year;
with worked on items and goods in care for a business with its own unit about €600 to €1,400.
These are guide values from our quoting work.
Who pays if a client's car is stolen from my unit?
From your own insurance, only public liability with the goods in care extension.
Without it you have to settle the loss with your client yourself.
Is mobile detailing insured differently?
Your public liability must cover work on other people's property,
and the service van must be declared for business use.
Do I need business interruption cover?
If you have your own unit it is worth it: after a fire, rent,
wages and leasing keep running even when no car can be worked on.
NAMMERT insurance broker
Request quotes for Car detailing
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.