Insurance for rope access technicians and work at height in Germany
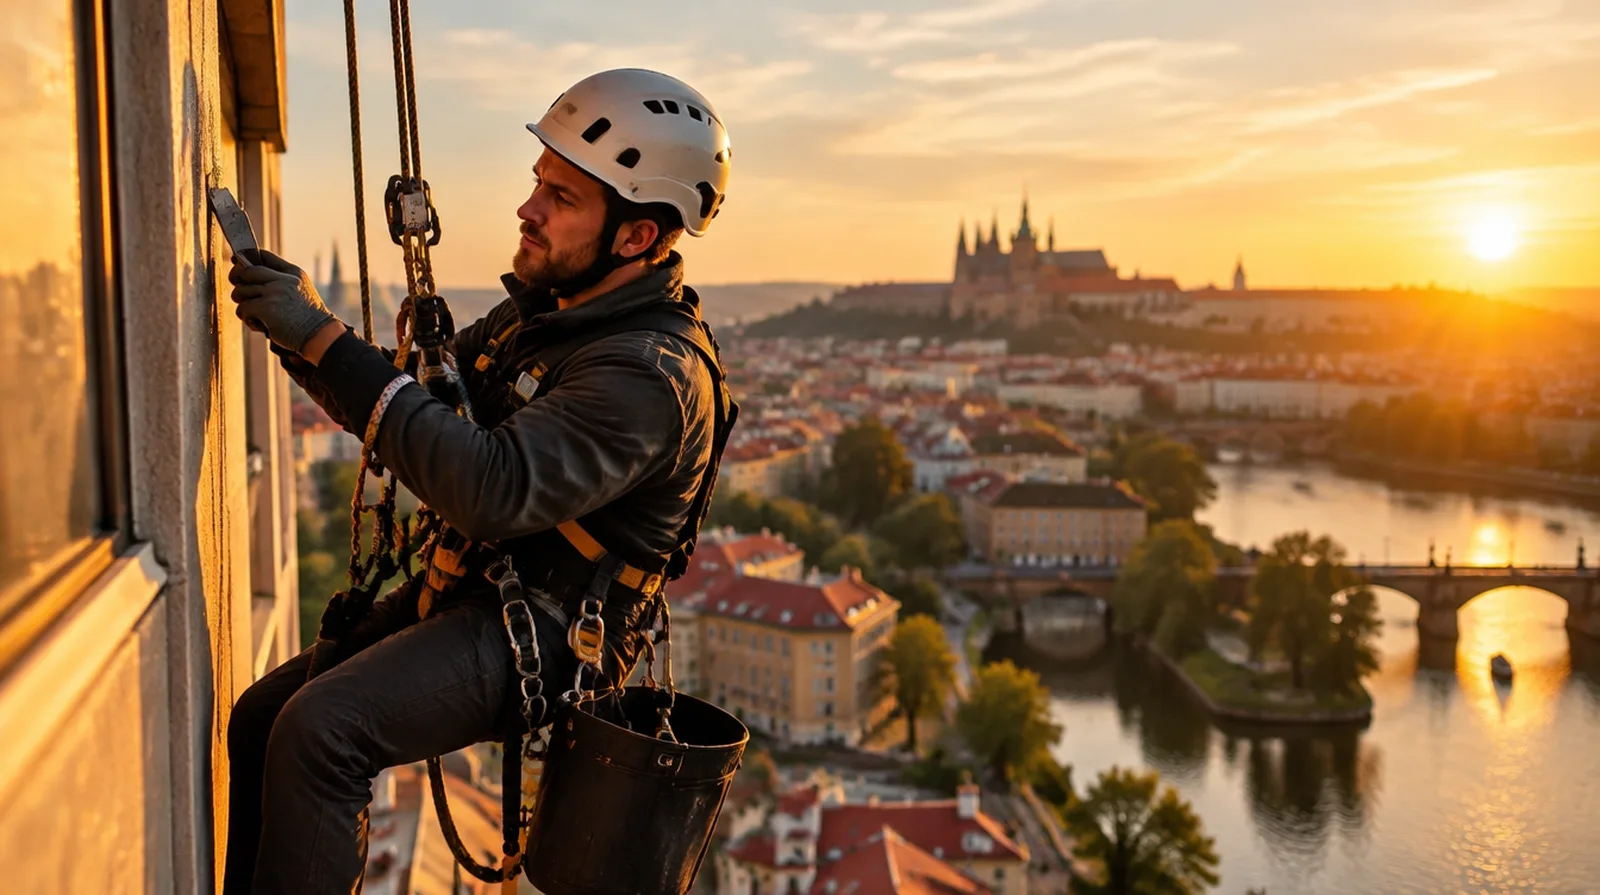
Many rope access technicians in Germany trained under international schemes and work on facades, wind turbines, bridges and industrial plants. German law sets clear rules for rope access in the Industrial Safety Regulation (Betriebssicherheitsverordnung): at least two separately anchored ropes and special instruction in rescue procedures. The real cost in work at height usually comes from below: a dropped tool hits a car, a glass panel cracks, a colleague is injured. This page explains which insurance rope access technicians and companies in Germany need and what it roughly costs.
Does my liability insurance pay if I damage the facade I am working on?
Not automatically. Many policies exclude damage to the object you are working on. German policies use separate clauses for this, often with their own limit and excess. For glass facades, rotor blades or industrial plant, choose that limit carefully and have the inclusion confirmed in writing.
What goes wrong in this trade
01
Dropped objects
A drill or a piece of cladding falls 30 metres onto a pavement, a car or a person.
02
Damage to the structure
A glass pane cracks during cleaning, or a rotor blade or coating is damaged during descent.
03
Falls and suspension trauma
Even with two ropes, work at height is dangerous. A delayed rescue can have serious consequences.
04
Client downtime
If a plant stays shut down longer because something was damaged, the operator claims compensation.
05
Theft of equipment
Ropes, devices and tools in the van are expensive and attractive to thieves.
06
Wear and tear
Shoulders, knees and back carry kit every day. If you can no longer climb, your income stops.
Pays for injury and property damage caused by your work at height. Check cover for damage to the object worked on and a high limit for personal injury.
For disputes over payment, acceptance of work and liability after an accident on site.
What it costs: example prices
Premiums depend mainly on turnover, staff numbers and the type of work. Window and facade cleaning costs less than work on wind turbines or industrial plant, where damage to the object becomes expensive.
Insurance
Example
Typical range
Business liability
Sole trader, facade and glass cleaning, 5 million euros cover
around 600 to 1,200 euros a year
Business liability
Company with five employees, industry and wind energy, 10 million euros cover
around 2,500 to 6,000 euros a year
Group accident insurance
Five employees, 150,000 euros disability sum
around 600 to 1,300 euros a year
Accident insurance
Owner, age 40, 200,000 euros base sum with progression
around 300 to 700 euros a year
Business contents
Store with equipment worth 40,000 euros
around 200 to 450 euros a year
For comparison: Public liability for a small rope access company costs about as much a year as one or two days of facade work.
Guide values from our quoting experience, as of October 2026,
excluding German insurance premium tax.
Not every insurer accepts work at height; we obtain the exact quote for you.
Six things that really happen to rope access technicians, here all on a single Tuesday. Tap through and see who pays.
Damage so far€66,800
During rigging a karabiner falls from the roof and smashes the windscreen of a parked car.
€1,800 · Paid by: Business liability
A double-glazed facade panel cracks during cleaning.
€9,000 · Paid by: Business liability
An employee swings into the facade and badly injures a shoulder, off work for months.
€25,000 · Paid by: Group accident insurance
A falling piece of joint sealant hits a passer-by on the head.
€15,000 · Paid by: Business liability
Ropes, descenders and power tools are stolen from the van overnight.
€12,000 · Paid by: Car insurance
The client refuses acceptance and withholds payment.
€4,000 · Paid by: Business legal expenses
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €66,800
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Have damage to the object worked on expressly included and choose the limit to match your most expensive jobs.
Tell the insurer every type of site, such as wind turbines, offshore, bridges or industrial plant; some are excluded.
Follow Annex 1 no. 3.4 of the Industrial Safety Regulation and document your risk assessment, instruction and rescue plan.
Cordon off the area below you and tether tools; it reduces claims and strengthens your position in a dispute.
Check whether equipment stolen from the van is covered by motor own damage cover or a tools clause.
Protect yourself as the owner against accident and loss of earning capacity; without voluntary Berufsgenossenschaft cover you lack statutory protection.
Why NAMMERT for your business
We know the tricky clauses
As an insurance broker, Norman Nammert compares several insurers and checks damage to the object worked on, site exclusions and limits for personal injury.
We know claims handling
In boat insurance we handle claims ourselves. We know what an insurer wants to see after property damage on site.
Advice in English
We explain German policy wording in plain English, and you get the documents explained before you sign.
Brokering since 1989
Our advice costs you nothing, as the insurer pays our commission.
Frequently asked questions
Questions and answers
Is public liability insurance compulsory for rope access work in Germany?
Not by law.
Clients almost always ask for proof,
and without insurance you are personally liable for damage caused by falling objects.
How much does rope access insurance cost in Germany?
As a guide from our quoting experience, around 600 to 1,200 euros a year for a sole trader.
Companies working in industry or wind energy pay considerably more.
Which rules apply to rope access in Germany?
Annex 1 no.
3.4 of the Industrial Safety Regulation requires at least two separately anchored ropes,
a harness, secured tools, careful planning and supervision and special instruction,
above all in rescue procedures.
A single rope is allowed only if the risk assessment shows a second rope would be more dangerous.
Is damage to the facade I work on covered?
Only with a clause for damage to the object worked on.
Check the limit and excess before working on glass facades or expensive plant.
Are my employees insured if they fall?
Through the statutory accident insurer, the Berufsgenossenschaft.
Group accident insurance pays an additional lump sum for permanent injury.
Does my policy cover jobs outside Germany?
Only if it includes work abroad.
Clarify this before the first job, especially for wind farms in neighbouring countries.
NAMMERT insurance broker
Request quotes for Rope access
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.