Insurance for cheese makers, farm creameries and dairies in Germany
Listeria in raw milk cheese, a ripening cellar whose climate fails over the weekend, a cheese vat that breaks in the middle of the season: for cheese makers, farm creameries and dairies, much of the value sits in the cellar for months before it is sold. This page explains what to cover in Germany and what it costs.
Is the cheese in my ripening cellar insured if the climate control fails?
Only if spoilage after a machinery breakdown or power cut is expressly included. Contents insurance pays for fire, burst pipes or burglary. If only the equipment fails and the cheese spoils, you need machinery breakdown cover that includes stored goods.
What goes wrong in this trade
01
Germs in the cheese
Listeria and other germs are often only found in an official sample or after people fall ill. Raw milk and soft cheeses are most at risk.
02
Ripening cellar
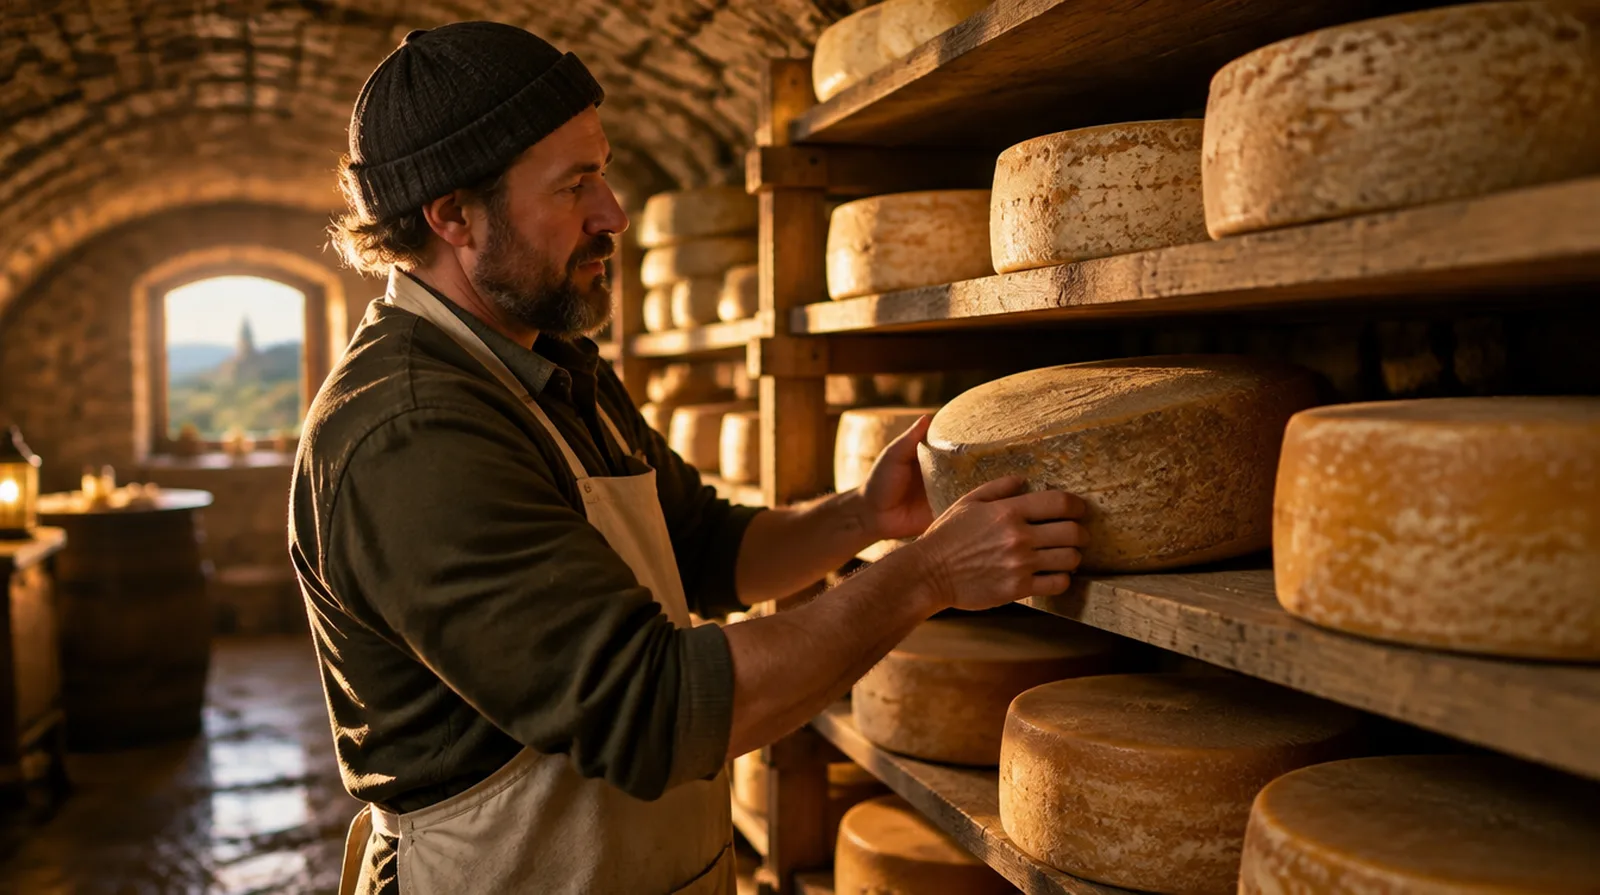
Months of work lie in the cellar. A climate fault, foreign mould or water destroys a whole ripening batch.
03
Cooling and equipment
Milk tank, vat, pasteuriser and refrigeration run every day. If one fails, milk has to be discarded.
04
Cleaning chemicals
Caustic and acid cleaners cause chemical burns, and a wrongly mixed batch can pollute waste water.
05
Foreign bodies and allergens
Metal from the curd knife or press, undeclared ingredients in cream cheese and spreads: classic liability claims.
06
Farm shop and visitors
Farm creameries welcome customers, school classes and guests. A fall on a wet floor ends up with you.
For dairies with digital traceability, till systems and an online shop.
What it costs: example prices
Premiums depend on whether you process raw milk, how long your cheese ripens and who you supply. A farm creamery with a shop pays much less than a dairy supplying supermarkets.
Insurance
Example
Typical range
Business liability
Farm creamery with shop and market sales, €3 to €5 million cover
around €400 to €1,000 a year
Business liability
Cheese dairy with 15 staff supplying retailers
around €1,800 to €5,000 a year
Business contents
Equipment and ripening stock worth €400,000
around €600 to €1,600 a year
Machinery breakdown
Refrigeration, pasteuriser and vats with a new value of €250,000, including spoilage
around €800 to €2,200 a year
Business interruption
Business interruption with a 12 month indemnity period
around €400 to €1,500 a year
For comparison: Liability and contents cover for a small farm creamery cost roughly as much a year as two wheels of mountain cheese.
Guide figures from our quoting, as of October 2026, excluding German insurance tax.
Published tariffs for cheese dairies are rare.
The sources support the legal statements on this page; we obtain the exact quote for you.
Six things that really happen to cheese makers, all on one Monday after a long weekend. Tap through and see who pays.
Damage so far€540,000
The ripening climate failed on Saturday. Foreign mould is growing on 800 wheels.
€45,000 · Paid by: Machinery breakdown
The milk tank's cooling is broken and 6,000 litres of milk must be discarded.
€3,500 · Paid by: Machinery breakdown
The authority reports listeria in a sample. Several customers are ill and claim damages.
€60,000 · Paid by: Business liability
A visitor slips on the wet floor of the farm shop and breaks her wrist.
€7,000 · Paid by: Business liability
The delivery van's cooling unit fails on the round and the goods can no longer be sold.
€4,500 · Paid by: Cargo insurance
A cable fire in the plant room spreads to the dairy and ripening cellar.
€420,000 · Paid by: Business contents
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €540,000
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Insure the ripening stock at its full value and raise the sum as the cellar fills up.
Expressly include spoilage after failure of cooling, climate control and power, also for milk in the tank.
Choose at least €5 million product liability if you supply retailers, and look at recall cover.
Document checks, temperatures and batches; that decides the evidence and the amount after a loss.
Plan a long indemnity period in business interruption, because ripened cheese cannot be replaced in a few weeks.
On farms, check whether cheese making and the shop are part of the agricultural policy or need their own cover.
Why NAMMERT for your business
We look at the cellar and the cooling
Ripening stock and spoilage are the most expensive gaps in the sector. As an insurance broker, Norman Nammert obtains quotes from several insurers and compares exactly these points.
Claims handling seen from the inside
From boat insurance we know claims handling from our own work. That helps to set values and records correctly when the policy is taken out.
Farm, business and family in one place
Dairy, vehicles, farm shop and your private cover come together with one contact who can explain German policies in English.
The Nammert family has arranged insurance since 1989
Many cheese makers are family businesses, and so are we. Our work is free for you; the insurer pays our commission.
Frequently asked questions
Questions and answers
Is insurance compulsory for a cheese dairy?
Not by law.
But you are liable without fault under the Product Liability Act,
and retailers usually ask for proof of product liability cover.
What does insurance cost for a farm creamery?
In our quoting, liability, contents and machinery usually come to €1,500 to €4,000 a year,
depending on the value of the ripening stock.
Does liability pay if customers get ill from listeria?
Yes, product liability pays for harm to health caused by your product and defends unjustified
claims.
The recall itself is only paid by a separate extension.
How do I insure cheese that is still ripening?
With a sum that covers a full cellar.
Many insurers offer declaration or peak value arrangements for stock that changes over the year.
Are my employees covered for accidents?
Yes, employees are insured by law under Social Code Book VII through the responsible
Berufsgenossenschaft.
Is a farm creamery covered by my agricultural policy?
Sometimes, but often only within limits.
Processing and selling are frequently treated as commercial activities and need their own cover.
NAMMERT insurance broker
Request quotes for Cheese dairy
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.