Insurance for flour mills, oil mills and mills with a farm shop in Germany
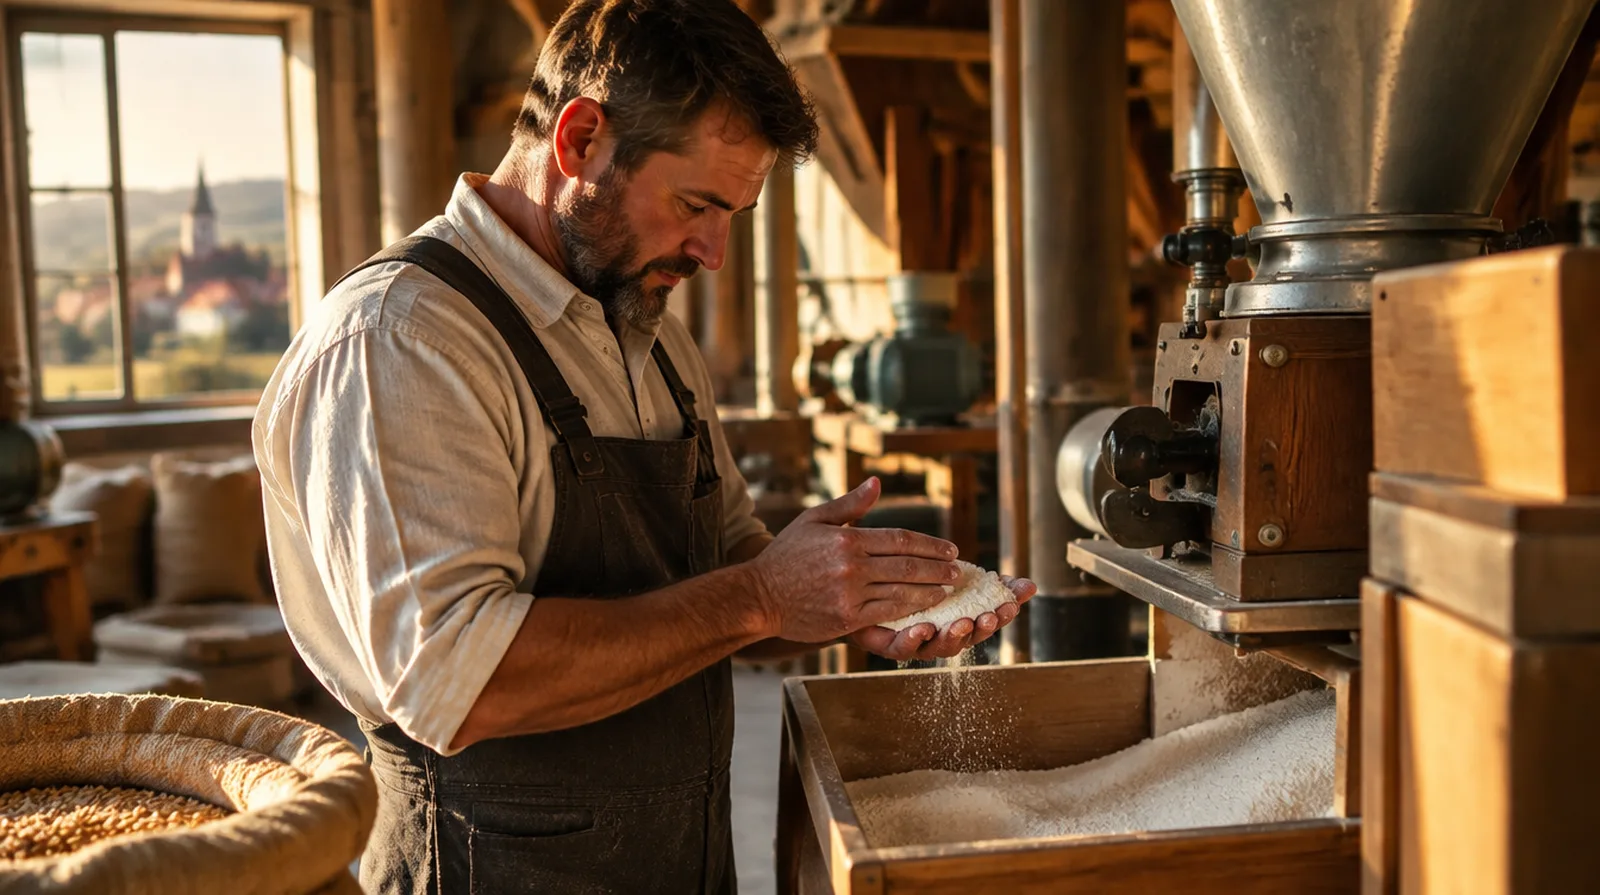
Flour dust burns like tinder, many mills have stood right on the water for centuries, and a broken roller mill stops all milling. For flour mills, oil mills and mills with a farm shop, fire, flooding and downtime are the big issues, plus liability for flour and oil at the customer's end. This page explains what to cover in Germany and what it costs.
Can I get fire insurance for an old mill by a stream?
Usually yes, but insurers ask detailed questions: construction, age of the wiring, dust extraction, fire detectors and distance to the water decide the premium and whether flooding is included. Well documented maintenance and renovation lower the premium noticeably, and a broker can approach several insurers at once.
What goes wrong in this trade
01
Dust explosion and fire
Fine flour dust, an overheated bearing or a spark in the elevator are enough for an explosion. Old timber floors burn quickly.
02
Flooding
Many mills stand right by a river or mill race. Heavy rain and floods fill the basement, drive and store.
03
Roller mill and drive
If a roller or gearbox breaks, milling stops. Parts for older plants take weeks.
04
Foreign bodies and contaminants
Stones, metal parts or contaminated grain end up in the flour, and bakeries reject whole deliveries.
05
Silo and falls
Work in silos, on platforms and on conveyors is among the most dangerous in the business.
06
Valuable old building
Listed mills are expensive to rebuild; a sum insured that is too low hurts after a fire.
For mills with digital controls, stock management and an online shop.
What it costs: example prices
For mills, fire and buildings insurance makes up most of the premium. Construction, dust protection, location by the water and rebuilding value count more than turnover.
Insurance
Example
Typical range
Business liability
Small mill with farm shop supplying local bakers
around €400 to €1,100 a year
Commercial buildings
Mill building with silo, rebuilding value €1.5 million, without flooding
around €2,500 to €7,000 a year
Business contents
Milling plant and stock worth €600,000
around €1,200 to €3,500 a year
Machinery breakdown
Roller mills, sifters and drives with a new value of €500,000
around €1,000 to €3,000 a year
Business interruption
Business interruption with a 12 month indemnity period, together with fire cover
around €800 to €2,500 a year
For comparison: Fire insurance for a medium sized mill costs roughly as much a year as ten tonnes of bread wheat on the market.
Guide figures from our quoting, as of October 2026, excluding German insurance tax.
Mills are rated individually; there are no published tariffs.
The sources support the legal statements on this page; we obtain the exact quote for you.
Six things that really happen to mills, all on one stormy day. Tap through and see who pays.
Damage so far€954,500
A roller mill breaks and milling stops. The spare part arrives in three weeks.
€38,000 · Paid by: Machinery breakdown
A bakery reports metal in the flour. Two batches of bread must be destroyed.
€14,000 · Paid by: Business liability
A visitor trips on a step in the farm shop and injures his knee.
€5,500 · Paid by: Business liability
After heavy rain the mill stream bursts its banks; the basement with drive and flour store is flooded.
€95,000 · Paid by: Commercial buildings
The soaked flour in the store is lost.
€22,000 · Paid by: Business contents
An overheated bearing ignites dust in the elevator and the fire spreads to the milling floors.
€780,000 · Paid by: Commercial buildings
Which package would you have had?
Paid by insurance: €0
Out of your own pocket: €954,500
Illustrative amounts before any excess.
What is paid depends on the policy terms.
Practical tips from your broker
Have the rebuilding value of the mill assessed; for old and listed buildings it is often far above the purchase price.
Check flooding and heavy rain expressly; mills by the water do not get them automatically.
Document dust extraction, cleaning and bearing maintenance; it lowers the premium and helps after a loss.
Agree an indemnity period in business interruption that matches the time to replace the milling plant, usually 12 to 24 months.
If you supply bakeries, include consequential losses at the customer in product liability, such as destroyed bread.
Check whether water wheel, turbine and weir are covered by the buildings policy.
Why NAMMERT for your business
We know old buildings by the water
Boats and harbours are on the water, and so are mills. As an insurance broker, Norman Nammert obtains quotes from several insurers and watches flooding, weir and rebuilding value.
Claims handling seen from the inside
From boat insurance we know claims handling from our own work. That helps to set sums and records correctly when the policy is taken out.
Mill, farm and family in one place
Buildings, vehicles, farm shop and your private cover come together with one contact who can explain German policies in English.
The Nammert family has arranged insurance since 1989
Many mills have been in family hands for generations, and we work the same way. Our work is free for you; the insurer pays our commission.
Frequently asked questions
Questions and answers
Is insurance compulsory for a mill?
Not by law.
Banks usually require fire insurance when they finance,
and under the Product Liability Act you are liable without fault for defective flour or oil.
Do I need a master craftsman qualification to run a mill?
No.
The miller trade is listed in Annex B section 1 of the Crafts Code and needs no master
qualification.
What does insurance cost for a small mill?
In our quoting, buildings, contents and liability usually come to €2,500 to €6,000 a year.
Rebuilding value and fire protection make the difference.
Is flooding covered for a mill?
Only with natural hazard cover.
For mills right by the water insurers assess the location individually and often ask for a higher
excess.
Does insurance pay if we cannot deliver after a fire?
Only business interruption cover.
It pays running costs and lost profit if the standstill results from insured property damage.
Are my employees covered for accidents?
Yes, employees are insured by law under Social Code Book VII through the responsible
Berufsgenossenschaft.
NAMMERT insurance broker
Request quotes for Mill
The recommended covers are ticked.
Change what does not fit; we compare quotes, in English.
Thank you, we have your request.
We will be in touch within one working day. If it is urgent: +49 3375 29 12 77.