Magazine / Magazine: Boat and season
Quicksilver Activ Cabin 455 insurance check: setting the insured value right
Part 2 of the series: no market values and no amounts. How policy wordings deal with the value of a small cuddy cabin boat and what tends to be left out.
30 October 20266 min readNAMMERT Assekuradeur GmbH
The second part of this series is about the figure everything depends on after a total loss: the insured value. As in part one, we have not driven the Quicksilver Activ Cabin 455 and we do not value it. We give no market values and no amounts. What a small motor boat with a cuddy cabin is worth depends on condition, year, outboard, equipment and care, and only someone looking at the individual boat can judge that. What we can explain is how policy wordings deal with the value you state on the proposal, and which items tend to be left out. On a small boat the engine and the trailer make up a large share of the whole, and in most contracts both are separate items. Like the rest of this insurance check, this part is about setting the figure right, not about testing the boat.
First, the difference that matters after a total loss. Some hull policies settle on actual cash value: the cost of a boat of the same kind and quality on the day of the loss, minus a deduction for age, wear and use, sometimes on a fixed scale that grows with the age of the boat. Others work with an agreed value, a sum fixed in the schedule by mutual agreement when the contract is made. With an agreed value, the figure is not estimated after the loss but settled at the start. That is why it pays to set it carefully, and why it is worth reading which basis of settlement your own wording uses before anything happens.
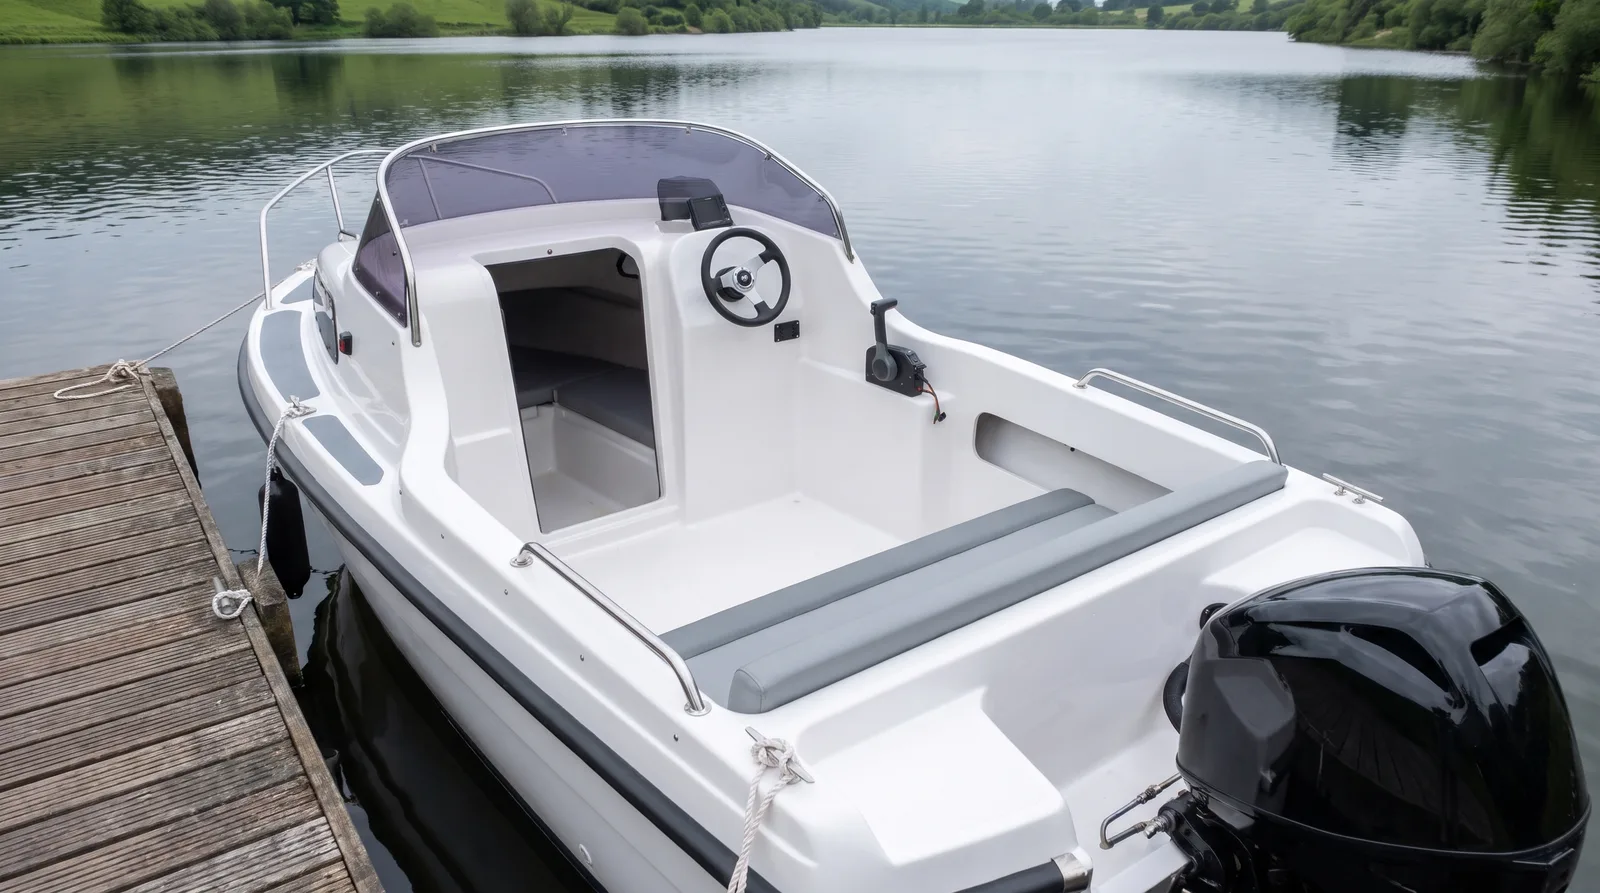
The outboard is the item most often entered wrongly. Many wordings do not include it in the sum insured for the boat but require its own value in the schedule; if that line is missing, the outboard may not be insured at all. Replacing the engine or fitting a more powerful one changes the value and often the risk as well. Some policies oblige you to report an increase in value from upgrades and only cover the change once you have proved it, others allow the sum to be raised at any time against invoices or a survey. Either way, keep the engine invoice with the paperwork for the boat.
Then the things that tend to be forgotten. Hull cover typically includes the boat with its fixed parts, navigation equipment such as a handheld VHF or a plotter, accessories and inventory. On a small cuddy boat that means items like the cover, the cabin cushions, the echo sounder, the swim ladder and the bow rail. Wordings rarely list them one by one, so their value belongs in the sum insured. Personal belongings such as phones or glasses are a different matter: some policies include them within fixed limits, others exclude them entirely. They do not belong in the sum insured for the boat.
Many small boats spend the winter at home rather than in a yard, and parts come off. Some wordings keep equipment, inventory and the outboard covered when they are stored apart from the boat in a locked room or building, often with other insurance taking precedence. Others do not mention this at all, and then the question is open. Two exclusions are found in many hull wordings regardless: weather such as rain, frost or sun is excluded unless it follows a storm, and theft of loose items that were not properly packed, covered and lashed down is not paid. A cover worn out by the sun is wear; a cover torn by a storm is a claim.
The trailer is a separate object with its own value. Many policies cover it under the hull section only if it is named in the schedule with a sum insured, and some do not apply the deductible to it. Damage to the trailer is often limited to certain causes, for instance an accident involving the boat, storm, lightning, fire, explosion or theft. Theft conditions are common: the trailer must be locked against unauthorised uncoupling while hitched, and against hitching when parked, for example with a wheel clamp. What that means on the road and at the ramp is the subject of part four of this series.
Finally, time. A value that was right at purchase is often wrong a few years later, in either direction. A new outboard, new electronics or re-covered cushions raise it; age and use lower it, and the sum also drives what you pay. For partial losses, some wordings pay the necessary repair costs without deductions for age unless agreed otherwise, while others apply an age scale. It is worth reading the contract once a year, ideally when the boat is laid up for winter. Part three of this series looks at the damage that is typical for a small motor boat.
Insurance checkPart 2 of 4
Quicksilver Activ Cabin 455: an insurance check
All parts at a glance
- Quicksilver Activ Cabin 455 insurance check (Policy)
- Quicksilver Activ Cabin 455 insurance check (Value)
- Quicksilver Activ Cabin 455 insurance check (Damage)
- Quicksilver Activ Cabin 455 insurance check (On the move)
Worth checking
Common questions
How much should I insure my Quicksilver Activ Cabin 455 for?
We do not give a figure because it depends on the individual boat. The yardstick is what a boat of the same kind and quality with this engine and this equipment would cost. Invoices or a survey are the best basis.
Is the outboard part of the sum insured for the boat?
In many wordings it is not. It needs its own value in the schedule, and if it is missing there the outboard may not be insured, even though it hangs on the transom.
Are cushions and electronics in my cellar covered over the winter?
That depends on the wording. Some policies keep equipment covered when it is stored apart from the boat in a locked room, often with household insurance taking precedence. Check this clause before you carry everything indoors.
Related
