Magazine / Magazine: Boat and season
Quicksilver Activ Cabin 455 insurance check: trailer, ramp, storage and travel abroad
Part 4 of the series: road, ramp, jetty, garage and travel abroad. Where policy wordings for a small trailer boat run into everyday life, and what applies behind the boat.
30 October 20267 min readNAMMERT Assekuradeur GmbH
In the fourth and last part of this series the Quicksilver Activ Cabin 455 is on the move, in the places where a small motor boat spends a lot of time when it is not running: on the trailer, at the slipway, at the jetty, in the garage and in winter storage. What was said in part one still applies: we have not driven the boat and make no judgement on handling or build. This part is about the points where policy wordings for a trailer boat run into everyday life, and about the questions asked first after damage on the road, at the ramp or abroad. A boat of this size is easy to move, which is exactly why these questions come up so often. This insurance check stays with the contract, including for travel abroad.
On the road, hull cover usually continues while the boat is carried on a suitable means of transport. Damage caused by improper loading and securing during transport is commonly excluded, so a strap that comes loose on the motorway is a matter of load security rather than a hull claim, and the same goes for an outboard rolling around in the boot of the car. Damage the trailer causes to others while being towed is normally a matter for the motor insurance of the towing vehicle. Some boat liability wordings step in for the unhitched trailer, for example one that rolls away on a slope, where the car insurance does not respond; others say nothing about it.
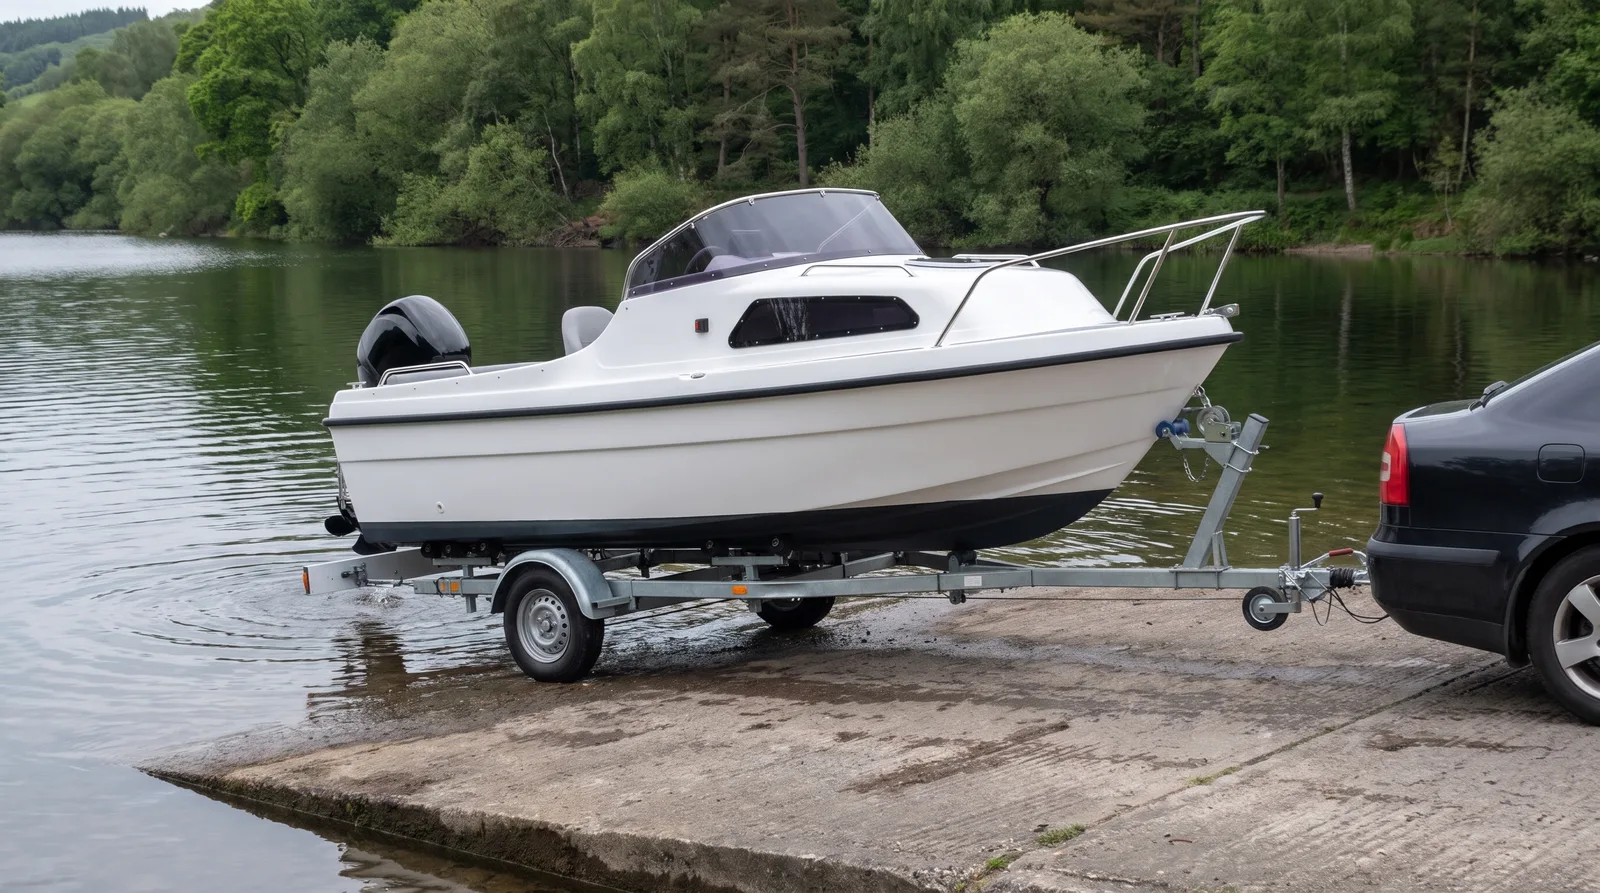
At the ramp, many hull wordings expressly include hauling out and launching. Whether damage there is covered depends on what happened and on the level of cover. If the boat slides off the trailer and hits the edge of the ramp, that is accidental damage, which basic named-perils cover often does not include. If you injure yourself at the slipway, the personal accident section is the place to look, and wordings differ on whether launching and recovery are expressly within its scope. What happens when the car itself rolls into the water is the subject of a separate article in our magazine.
At a mooring, policies typically require a place that is objectively suitable for boats. Many hull wordings exclude damage if the boat is left unattended off an open coast for longer than a set number of hours without anyone able to move it when danger threatens. For the jetty itself, liability cover is the relevant section, and some wordings expressly include damage to jetties used for mooring and to rented storage spaces or parking bays. That can matter for the rented space where the boat and trailer are kept between trips.
Many small boats spend the winter at home, in a garage, under a carport or in the garden. Hull cover usually continues on land, but for theft and vandalism the place matters: many wordings exclude both if the boat was stored somewhere not fenced and locked, or in a building that is not locked. A locked garage meets that condition, an open carport does not. A parked trailer often needs a hitch lock or a wheel clamp. Frost is weather and commonly excluded. And one limit to know in advance: a seasonal policy that charges only for the boating months may provide no cover at all outside them, including in winter storage, so read its dates before laying up.
With a trailer, another country is a day's drive away, whether that is Lake Garda, Croatia or the Danish coast. What decides is the cruising area in the schedule, as described in part one: inland waters in Europe are not the same as the Adriatic. Liability cover usually extends to incidents abroad, though some wordings count defence costs abroad against the sum insured. Hull wordings commonly exclude damage if the boat was skippered without a licence required for that area. An engine that may be run without a licence at home may need one in the destination country, and some lakes ban combustion engines altogether. Settle this before you set off.
Finally, what happens behind the boat. Towing children on an inflatable is tempting even with a small motor boat. Some liability wordings expressly include towing water skiers, wakeboarders and inflatables; in others the point is not mentioned, and then it is worth asking before the first run. The personal liability of the person being towed is normally not part of the boat cover, and claims by relatives in the same household are often excluded. For your own children on the inflatable, the personal accident section is therefore the place to look. That ends the series; parts one to three deal with the policy, the value and typical damage.
Insurance checkPart 4 of 4
Quicksilver Activ Cabin 455: an insurance check
All parts at a glance
- Quicksilver Activ Cabin 455 insurance check (Policy)
- Quicksilver Activ Cabin 455 insurance check (Value)
- Quicksilver Activ Cabin 455 insurance check (Damage)
- Quicksilver Activ Cabin 455 insurance check (On the move)
Worth checking
Common questions
Is my boat covered while launching at a slipway?
Many hull wordings expressly include hauling out and launching. Damage from the boat sliding off or striking the ramp is accidental damage, though, and basic named-perils cover often does not include that.
Is a carport good enough for winter storage?
For theft and vandalism often not. An open carport is neither a locked building nor a fenced and locked area, and many wordings exclude both risks there. A locked garage usually meets the condition.
Does a seasonal policy cover the boat in winter storage?
Often not. A seasonal policy that charges only for the boating months may provide no cover outside them, including in storage and in your own garage. Read the dates in the schedule.
Related
