Sea-Doo RXP-XRS 300 insurance check: typical jet ski damage and the wording behind it
Part three of this insurance check looks at the damage typical for jet skis and the wording that decides each claim. It is about the type of craft, not about this model in particular.
11 October 20268 min readNAMMERT Assekuradeur GmbH
The third part of this insurance check turns from paperwork to events and to the wording behind each claim. Part one covered what the policy should say, part two the insured value; this part is about what actually happens to jet skis. One point first: the damage described here is typical for jet skis as a type of craft, not for the Sea-Doo RXP-XRS 300 in particular. Nobody here has ridden the model, and nothing in this text suggests it is prone to any kind of damage. What follows is how hull, accident and liability wordings commonly deal with the claims that come up again and again with jet skis, and which clauses to look for in your own contract before the season.
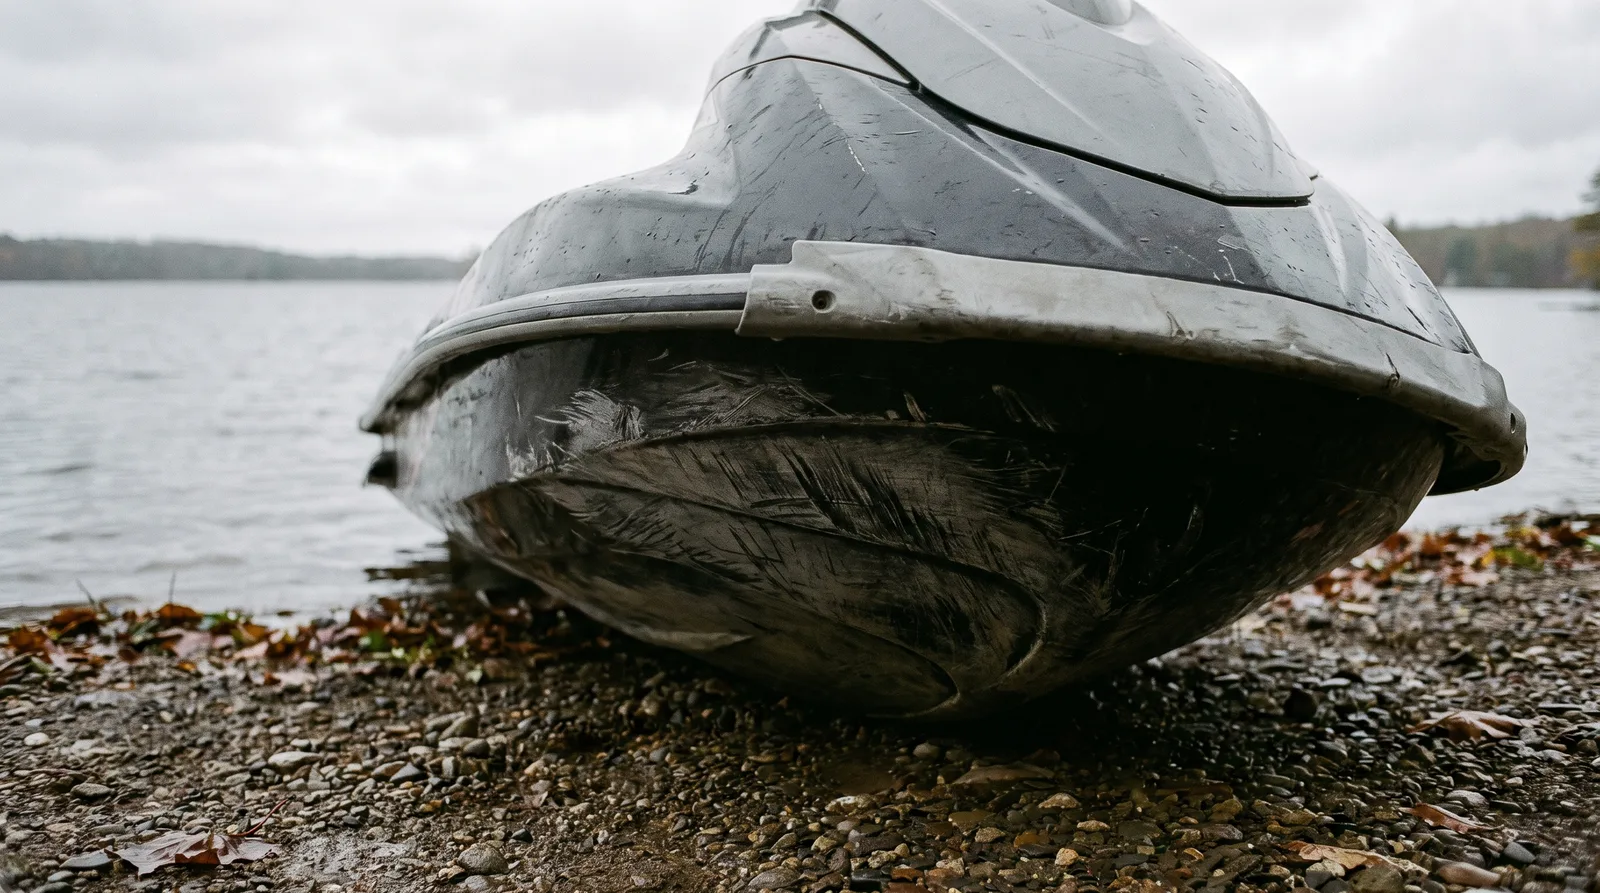
Collision and grounding are accident events. Broader hull covers usually name them explicitly, together with striking fixed or floating objects, while narrower covers limited to named hazards such as storm, fire and theft do not include them at all. Some wordings also pay for an inspection after a reported grounding, with or without a limit. Jet ski clauses often add a specific hull exclusion: damage that does not impair the normal use of the craft is not paid. A scratch from a gravel beach that does not affect riding is then not a claim. Check too how the deductible is handled, because jet ski clauses frequently deduct it from every claim, including total loss and theft.
One kind of damage is peculiar to jet skis and concerns the drive. A jet pump draws in water, and with it sometimes rope, gravel, weed or plastic. The question for the insurer is the same as with a rope round a propeller: was it an external event or wear and operating damage? Operating damage to machinery, wear and poor maintenance are excluded in most hull wordings, and optional machinery covers sometimes leave out jet skis entirely. Many jet ski clauses also exclude engine damage from water ingestion unless it is the direct result of a collision with a fixed object. If you find debris in the intake, keep it and photograph it before the workshop throws it away; it may be the only evidence of an external event.
Theft is where policies differ most. Narrow covers often insure only theft of the whole craft, broader ones add break-in, theft of parts and malicious damage. Jet ski clauses commonly require the craft to be secured against unauthorised use, at night and whenever the owner is away for a longer period, winter storage included; typical examples are a locked building or plot, a jet ski dock with a security cable or protected storage in a marina. Many wordings refuse theft claims when the craft stood ashore on an open, unfenced plot. Some lift that condition but double the deductible unless the jet ski was kept locked away. Read this clause before you choose where the craft spends the night.
The passenger is the case most often underestimated. Personal accident covers attached to a boat policy differ in whom they protect: sometimes only the owner, sometimes the owner and close family, sometimes every authorised person on board. Some divide the sum insured by the number of people aboard at the time of the accident. Cover usually applies worldwide, but only in connection with the use of the craft, not around the clock. Some covers grant jet ski riders a higher benefit for a head injury if a standard helmet was worn, typically for the rider only. Check before you take anyone along, and wear the helmet whether or not the policy rewards it.
Then liability, which matters a great deal on a jet ski because swimmers, bathers and other craft are often close. Liability cover pays for injury and damage to third parties for which you are legally liable. If a passenger is hurt, it pays only where the rider is liable, and many wordings exclude claims by relatives living in the same household. Towing water skiers, wakeboarders or inflatables may be included or excluded; look for the clause. Finally, gross negligence: hull wordings may reduce a payment in proportion to the fault, and some waive that reduction up to a share of the sum insured, though rarely for theft, drugs or alcohol. Racing and training are the subject of part four.
Insurance checkPart 3 of 4
Sea-Doo RXP-XRS 300: an insurance check
All parts at a glance
- Sea-Doo RXP-XRS 300 insurance check
- Sea-Doo RXP-XRS 300 insurance check
- Sea-Doo RXP-XRS 300 insurance check
- Sea-Doo RXP-XRS 300 insurance check
Worth checking
Common questions
Will hull cover pay for scratches on a jet ski?
Often not. Many jet ski clauses exclude hull damage that does not impair the normal use of the craft. Damage that does impair use and results from an insured event, such as a collision, is a different matter if the policy includes accident cover.
Is my passenger covered by personal accident insurance?
That depends entirely on the wording. Some covers protect only the owner, some the owner and close family, some everyone authorised on board, and some divide the sum by the number of people aboard. Check before the first ride together.
What about engine damage after the jet pump sucked in debris?
The key is proving an external event. Operating damage is usually excluded, and engine damage from water ingestion often too unless it follows a collision with a fixed object. Keep what was sucked in and report the claim before repairs start.
Related